Travel Trailer Insurance Coverage Explained: Costs and Claims
Travel trailer insurance coverage explained: learn how physical damage, liability, and add-ons protect your trailer and avoid costly gaps after an accident.
By John Miller
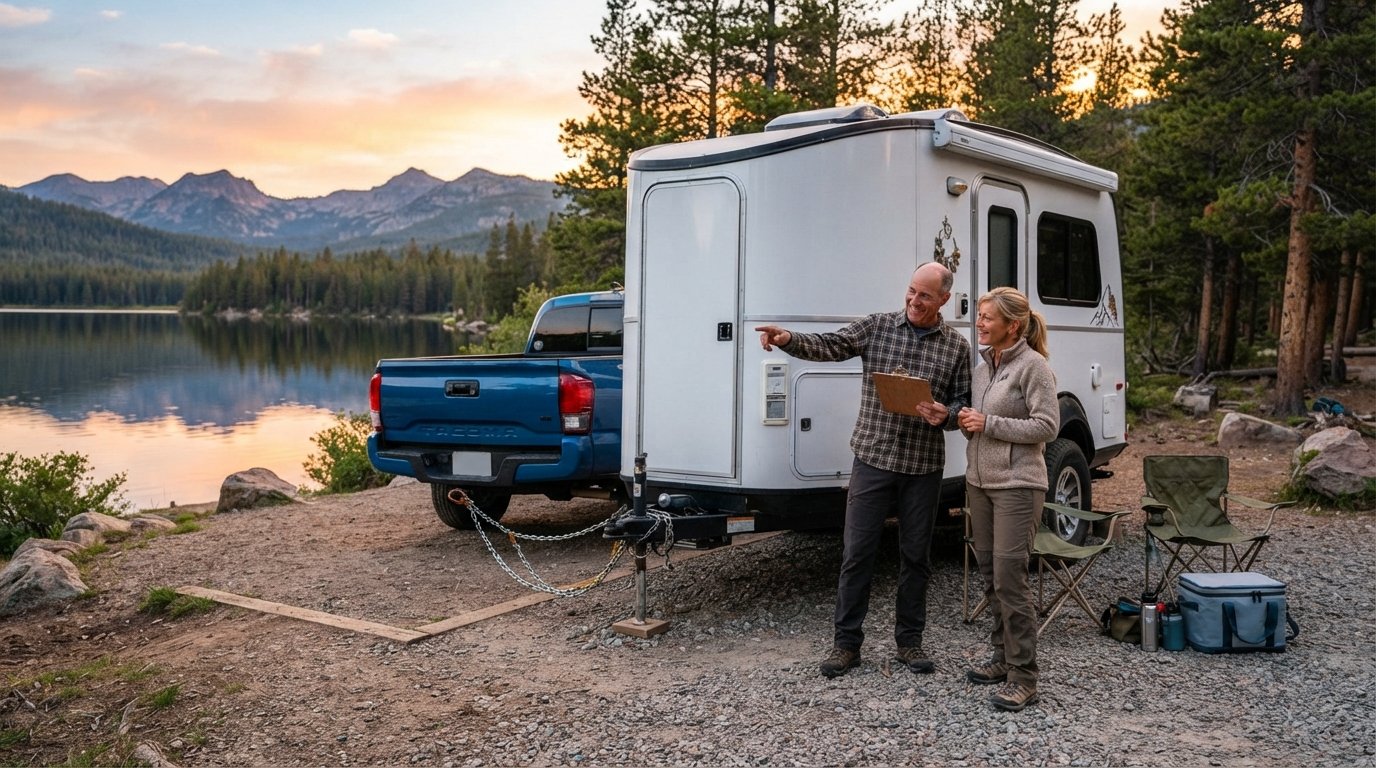
Your travel trailer is more than a weekend accessory. It is a rolling investment in family trips, cross-country adventures, and quiet mornings by a lake. Yet many owners spend hours comparing tow hitches and floor plans while giving almost no thought to the policy that protects the trailer itself. That gap matters, because a travel trailer sits in an unusual insurance category: it is not quite a car, not quite a home, and not automatically covered by the policy on the truck that pulls it. Understanding how travel trailer insurance coverage works, what each component pays for, and where the gaps hide is the difference between a quick claim payout and a financial headache after an accident.
This guide walks through the full picture. You will learn how coverage is structured, why your tow vehicle's policy usually falls short, which add-ons are worth the money, how premiums are calculated, and what happens when you file a claim. The goal is simple: help you make an informed decision before something goes wrong, not after.
Why Your Tow Vehicle's Policy Is Not Enough
A common and costly misconception is that the auto policy on your truck or SUV automatically extends full protection to whatever you are towing. In reality, liability coverage on a tow vehicle typically does follow the trailer in a limited way. If your trailer swings into another car while you are driving, your auto liability may respond. But that is where the extension usually stops. Physical damage to the trailer itself, your personal belongings inside it, and injuries or losses that occur once the trailer is unhitched and parked at a campsite are generally excluded.
Think about what that means in practice. A sway event on the highway damages the trailer's side panel and axle. Your auto collision coverage may not pay for the trailer repair because the trailer is not a listed vehicle on that policy. A windstorm flips the trailer while it sits in a storage lot. Your auto policy is not involved at all. A thief breaks in at a campground and takes a generator, a laptop, and camping gear. Again, the auto policy is silent.
This is why a dedicated travel trailer policy, or a carefully structured endorsement on an existing policy, exists. It fills the gaps that a standard auto policy leaves open. Some insurers allow you to add a travel trailer as a listed item, while others require a separate recreational vehicle policy. Either way, the coverage needs to be arranged deliberately. If you are already comparing options for your everyday vehicle, the same logic applies here: specialized vehicles need specialized coverage, and you can review how broad protection is structured in this guide to find affordable comprehensive insurance coverage before you decide.
The Core Coverage Components Explained
Travel trailer insurance is best understood as a bundle of distinct protections, each responding to a different type of loss. No single component covers everything, and the right combination depends on your trailer's value, how you use it, and where you store it. Here are the main pieces you will encounter on a quote.
- Physical damage coverage (collision and comprehensive): Pays to repair or replace the trailer after a collision, fire, theft, vandalism, hail, or falling objects. Collision handles impact with another vehicle or object; comprehensive handles everything else.
- Liability coverage: Pays for injuries or property damage you cause to others while towing or using the trailer. This is often the legal minimum required in many states.
- Medical payments or personal injury protection: Covers medical expenses for you and your passengers after an accident, regardless of fault in some states.
- Uninsured and underinsured motorist coverage: Protects you when a driver with no insurance or too little insurance hits you and causes injury or damage.
- Personal effects coverage: Reimburses you for belongings inside the trailer, such as clothing, electronics, cookware, and camping gear, up to a stated limit.
Beyond these core elements, several endorsements can be added. Vacation liability coverage, for example, protects you if a guest is injured at your campsite or you accidentally cause damage to campground property. Total loss replacement can pay for a brand-new comparable trailer instead of a depreciated value. Emergency expense coverage can reimburse hotel and travel costs if your trailer becomes uninhabitable far from home. Each add-on has a cost, and each solves a specific problem, so the right mix depends on how and where you camp.
One important distinction is between actual cash value and agreed value settlements. Actual cash value pays what the trailer is worth at the time of loss, which is less than you paid. Agreed value pays a pre-set amount established when the policy begins. For newer trailers, agreed value or total loss replacement is often worth the extra premium because depreciation on recreational vehicles can be steep in the first few years.
How Insurers Calculate Your Travel Trailer Premium
Premiums for travel trailer insurance are not random. Insurers weigh a set of risk factors that predict how likely you are to file a claim and how expensive that claim might be. Understanding these factors gives you leverage when you shop, because you can adjust some of them before you buy.
The first factor is the trailer itself: its make, model, year, length, and purchase price. A large fifth-wheel with premium finishes costs more to repair and replace than a small folding camper, so it carries a higher base rate. The second factor is usage. Full-time travelers who live in their trailer for months at a time are seen as higher risk than weekend campers who store the unit most of the year. The third factor is storage. A trailer kept in a locked, gated facility or a private garage is cheaper to insure than one parked on an open street or in an unsecured lot.
Your driving record and claims history also matter, especially if the policy is bundled with your auto insurance. A clean record can unlock meaningful discounts, while at-fault accidents and prior claims push rates up. Finally, the deductibles you choose directly affect your premium. A higher deductible lowers your monthly cost but increases what you pay out of pocket after a loss. Choosing a deductible is a balancing act between affordability today and resilience tomorrow.
Discount opportunities are worth asking about directly. Common ones include:
- Bundling the trailer policy with your auto or homeowners insurance
- Belonging to a recognized camping or RV association
- Completing a defensive driving or RV safety course
- Paying the full annual premium upfront instead of monthly
- Having a claims-free history for a set number of years
These discounts can stack, and even modest percentage reductions add up over a season of travel. The key is to ask specifically which discounts a carrier offers rather than assuming they will be applied automatically.
What Happens When You File a Travel Trailer Claim
Knowing the claims process in advance removes much of the stress from an already stressful situation. The steps are straightforward, but the details you document in the first hour after a loss can shape the outcome of your claim for weeks afterward.
- Ensure safety first. Move to a safe location, check for injuries, and call emergency services if anyone is hurt.
- Document everything. Take photos and videos of the damage, the surrounding scene, and any other vehicles involved. Note the date, time, location, and weather conditions.
- Report the incident. Contact your insurer as soon as practical. Most policies require prompt notice, and delays can complicate a claim.
- Collect information. Exchange names, contact details, insurance information, and license plate numbers with any other parties involved.
- Keep records. Save receipts for emergency repairs, towing, lodging, and any other expenses related to the loss.
After you file, an adjuster will inspect the damage and estimate the repair or replacement cost. If the trailer is a total loss, the settlement will follow either actual cash value or agreed value, depending on your policy. This is the moment when the coverage choices you made at purchase become real money. A policy with agreed value and total loss replacement can mean the difference between replacing your trailer and absorbing a significant loss yourself.
One practical tip: keep a current inventory of everything stored inside your trailer, with photos and approximate values. Personal effects coverage has limits, and a documented inventory makes it far easier to recover what you are owed. Store a copy of that inventory somewhere other than the trailer itself, such as in cloud storage, so it survives the loss.
Matching Coverage to How You Actually Travel
There is no single best travel trailer policy, because no two owners travel the same way. A retired couple who spends six months a year on the road has very different needs from a family that takes three weekend trips each summer. The right approach is to match coverage to usage, then adjust as circumstances change.
Weekend and seasonal campers can often get by with physical damage coverage, liability, and a modest personal effects limit. The trailer spends most of its life in storage, so storage-related risks like theft and weather damage deserve attention. Full-time travelers, by contrast, should look closely at vacation liability, emergency expense coverage, and higher personal effects limits, because the trailer functions as their home and a single loss can displace them entirely. Owners of high-value or custom trailers should weigh agreed value coverage carefully, since standard actual cash value settlements may fall well short of replacement cost.
It also helps to revisit your policy whenever your situation changes. Buying a larger trailer, switching to full-time travel, moving to a new state, or paying off the loan are all events that can change what coverage makes sense. A policy that fit two years ago may leave you exposed today. Reviewing it annually, ideally before your camping season begins, keeps your protection aligned with your life.
When you are ready to compare options, gathering quotes from multiple sources is the fastest way to see how much rates vary for the same trailer and the same coverage. A platform like FreeAutoInsuranceQuotesOnline lets you request quotes from several carriers at once, which makes it easier to spot both genuine savings and overpriced policies. Pair that with a clear understanding of your own coverage needs, and you can shop with confidence rather than guesswork.
Travel trailer insurance coverage is ultimately about protecting a lifestyle, not just a vehicle. The right policy keeps a blown tire, a hailstorm, or a campground theft from turning into a financial setback. Take the time to understand each component, ask about discounts, document your belongings, and review your policy as your travels evolve. Do that, and your trailer will remain what it was meant to be: a source of good trips and better memories.