What Is Medical Payments Coverage and Do I Need It?
Understand what medical payments coverage is and whether you need it. Call (833)-214-7506 to compare options and protect against surprise medical bills.
By Sienna Vale
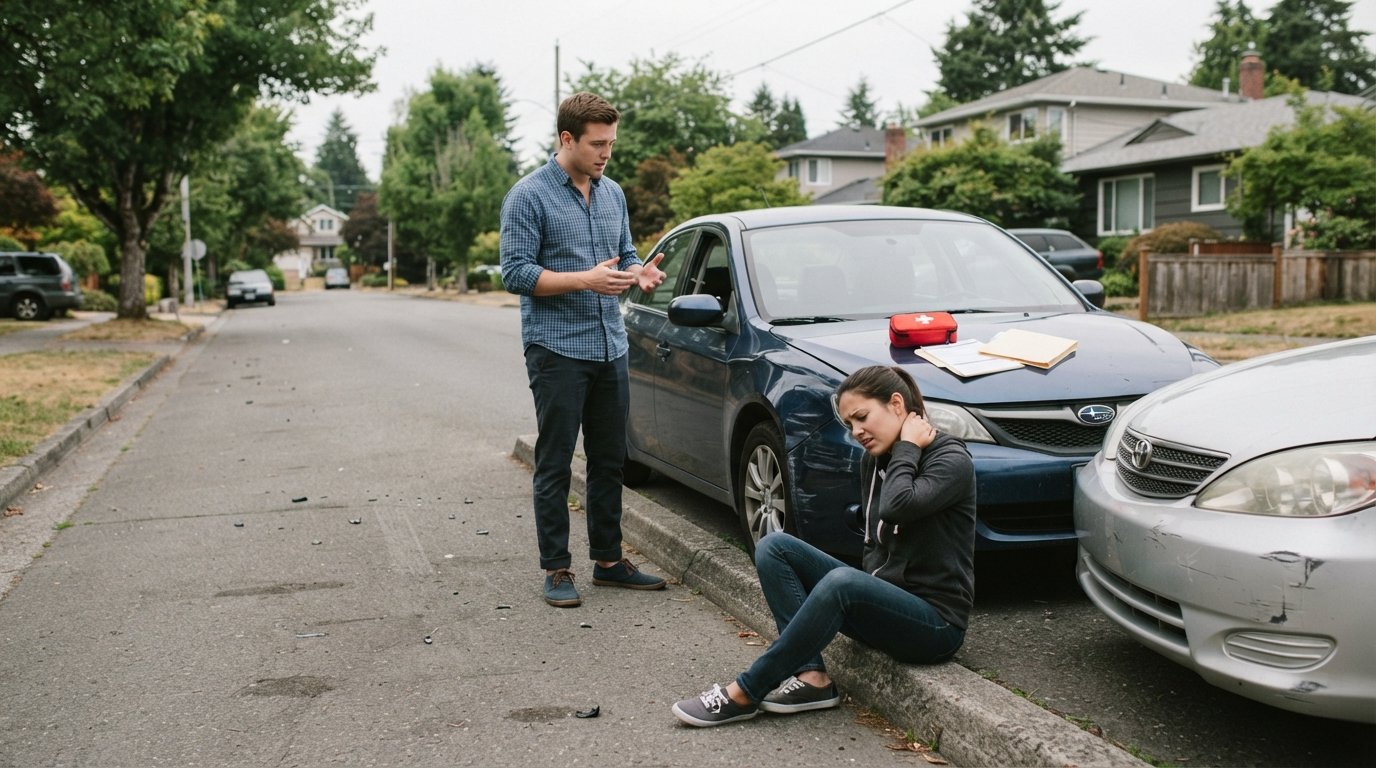
Imagine a minor fender bender where your passenger complains of neck pain. Your health insurance might cover the visit, but the deductible and co-pay are due upfront. Medical payments coverage, often called MedPay, is designed to fill that gap without waiting for a liability determination. It pays for reasonable and necessary medical expenses for you and your passengers after a car accident, regardless of who caused the crash. Understanding what medical payments coverage is and whether you need it can save you from surprise bills and stressful reimbursement battles.
This guide breaks down how MedPay works, how it differs from personal injury protection (PIP) and health insurance, who benefits most, typical limits and costs, and how to decide if it belongs in your auto policy. The goal is straightforward: help you make an informed choice rather than guess based on generic advice.
How Medical Payments Coverage Works (and What It Pays For)
Medical payments coverage is an optional auto insurance coverage that pays for medical and funeral expenses for you and your passengers after a car accident. The key feature is that it pays regardless of fault. If you are hit by another driver, your MedPay can respond immediately. If you cause the accident, MedPay still responds for your own injuries and those of your passengers. The coverage typically applies to reasonable and necessary expenses incurred within a certain time frame after the accident, often three years from the date of loss, though policy language varies by insurer and state.
MedPay generally covers a range of accident-related medical costs, including emergency room visits, ambulance fees, doctor visits, hospital stays, X-rays, surgery, and sometimes dental care resulting from the accident. Some policies also cover funeral expenses. It does not cover lost wages or pain and suffering; those fall under other coverages or legal claims. MedPay is a no-fault benefit in the sense that it pays without waiting for a liability investigation, but it is not the same as a formal no-fault system like PIP.
One practical way to think about MedPay is as a fast, small-dollar medical wallet attached to your auto policy. It can pay providers directly or reimburse you, depending on the insurer and the situation. For a deeper look at how this coverage fits into a broader auto policy, see this guide on auto insurance with medical payments coverage. The takeaway: MedPay is a simple, fault-free way to access medical care after a crash, but it has limits and does not replace health insurance or liability coverage.
MedPay vs. PIP vs. Health Insurance: Key Differences
The most common confusion involves MedPay, personal injury protection (PIP), and health insurance. They overlap in some ways but serve different purposes and operate under different rules. Understanding these differences is essential to answering whether you need MedPay.
MedPay is optional in most states and pays medical expenses for you and your passengers after an accident, regardless of fault. It has a per-person limit and sometimes a per-accident limit. It does not cover lost wages or rehabilitation in most cases. PIP, by contrast, is required in no-fault states and typically covers a broader set of expenses, including medical bills, lost wages, and sometimes essential services like childcare or housekeeping. PIP limits are often higher than MedPay limits, and PIP may have deductibles and coordination-of-benefits rules. Health insurance covers medical care broadly but comes with networks, deductibles, co-pays, and prior authorization requirements. Health insurance also may seek reimbursement from a settlement or from other coverage, a process known as subrogation.
Here is a quick comparison to clarify the differences:
- MedPay: Optional in most states; pays medical and funeral expenses for you and passengers regardless of fault; lower limits; no wage loss coverage; fast payment.
- PIP: Required in no-fault states; covers medical, wage loss, and sometimes rehabilitation; higher limits; may have deductibles; broader benefits.
- Health insurance: Covers medical care broadly; networks and co-pays apply; may seek reimbursement from auto settlements; not fault-based but may delay care due to approvals.
In practice, MedPay and health insurance can work together. MedPay can pay upfront costs like co-pays and deductibles, while health insurance covers larger bills. However, some health insurers may require you to use auto coverage first or may seek reimbursement from a MedPay payout. Coordination of benefits rules vary, so it is worth reading both policies carefully. If you live in a no-fault state with PIP, MedPay may be redundant or limited, but it can still fill gaps for passengers or for expenses PIP does not cover.
Who Benefits Most from MedPay?
MedPay is particularly valuable for certain groups and situations. The coverage follows the vehicle, so it protects you and your passengers regardless of who is driving. It also can cover family members in your household under some policies, and it may cover you as a pedestrian or cyclist if you are struck by a vehicle, depending on the policy language. That makes MedPay a useful safety net for people who frequently carry passengers, such as carpoolers, rideshare drivers (though commercial policies may be needed), and families with teen drivers.
Consider these scenarios where MedPay shines:
- You have a high-deductible health plan and want to avoid upfront costs after a minor accident.
- You often carry passengers who may not have health insurance or who have limited coverage.
- You live in a state where PIP is not required and want fault-free medical benefits.
- You want coverage for accidental injuries while riding as a passenger in someone else's car or while walking.
On the other hand, MedPay may be less necessary if you have robust health insurance with low deductibles and generous out-of-pocket maximums, or if you live in a state with strong PIP benefits. Even then, MedPay can still provide a convenient, no-fault payment source that avoids network restrictions and prior authorization delays. The decision hinges on your risk tolerance, your health coverage, and your budget.
Typical MedPay Limits and Costs
MedPay limits are usually modest compared to liability or PIP limits. Common per-person limits range from $1,000 to $10,000, with $5,000 being a popular choice. Some policies offer higher limits, and you can often choose a limit that fits your budget. The cost of adding MedPay is generally low, often just a few dollars per month, or roughly $20 to $60 per year for a $5,000 limit, depending on your state, insurer, and driving profile. That makes MedPay one of the more affordable add-ons in auto insurance.
Here is a typical example: A driver in a state without PIP adds $5,000 in MedPay for about $30 per year. After a minor accident, the driver's passenger visits an urgent care center and receives an X-ray and a splint. The total bill is $1,200. MedPay pays the bill directly, up to the limit, without waiting for fault to be determined. The passenger's health insurance is not billed, and the driver avoids a potential lawsuit or out-of-pocket payment. For $30 per year, that is a meaningful layer of financial protection.
It is important to note that MedPay limits are per person, and some policies also have a per-accident cap. Read the policy language to understand how limits apply. Also, MedPay may not cover injuries sustained while using a vehicle for business purposes or while committing a felony, and exclusions vary by state. As always, the best way to know your options is to compare quotes from multiple insurers. If you are also exploring ways to lower your overall auto loan costs, you might find resources on car loan refinancing helpful for your broader financial planning.
When MedPay Duplicates Coverage and When It Fills a Gap
MedPay can be redundant in some situations and invaluable in others. The key is to map your existing coverage against the specific gaps MedPay fills. If you have health insurance with a low deductible and low out-of-pocket maximum, MedPay may simply duplicate benefits, though it can still reduce your upfront costs. If you have a high-deductible health plan, MedPay can cover the deductible and co-pays, making care more accessible. If you have no health insurance, MedPay is a critical safety net for accident-related injuries.
MedPay also fills a gap when it comes to passengers. Your health insurance may not cover passengers in your vehicle, especially if they are not family members. MedPay covers passengers regardless of their insurance status, which can prevent awkward conversations and potential liability claims. Similarly, if you are a pedestrian or cyclist struck by a vehicle, MedPay may respond under your auto policy, depending on the policy terms. That is a gap that health insurance may not address quickly, especially if liability is disputed.
Here is a simple framework to decide if MedPay fills a gap for you:
- Review your health insurance deductible, co-pays, and out-of-pocket maximum. If they are high, MedPay can help.
- Consider how often you carry passengers, especially those without health insurance.
- Check your state's PIP requirements. If PIP is not required, MedPay is more likely to be useful.
- Evaluate your risk tolerance for surprise medical bills after an accident.
If you answer yes to two or more of these points, MedPay is likely worth considering. The cost is low, and the benefit is immediate access to care without financial friction.
Do You Need MedPay? A Practical Decision Guide
Deciding whether to add MedPay comes down to balancing cost, convenience, and existing coverage. For many drivers, MedPay is a low-cost way to avoid surprise medical bills and to ensure passengers are covered. For others, especially those with comprehensive health insurance and no passengers, it may be optional. The following questions can help you decide:
- Do you have a health insurance deductible of $1,000 or more? MedPay can cover that gap.
- Do you frequently carry passengers who may not have health insurance? MedPay protects them and reduces your liability risk.
- Do you live in a state without PIP? MedPay provides fault-free medical benefits.
- Is the annual premium for MedPay less than your expected out-of-pocket cost for a single urgent care visit? If so, it may be worth it.
It is also worth noting that MedPay can help you avoid tapping into your liability coverage, which could raise your rates if you are at fault. By using MedPay for minor injuries, you keep small claims out of the liability system. That can be a smart strategy for maintaining lower premiums over time. Of course, MedPay is not a substitute for adequate liability coverage or health insurance, but it is a useful complement.
For personalized guidance, consider speaking with a licensed insurance agent who can review your specific policy and health coverage. NewAutoInsurance.com connects drivers with licensed agents for personalized quotes, and there is no obligation to purchase. You can also call 833-214-7506 to compare options. Remember that NewAutoInsurance.com is an independent resource, not an insurance carrier, and the content here is educational, not financial or legal advice.
Ultimately, the question of what is medical payments coverage and do I need it depends on your individual circumstances. MedPay is a modest, practical add-on that can provide peace of mind and financial protection for you and your passengers. If the premium fits your budget and you value fast, fault-free medical payments, it is a coverage worth considering.