How Gap Insurance Works When You Owe More Than Car Value
Gap insurance covers the difference between your car's value and your loan balance after a total loss. Call (833)-214-7506 to compare coverage options.
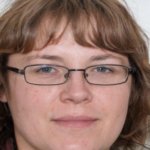
Imagine this: you are driving home from work when another driver runs a red light and totals your car. You breathe a sigh of relief because you have full coverage. Then the insurance adjuster calls with bad news. Your vehicle is worth $18,000, but your loan balance is $24,000. After your $500 deductible, your insurer pays $17,500, leaving you $6,500 in debt for a car you can no longer drive. This scenario plays out every day across the United States, and it is exactly why gap insurance exists. Understanding how gap insurance works when you owe more than your car value is essential for anyone financing or leasing a vehicle, especially in a market where depreciation can outpace loan payoffs faster than many drivers expect.
Gap insurance, short for guaranteed asset protection, is a type of coverage designed to bridge the difference between what your vehicle is worth at the time of a total loss and what you still owe on your loan or lease. Without it, that shortfall becomes an out-of-pocket expense that can derail your budget for months or even years. This guide explains the mechanics of gap coverage, who benefits most, how different types of gap protection compare, and how to decide whether it makes financial sense for your situation.
Why Actual Cash Value Payouts Leave You Underwater
To understand gap insurance, you first need to understand how standard auto insurance pays out claims. When your vehicle is declared a total loss, whether from a collision, theft, fire, flood, or other covered peril, your insurer pays the actual cash value (ACV) of the vehicle at the time of the loss. ACV is not what you paid for the car, and it is not what it would cost to replace it with a brand-new model. It is the fair market value of your vehicle in its current condition, factoring in age, mileage, wear and tear, and local market demand.
New vehicles depreciate rapidly. Most cars lose roughly 20 percent of their value in the first year, and another 10 to 15 percent each year after that. If you financed the full purchase price with a small down payment, your loan balance may remain higher than the vehicle's ACV for two to four years, depending on the loan term and interest rate. This negative equity position is often called being "upside down" or "underwater" on your loan.
The gap between ACV and loan balance becomes a problem when a total loss occurs. Your insurer pays only the ACV, minus your deductible. The remaining loan balance does not disappear. You are still contractually obligated to repay it, even though you no longer have the vehicle. Gap insurance steps in to cover that difference, up to policy limits, so you are not stuck paying for a car you cannot drive.
How Gap Insurance Pays Out After a Total Loss
When you file a total loss claim and have gap coverage, the process typically follows a specific sequence. Understanding these steps helps you anticipate what to expect and ensures you do not miss any deadlines or requirements.
- Your primary insurer settles the ACV claim. The insurance company handling your collision or comprehensive coverage determines the actual cash value of your vehicle and pays that amount, minus your deductible, toward your loan or lease balance.
- You file a gap claim. Once the primary settlement is finalized, you notify your gap provider (which may be your insurer, your lender, or a dealer-arranged program) and submit the required documentation, including the settlement letter, loan payoff statement, and proof of loss.
- The gap provider calculates the shortfall. The gap coverage pays the difference between the primary settlement and your remaining loan or lease balance, subject to any caps or exclusions in the policy.
- The loan is paid off. The gap payment goes directly to your lender to satisfy the remaining balance. In most cases, you owe nothing further on the vehicle.
It is important to note that gap insurance does not cover your deductible, any past-due payments, late fees, or penalties that may have accrued on your loan. It also does not cover negative equity rolled over from a previous vehicle loan unless the policy specifically includes that provision. Some gap policies cap the payout at a percentage of the vehicle's original value or a fixed dollar amount, so reading the fine print is essential.
If you are comparing coverage types and wondering how gap fits alongside your existing policy, our guide on gap insurance versus full coverage explains the distinctions in detail and helps you determine whether you need both.
Who Should Consider Gap Insurance
Gap insurance is not necessary for every driver, but it provides meaningful protection for certain financing situations. The following groups should evaluate gap coverage carefully:
- New car buyers with small down payments: If you financed most of the purchase price and put little or nothing down, you are likely upside down on your loan from day one. Gap coverage protects you during the period when depreciation outpaces your payoff.
- Lessees: Lease agreements often require gap coverage, and lease-specific gap policies may cover not only the balance but also early termination fees and other lease-end charges.
- Drivers with long loan terms: Loans of 60, 72, or 84 months extend the period during which you owe more than the car is worth. The longer the term, the more valuable gap coverage becomes.
- Buyers of vehicles with rapid depreciation: Certain makes and models lose value faster than average. Luxury vehicles, electric vehicles with evolving technology, and some domestic models may depreciate steeply, increasing shortfall risk.
- Anyone who rolled negative equity into a new loan: If you traded in an underwater vehicle and financed the shortfall into your new loan, your balance starts higher than the vehicle's value, making gap coverage especially relevant.
Conversely, if you made a substantial down payment, have a short loan term, or drive a vehicle that holds its value well, you may never face a significant shortfall. In those cases, the cost of gap insurance may outweigh the benefit, and self-insuring by setting aside the equivalent premium may be a reasonable alternative.
Dealer Gap, Lender Gap, and Insurer-Provided Loan/Lease Coverage
Gap protection comes in several forms, and the differences matter for cost, convenience, and consumer protections. Understanding these distinctions helps you avoid overpaying or duplicating coverage.
Dealer-Arranged Gap Insurance
Auto dealers frequently offer gap insurance at the point of sale, often bundling it into your financing. While convenient, dealer-arranged gap tends to be the most expensive option. The coverage may also include markups that are not disclosed clearly. If you choose dealer gap, review the contract carefully and compare the price against alternatives before signing.
Lender-Provided Gap Coverage
Some lenders offer gap protection as an add-on to your auto loan. Lender gap is typically less expensive than dealer gap and may be required for certain lease agreements. However, coverage terms vary widely, and some lender programs have strict claim requirements or caps on payouts. Ask for the policy documents and read the exclusions before agreeing.
Insurer-Provided Loan/Lease Coverage
Many auto insurance companies offer loan/lease coverage as an optional endorsement on your existing policy. This option is often the most cost-effective, especially if you already have comprehensive and collision coverage with the same insurer. Insurer-provided gap coverage is regulated like other insurance products, which may offer stronger consumer protections. It also simplifies the claims process because the same company handles both the ACV payout and the gap payment.
When evaluating these options, consider not only the premium but also the payout limits, exclusions, and the claims process. A lower-priced policy with a restrictive cap may provide less real protection than a slightly more expensive policy with generous terms.
Cost Versus Benefit: When Gap Insurance Makes Sense
Gap insurance typically costs between $20 and $60 per year when added to an existing auto policy, though dealer-arranged gap can cost several hundred dollars as a one-time fee. For many drivers, the annual cost is modest compared to the potential shortfall, which can easily reach $5,000 or more in the first two years of a loan.
To decide whether gap coverage is worth it, consider the following framework:
- Estimate your shortfall risk. Compare your current loan balance to your vehicle's estimated ACV. If the difference is small and shrinking quickly, gap coverage may not be necessary. If the difference is large or growing, gap coverage provides meaningful protection.
- Calculate the cost over your ownership period. Multiply the annual gap premium by the number of years you expect to be upside down. Compare that total to the potential shortfall you would face after a total loss.
- Consider your risk tolerance and emergency savings. If you have substantial savings and could comfortably absorb a $5,000 shortfall, self-insuring may be reasonable. If a shortfall would strain your finances, gap coverage offers peace of mind.
- Review your lease or loan requirements. Some leases mandate gap coverage. If yours does, you need to obtain it regardless of cost, but you can still shop for the most competitive option.
For drivers who want to reduce their loan balance faster and eliminate the need for gap coverage sooner, exploring car loan refinancing options may be worthwhile. Refinancing to a lower interest rate or shorter term can help you build equity more quickly and reduce the period during which you are upside down.
Common Misconceptions About Gap Insurance
Several myths surround gap coverage, and clearing them up helps consumers make better decisions. One common misconception is that gap insurance covers mechanical breakdowns or routine maintenance. It does not. Gap coverage applies only after a total loss, and only to the difference between the ACV settlement and the loan or lease balance.
Another myth is that gap insurance covers negative equity from a previous vehicle. In most cases, it does not. If you rolled $4,000 of negative equity from an old loan into a new one, standard gap policies will not cover that portion of the balance unless the policy explicitly includes it. Some lenders offer "negative equity coverage" as a separate product, but it is not the same as standard gap insurance.
A third misconception is that gap insurance is always required. It is not required by law in any state, though lenders and lessors may require it as a condition of financing. If you are not required to carry it, you can choose whether the protection is worth the cost for your situation.
Finally, some drivers believe gap insurance covers their deductible. It typically does not. You remain responsible for your deductible under your primary collision or comprehensive coverage, and gap insurance pays only the difference between the ACV settlement (after deductible) and the loan balance.
Steps to Take If You Are Upside Down on Your Auto Loan
If you suspect you owe more than your car is worth, taking proactive steps can protect your finances. Start by determining your actual position: look up your loan payoff amount and compare it to your vehicle's current market value using a reputable pricing guide or online valuation tool. If the gap is significant, consider the following actions:
- Evaluate gap coverage options: Compare quotes from your insurer, lender, and dealer to find the most cost-effective protection.
- Increase your loan payments: Paying extra toward principal each month reduces your balance faster and shortens the period during which you are upside down.
- Avoid rolling negative equity into future loans: If possible, pay off your current loan before trading in the vehicle, or choose a less expensive replacement that requires less financing.
- Refinance if rates have dropped: A lower interest rate can accelerate equity building and reduce your shortfall risk over time.
- Review your insurance coverage annually: As your loan balance declines, reassess whether gap coverage still provides value or whether you can safely drop it.
Being upside down on a car loan is common, but it is not permanent. With deliberate financial management and the right coverage, you can navigate the risk and protect yourself against the worst-case scenario of a total loss.
Gap insurance is a specialized tool that addresses a specific problem: the difference between what you owe and what your car is worth after a total loss. For drivers with small down payments, long loan terms, or leases, it can mean the difference between a manageable claim and a financial setback. By understanding how gap coverage works, comparing your options carefully, and reassessing your needs as your loan balance declines, you can make an informed decision that fits your budget and your risk tolerance. If you are unsure whether gap coverage is right for you, speaking with a licensed insurance agent can help clarify your options and ensure you have the protection you need.