Named Insured Driver vs Permissive Use: Key Differences
Understand name an insured driver versus permissive use and how they differ, then call (833)-214-7506 to confirm every household driver is properly covered.
By Isobel Crane
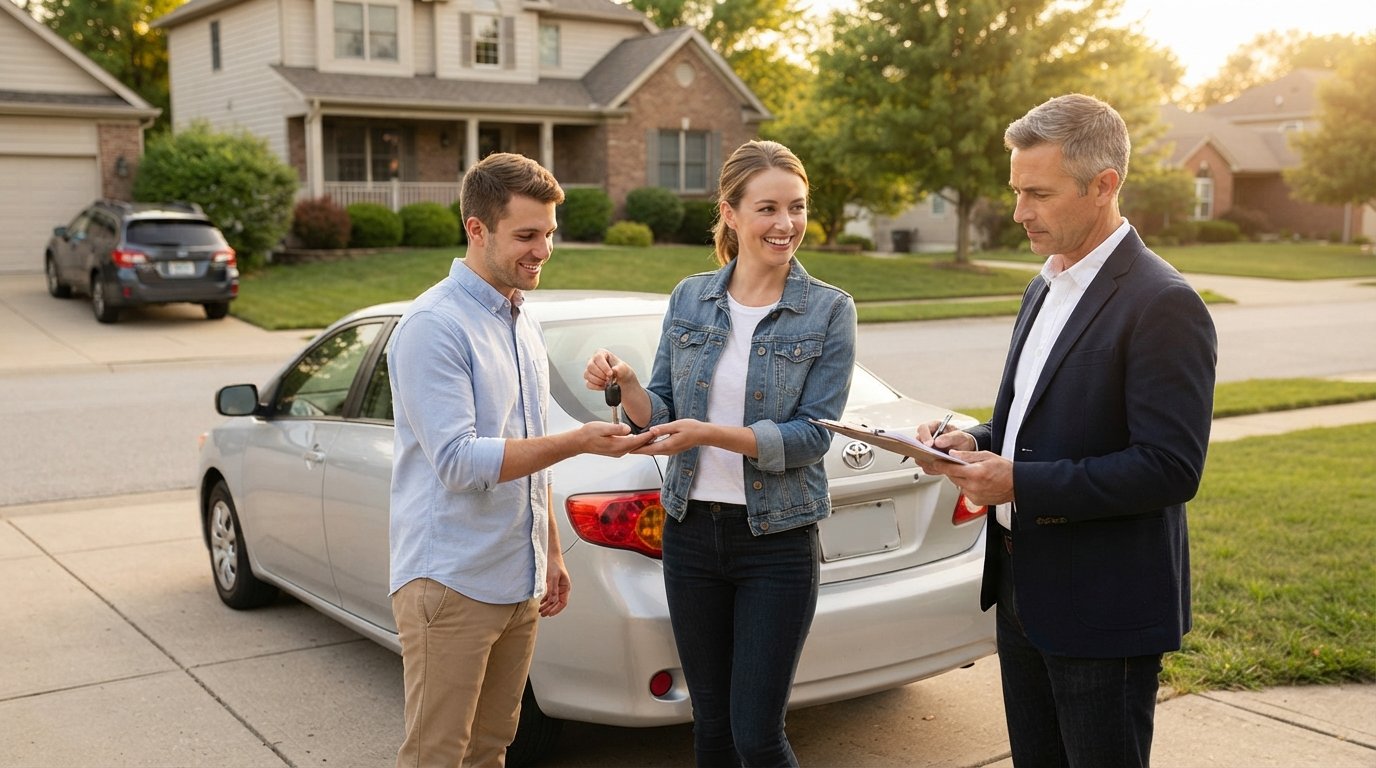
A friend asks to borrow your car for the afternoon. Your cousin needs wheels while hers is in the shop. A coworker offers to drive on a long road trip. In each case, you probably assume your auto policy will handle any mishap, but that assumption deserves closer scrutiny. The distinction between a named insured driver and a permissive user shapes who receives coverage, whose rate reflects the risk, and who absorbs the consequences when something goes wrong. Understanding this gap protects both your wallet and your relationships.
This guide walks through the mechanics of permissive use, the way household members fall outside that protection, the dangers of leaving regular drivers off your policy, and the situations where a named operator or non-owner policy makes more sense. Along the way, you will see how small documentation choices can prevent large claim disputes.
What It Means to Name an Insured Driver
A named insured driver is someone explicitly listed on the declarations page of an auto policy. That person is granted coverage under the contract, and in most cases the named insured also holds the legal right to cancel or modify the policy. The first name on the policy is typically the primary named insured, while additional named insureds are added through an endorsement or a simple listing during underwriting.
Naming a driver is not a formality. Insurers price risk based on who operates the vehicle, where it is garaged, and how often it is driven. When a driver appears on the policy, the carrier has evaluated that person's motor vehicle record, claims history, and driving experience. A named insured driver can file a claim directly, receive communications about the policy, and in many cases accrue the benefits of a continuous insurance history.
Permissive use, by contrast, is an automatic extension of coverage that applies when you lend your car to someone who is not on the policy. The policy follows the vehicle in most circumstances, which means a one-time borrower can be shielded under your liability, collision, and comprehensive coverages. The borrower does not become a named insured, does not receive policy documents, and does not build an insurance record from the transaction.
The two concepts overlap in daily life, but they serve different functions. Naming a driver is a deliberate underwriting decision. Permissive use is a courtesy provision built into most personal auto contracts. Confusing the two leads to the most common coverage gaps drivers discover only after a crash.
How Permissive Use Works in Practice
Permissive use generally means you gave someone explicit or implied permission to operate your vehicle. Letting a neighbor drive to the store, allowing a valet to park your car, or handing the keys to a friend for a weekend trip all fall within the typical definition. If the borrower causes an accident, your policy usually responds as though you were driving, subject to the same limits and deductibles.
Several conditions must be satisfied for permissive use to apply. The borrower must have reasonable belief that permission existed. The vehicle must be used in a manner consistent with the permission granted. The borrower must not be excluded by name or by a policy provision. And in most states, the borrower's own insurance, if any, may share or take priority for certain coverages, depending on the policy language and state rules.
The scope of permissive use narrows considerably when the borrower lives in your household. Standard personal auto policies contain a household member exclusion that treats family members and residents of the same address differently from occasional borrowers. A roommate, a spouse, a child home from college, or an adult relative living in your home is generally not considered a permissive user for liability purposes unless listed on the policy. Insurers reason that household members have regular access to the vehicle and should be rated accordingly.
This is why adding a newly licensed teenager or a partner who moves in with you matters. The carrier needs to know who regularly operates the car so the premium reflects the actual exposure. Failing to disclose a household driver can lead to a denied claim, a midterm cancellation, or a fraud investigation.
Household Members versus Non-Household Borrowers
The household versus non-household divide is the single most important factor in determining whether permissive use applies. Occasional borrowers who live elsewhere usually receive coverage under your policy when they drive your car with permission. Household members, however, are typically expected to be named drivers, and policies often exclude them from permissive use altogether.
Consider a few common scenarios to see how the rule plays out:
- A friend from out of town borrows your car for a day: likely covered as a permissive user under your policy.
- Your adult child moves back home and drives your car regularly: generally must be added to the policy to receive coverage.
- A neighbor borrows your truck to move furniture: usually covered as a permissive user, assuming no exclusion applies.
- Your spouse drives your car but is not listed on the policy: often excluded because spouses are treated as household members and expected to be rated.
- A coworker drives your car on a business errand: may be covered, but business use exclusions could apply if the vehicle is used commercially.
The pattern is clear. Distance from your household preserves permissive use. Proximity to your household undermines it. Insurers want every regular operator rated on the policy so the premium matches the risk. A borrower who lives under your roof has regular access and therefore belongs on the declarations page.
Some policies use a broader definition of household member that includes anyone who resides in your home, even temporarily. Others rely on a specific resident relative definition. The exact language matters, and reading the definitions section of your policy is the fastest way to understand where the line falls. If a household member is not listed and is not covered as a permissive user, the financial consequences of an accident can fall directly on your family.
Why Undisclosed Regular Drivers Create Real Risk
Leaving a regular driver off the policy is sometimes an honest oversight and sometimes a deliberate attempt to keep premiums low. Either way, the consequences can be severe. Insurers treat material misrepresentation about who drives the car as a rating issue, and many carriers reserve the right to deny coverage when a household driver is not disclosed.
The financial exposure extends beyond a denied claim. If your insurer discovers an undisclosed household driver after an accident, it may rescind the policy, cancel coverage going forward, or pursue a premium adjustment. In some states, intentionally hiding a high-risk driver can be classified as rate evasion, which carries civil penalties and, in extreme cases, criminal exposure. The short-term savings from omitting a driver rarely justify the long-term risk.
There is also a practical rating dimension. Adding a driver does not always raise your premium as much as people fear, especially if that driver has a clean record. Many carriers offer good student discounts, safe driver discounts, and multi-policy savings that offset the added cost. A licensed agent can run the numbers and show you the actual impact before you commit. If you are unsure how a specific driver would affect your rate, gathering a few quotes through an independent comparison resource is a low-effort way to see the math.
Claims disputes are another hidden cost. When an insurer investigates a claim and finds an undisclosed regular operator, the process can drag on for weeks or months. In the meantime, you may be without a vehicle, facing medical bills, or dealing with a lawsuit. Even if coverage is ultimately honored, the delay and stress are avoidable. Transparency at the point of application is always the cleaner path.
When a Named Operator or Non-Owner Policy Makes Sense
Permissive use is not the right tool for every situation. Some drivers need their own coverage even though they do not own a vehicle. A named operator policy, sometimes called a named non-owner policy, covers a specific person for liability and sometimes medical payments while driving vehicles they do not own. This is a common solution for people who borrow cars frequently, drive rental vehicles, or use car-sharing services.
A non-owner policy is particularly useful in a few scenarios:
- You live in a city and rely on rental cars, car shares, or borrowed vehicles rather than owning a car.
- You are a college student who drives home occasionally but does not keep a vehicle at school.
- You are between vehicles and want to maintain continuous insurance history to avoid rate penalties later.
- You regularly borrow a family member's car and want your own liability protection in case of an accident.
- You want higher limits than the vehicle owner's policy provides.
Named operator policies do not cover physical damage to the borrowed vehicle, so they are not a substitute for the owner's collision and comprehensive coverage. They also do not cover vehicles available for your regular use, which is an important limitation. Still, for drivers who want their own liability shield without owning a car, a non-owner policy closes a gap that permissive use leaves open.
For vehicle owners, adding a named driver to an existing policy is usually simpler than relying on permissive use, especially when the driver lives in the household. The cost is transparent, the coverage is clear, and the claim process avoids the ambiguity that comes with undeclared operators. If you are exploring options for a household driver, comparing quotes from multiple carriers is the most reliable way to find a fair rate. Resources such as car loan refinancing guidance can also help you understand how vehicle financing and insurance requirements interact, especially if you are still paying off the car.
Steps to Get the Driver Classification Right
Getting the named insured versus permissive use question right starts with a clear inventory of who drives your car. Take a few minutes to list every person who operates the vehicle, how often they drive, and whether they live in your home. Then follow a simple process to align your policy with reality.
First, review your declarations page and confirm that every household driver appears. Second, call your insurer or agent to add any missing drivers and ask how the addition affects your premium. Third, ask specifically about the household member exclusion and how your carrier defines household member. Fourth, document any occasional borrowers who do not live with you, so you can describe the arrangement accurately if a claim arises. Fifth, revisit the policy whenever a life change occurs, such as a move, a marriage, a new roommate, or a child getting a license.
If you discover that a regular driver has been uninsured or undisclosed, address it promptly. Voluntary disclosure is almost always treated more favorably than discovery during a claim investigation. A licensed agent can walk you through the options, including adding the driver, excluding them formally, or restructuring the policy. For drivers with serious violations, the stakes are higher, and understanding the penalties for uninsured driver repeat offenses can help you appreciate why continuous, accurate coverage matters.
Common Misconceptions That Lead to Gaps
Many drivers believe that any licensed driver who borrows the car is automatically covered, full stop. That belief is close to true for occasional borrowers who live elsewhere, but it breaks down for household members, excluded drivers, and regular operators. Another common myth is that adding a driver always doubles the premium. In reality, the increase depends on the driver's record, the vehicle, and the discounts available. A clean-record driver may add surprisingly little to the total.
A third misconception is that permissive use covers business use. If a borrower uses your car for commercial purposes, such as delivering food or driving for a rideshare platform, the personal auto policy may exclude the loss. Business use typically requires a commercial auto policy or a rideshare endorsement. Drivers who lend their cars to gig workers should confirm coverage before handing over the keys.
Finally, some owners assume that the borrower's insurance always pays first. The reality is state-specific and policy-specific. In some situations, the vehicle owner's policy is primary, and the borrower's policy is excess. In others, the order reverses. The only reliable way to know is to read both policies and, when in doubt, ask a licensed agent to explain the coordination of benefits.
Permissive use and named insured status are not competing ideas so much as different layers of the same coverage system. Permissive use handles the occasional borrower who lives elsewhere. Naming a driver handles the regular operator, especially the household member, whose risk belongs on the policy. Keeping the two straight protects your claim, your rate, and your peace of mind.