RV Insurance for Motorhomes: How to Choose Coverage
Master RV insurance for motorhomes: how to choose coverage that protects your rig and budget. Call (833)-214-7506 for expert guidance.
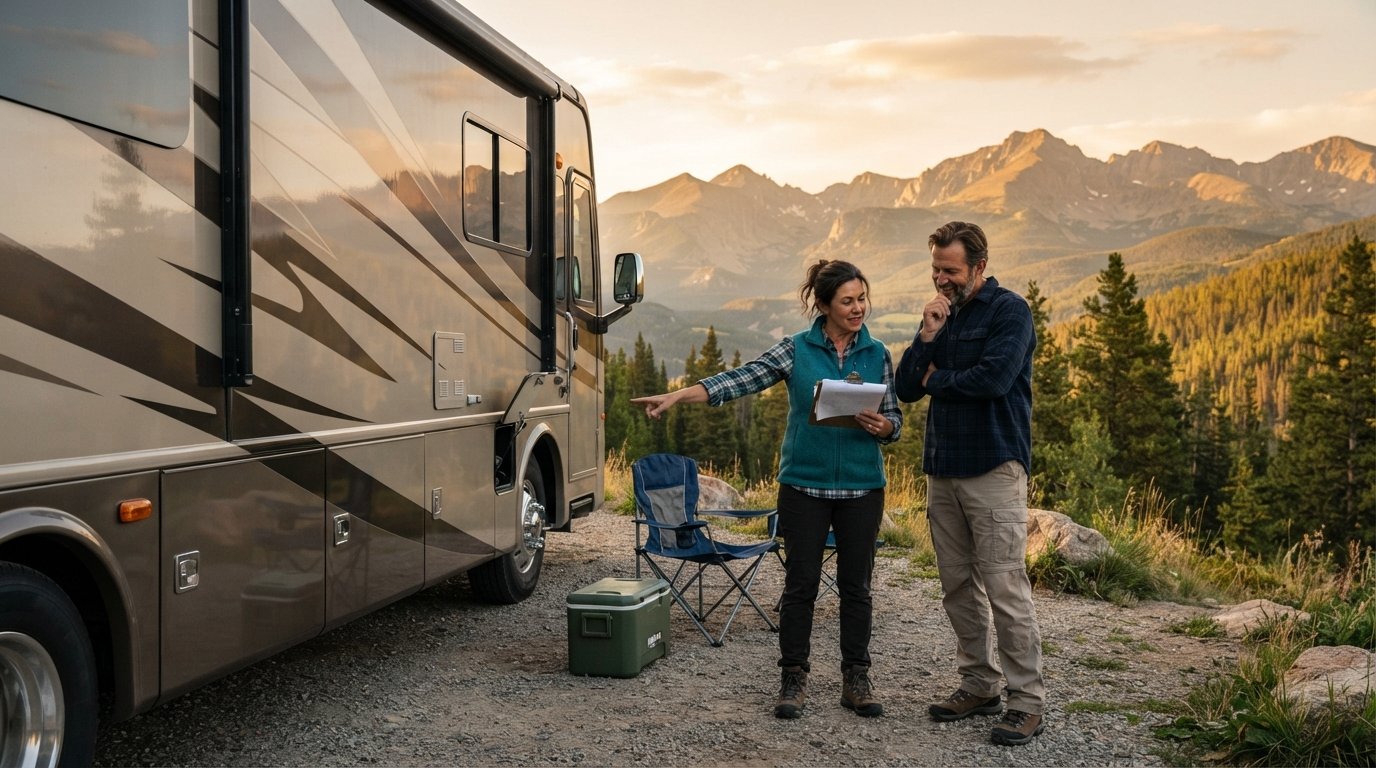
Your motorhome is more than a vehicle. It is a rolling home, a weekend escape pod, and often a significant financial investment. When you are barreling down a mountain pass or parked at a remote campsite, the last thing you want to worry about is whether your insurance policy actually covers the damage. Choosing the right RV insurance for motorhomes involves understanding that a standard auto policy rarely goes far enough. Motorhomes combine the risks of driving a large vehicle with the vulnerabilities of a house on wheels. This guide breaks down the coverage types, the unique risks you face, and the practical steps to secure a policy that protects your investment without overpaying.
Why a Standard Auto Policy Falls Short for Motorhomes
Many new motorhome owners assume their existing car insurance will automatically extend to their new rig. While some policies offer limited coverage for recreational vehicles, the protection is usually inadequate for a Class A, B, or C motorhome. A standard auto policy is designed for passenger cars, not for vehicles that contain plumbing, appliances, generators, and expensive electronics. If you rely solely on a standard policy, you may find yourself underinsured when a pipe bursts and ruins the interior, or when your awning is torn off by a sudden gust of wind.
Specialized RV insurance for motorhomes bridges this gap. It combines the liability and collision protection of auto insurance with the personal property and liability coverage found in a homeowners policy. This hybrid approach ensures that both the driving and the living aspects of your motorhome are protected. Without it, you risk paying out of pocket for repairs that could cost tens of thousands of dollars.
The Core Coverage Types You Need to Evaluate
When you start comparing quotes, you will encounter a mix of familiar auto terms and new RV-specific options. Understanding these components is the first step in how to choose coverage that matches your travel style.
Liability Coverage is the foundation. It pays for bodily injury and property damage you cause to others in an accident. Motorhomes are heavy and can cause significant damage, so higher liability limits are often wise. Collision Coverage handles damage to your own motorhome if you hit another vehicle or object, regardless of fault. Comprehensive Coverage protects against non-collision events like theft, fire, vandalism, or falling trees. For a motorhome, comprehensive is critical because these vehicles are often parked in remote areas or storage lots where theft and weather damage are real risks.
Beyond the basics, you need to look at Full-Timer Coverage. If you live in your motorhome year-round, your needs are different from a weekend camper. Full-timer coverage acts more like a homeowners policy, providing personal liability protection and coverage for your personal belongings both inside and outside the vehicle. It may also include loss of use coverage, which pays for a hotel or rental if your motorhome is uninhabitable due to a covered claim. If you are a part-timer, you may not need this, but you should still consider Personal Effects Coverage to protect items like laptops, camping gear, and clothing that are not permanently attached to the RV.
Finally, consider specialized add-ons such as Awning Coverage, which protects against damage to your retractable awning, and Roadside Assistance, which is essential for large vehicles that cannot be towed by a standard tow truck. Some policies include total loss replacement, which pays for a new model if your motorhome is totaled within the first few years.
Unique Risks That Drive Motorhome Insurance Decisions
Motorhomes face a distinct set of risks that set them apart from cars and houses. One major factor is personal belongings. Your motorhome likely contains thousands of dollars in gear, from kitchenware to electronics to outdoor furniture. Standard auto policies do not cover these items. You need to check whether your policy includes personal effects coverage and what limits apply. If you carry expensive items like cameras or jewelry, you may need a rider or floater.
Another consideration is usage and storage. Where you store your motorhome when it is not in use affects your premium. A secure, locked facility may lower your rate compared to parking it on the street. Similarly, how often you use it matters. Full-timers who drive thousands of miles a year present a different risk profile than occasional campers. Insurance providers will ask about your annual mileage and travel plans.
Weather and environmental risks are also significant. Hail, wind, and flooding can damage a motorhome just as they can damage a house. Comprehensive coverage is your defense here, but you should review the deductible and ensure it is affordable. If you travel to areas prone to wildfires or hurricanes, you may need to discuss additional protections with your agent.
Factors That Influence Your RV Insurance Rates
Insurance companies use a variety of data points to calculate your premium. Understanding these factors can help you anticipate costs and find opportunities to save. The type of motorhome is a primary factor. Class A diesel pushers cost more to insure than a Class B camper van because of their size, replacement cost, and repair complexity. The age and condition of the vehicle also matter. Newer motorhomes may qualify for total loss replacement coverage, while older ones may have lower actual cash value settlements.
Your driving history and experience with large vehicles play a role. A clean record and prior RV experience can lead to lower rates. Some insurers offer discounts for completing an RV safety course. Location is another factor: urban areas with high theft rates or severe weather zones may have higher premiums. Finally, the coverage limits and deductibles you choose directly affect your rate. Higher deductibles usually mean lower premiums, but you need to ensure you can afford the out-of-pocket cost if you file a claim.
How to Choose Coverage: A Step-by-Step Framework
With so many variables, it helps to follow a structured approach. Here is a practical framework to guide your decision.
- Assess your usage. Are you a full-timer, part-timer, or occasional camper? This determines whether you need full-timer coverage, personal effects coverage, and loss of use protection.
- Determine your must-have coverages. Liability, collision, and comprehensive are essential for most motorhomes. Add specialized coverage like awning protection and roadside assistance based on your needs.
- Set realistic limits and deductibles. Balance your budget with the need for adequate protection. Higher liability limits are often worth the extra cost given the damage a motorhome can cause.
- Compare quotes from specialized agents. RV insurance is not one-size-fits-all. Work with agents who understand motorhomes and can explain the nuances of each policy.
After you have a clear picture of your needs, you can start gathering quotes. This is where a resource like NewAutoInsurance.com can streamline the process. The site connects you with licensed agents who can provide personalized quotes for RV insurance. You can also explore general savings strategies, such as how to bundle auto insurance with renters or homeowners policies, which may apply to your RV if you insure it alongside your other vehicles.
Tips for Saving on Motorhome Insurance
Insurance for motorhomes can be expensive, but there are legitimate ways to reduce your premium without sacrificing protection. Bundling is one of the most effective strategies. If you insure your motorhome with the same company that covers your cars or home, you may qualify for a multi-policy discount. Safe driver discounts are available if you have a clean driving record or complete an approved RV driving course. Some insurers offer discounts for storing your RV in a secure facility or for being a member of a recognized RV association.
Another tip is to review your deductible annually. If you can afford a higher deductible, you may lower your premium. However, be careful not to raise it so high that a claim would be financially devastating. You can also ask about low-mileage discounts if you use your motorhome infrequently. Finally, maintain a good credit score, as many insurers use credit-based insurance scores to determine rates. By taking these steps, you can keep your RV insurance affordable while maintaining solid coverage.
Working with Specialized Agents and Comparing Quotes
RV insurance is a niche product. Not every insurance agent understands the difference between full-timer coverage and personal effects coverage, or how to properly value a motorhome with custom modifications. That is why it is crucial to work with agents who specialize in recreational vehicles. A specialized agent can help you identify gaps in coverage, explain policy exclusions, and tailor a policy to your specific travel plans.
To get started, you can use NewAutoInsurance.com to connect with licensed agents who offer RV insurance quotes. The platform is designed to provide fast, tailored quotes without obligation. You can also visit the CarLoanRefinancing resource to explore options for financing your motorhome, which can sometimes be bundled with insurance considerations. When comparing quotes, make sure you are comparing apples to apples: check the liability limits, deductibles, and included coverages. Do not simply choose the lowest price; choose the policy that provides the best protection for your investment and your lifestyle.
Before you finalize any policy, read the fine print. Understand what is excluded, such as wear and tear, insect damage, or certain weather events. Ask about the claims process and whether the insurer has a dedicated RV claims team. A little research upfront can save you significant headaches later.
Your motorhome represents freedom and adventure. Protecting it with the right insurance ensures that a single accident or storm does not derail your plans. By understanding your coverage options, assessing your usage, and comparing quotes from specialized agents, you can choose a policy that offers peace of mind on every journey.