Motorcycle Insurance Coverage for Riders: How to Compare
Master motorcycle insurance coverage for riders, how to compare policies, and save. Call (833)-214-7506 for expert help.
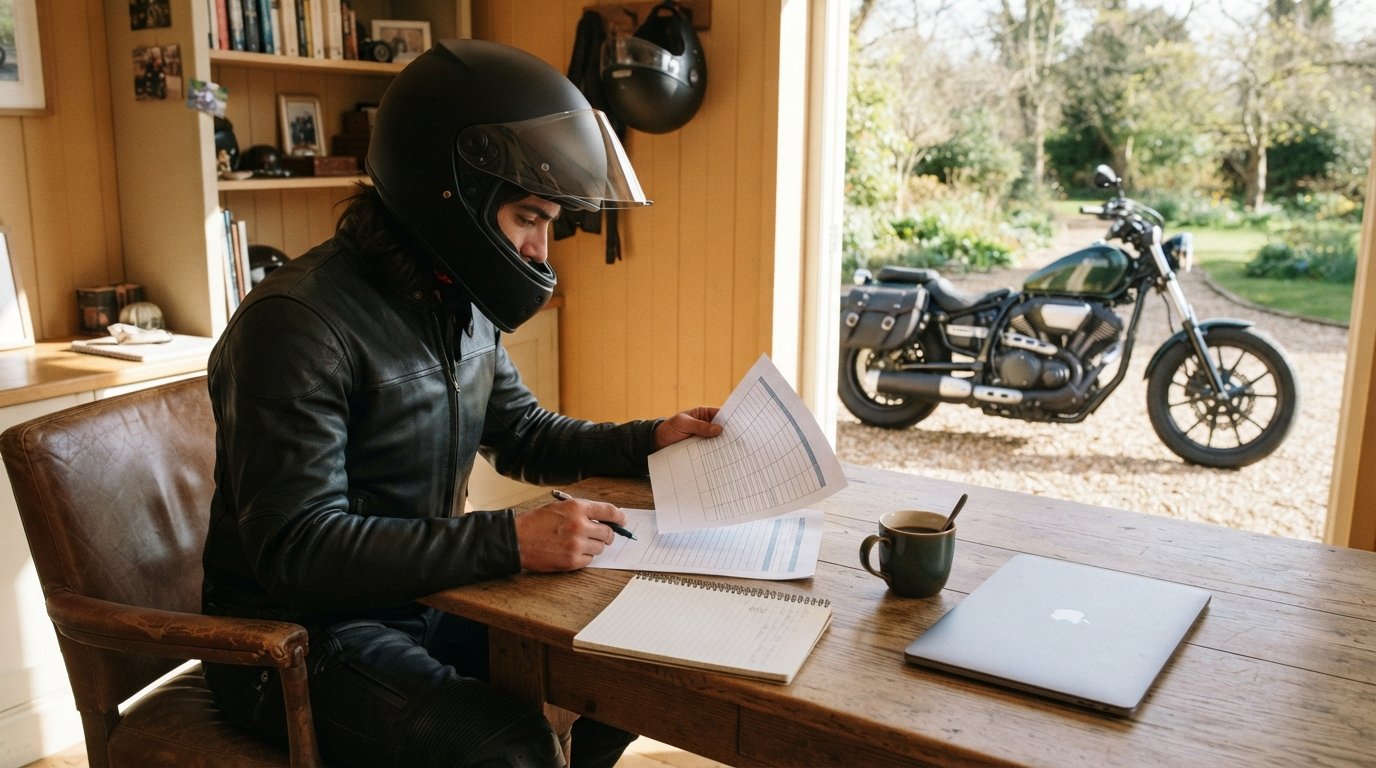
Your motorcycle is more than a machine; it is your escape, your commute, and often your pride and joy. But when it comes to protecting it, the process of comparing motorcycle insurance coverage can feel like navigating a maze of jargon and fine print. The stakes are high: riding a motorcycle exposes you to greater physical and financial risk than driving a car, so settling for the first policy you find could leave you underinsured and overpaying. The key to getting the right protection at the right price is understanding how to compare policies side by side, not just by the bottom line, but by the quality of coverage and the reliability of the insurer behind it. This guide will walk you through the essential components of a motorcycle policy, the factors that drive your rates, and a practical framework for comparing quotes so you can ride with confidence and financial security.
Decoding the Components of Motorcycle Insurance Coverage
Before you can compare policies, you need to know what you are comparing. Motorcycle insurance is not a single product; it is a bundle of different coverage types, each designed to protect you against a specific kind of financial loss. A policy that looks cheap might be stripped of critical protections, while a more expensive one might include coverage you do not actually need. Understanding the building blocks of a standard policy is the first step toward making an informed decision.
Most states require riders to carry a minimum level of liability coverage, but that is just the starting point. Liability coverage pays for damage you cause to others, but it does nothing for your own bike or your own medical bills. To fully protect yourself, you need to look beyond the state minimums and consider a broader suite of options. Here are the core components you will encounter when comparing motorcycle insurance coverage for riders:
- Bodily Injury Liability: Covers the cost of injuries you cause to others in an accident, including medical bills and legal fees if you are sued.
- Property Damage Liability: Pays for damage you cause to another person's property, such as a car or a fence.
- Collision Coverage: Reimburses you for damage to your own motorcycle if you hit another object or vehicle, regardless of who is at fault.
- Comprehensive Coverage: Protects your bike against non-collision incidents like theft, vandalism, fire, or natural disasters.
- Uninsured/Underinsured Motorist (UM/UIM) Coverage: Steps in when you are hit by a driver who has no insurance or insufficient coverage to pay for your injuries.
- Medical Payments (MedPay) or Personal Injury Protection (PIP): Covers medical expenses for you and your passenger, regardless of fault, often up to a specified limit.
Beyond these standard elements, many insurers offer specialized add-ons that are particularly valuable for riders. Accessory coverage, for example, protects your custom parts, safety gear, and riding apparel, which are often not covered under a standard policy. You may also find options for roadside assistance, trip interruption coverage, and even coverage for track days or organized events. When comparing quotes, check whether these add-ons are included or available, as they can significantly affect the value of a policy.
What Drives Your Motorcycle Insurance Rates?
Insurance premiums are not arbitrary. Insurers use a complex set of factors to assess the likelihood that you will file a claim and the potential cost of that claim. Understanding these factors gives you leverage when comparing quotes, as you can see why one policy might be more expensive than another and identify areas where you might be able to reduce your costs. The primary rating factors for motorcycle insurance include rider experience, the type of bike you ride, and where you live, but there are several other variables at play.
Rider experience is one of the most significant factors. New riders, or those with a history of accidents or traffic violations, are statistically more likely to file claims, so they typically pay higher premiums. Insurers often reward experienced riders, those with years of clean riding history, and those who have completed a motorcycle safety course with lower rates. Your age also plays a role; younger riders, particularly those under 25, often face higher premiums due to their perceived inexperience. The type of motorcycle you ride matters as well: sportbikes and high-performance models are more expensive to insure than cruisers or touring bikes because they are associated with higher speeds and more costly repairs.
Your location is another major factor. Urban areas with heavy traffic and higher rates of theft generally have higher premiums than rural areas. Even your credit score can influence your rate in many states, as insurers view credit history as a predictor of responsibility. The coverage limits and deductibles you choose will also directly impact your premium: higher limits cost more, while higher deductibles lower your premium but increase your out-of-pocket costs in the event of a claim. When you compare policies, make sure you are comparing quotes with identical coverage limits and deductibles; otherwise, you are not comparing apples to apples.
A Step-by-Step Framework for Comparing Motorcycle Insurance Quotes
Now that you understand what goes into a policy and what drives the price, you can approach the comparison process systematically. The goal is to find the best combination of coverage, price, and insurer reliability for your specific needs. Rushing this process or focusing solely on the lowest premium can be a costly mistake. Instead, follow a structured approach that ensures you are making a well-informed decision.
Start by determining your coverage needs. Consider your bike's value, your personal assets, your risk tolerance, and your state's minimum requirements. If you have a loan or lease on your motorcycle, the lender will likely require you to carry collision and comprehensive coverage. If you have significant assets to protect, you may want higher liability limits. Once you have a clear picture of what you need, you can begin gathering quotes. Here is a practical sequence to follow:
- Gather multiple quotes: Contact at least three to five different insurers or use an independent agent who can shop around for you. This is the only way to know if you are getting a competitive rate.
- Compare identical coverage levels: Ensure each quote reflects the same liability limits, deductibles, and add-ons. A lower premium often means lower coverage, so verify the details.
- Research the insurer's reputation: Check financial strength ratings and customer satisfaction scores. A cheap policy is worthless if the company is difficult to reach or slow to pay claims.
- Ask about discounts: Inquire about discounts for safety courses, bundling, loyalty, and safe riding records. These can vary significantly between insurers.
- Review the fine print: Look for exclusions, such as whether custom parts are covered, whether the policy covers riding gear, and how claims are handled.
After you have collected and compared quotes, do not be afraid to negotiate. Insurers want your business, and sometimes simply asking if there is room to lower the premium can yield results. You can also adjust your deductible or coverage limits to find a balance between affordability and protection. Remember that the cheapest policy is not always the best value; the right policy is the one that provides adequate protection at a price you can comfortably afford.
Strategies for Saving on Motorcycle Insurance Without Sacrificing Coverage
Finding affordable motorcycle insurance does not mean you have to settle for minimal coverage. There are several legitimate ways to reduce your premium while maintaining solid protection. The most effective strategy is to take advantage of discounts, which can vary widely from one insurer to another. When comparing quotes, always ask which discounts are available and whether you qualify. Some of the most common and valuable discounts include:
- Safety course discount: Completing a recognized motorcycle safety course, such as those offered by the Motorcycle Safety Foundation, can earn you a discount with many insurers.
- Bundling discount: If you also have auto, home, or renters insurance, bundling your motorcycle policy with the same insurer can lead to significant savings. For a deeper look at how bundling works across different policy types, you can read our guide on renters and homeowners auto insurance coverage fit.
- Loyalty and renewal discounts: Staying with the same insurer for multiple years or insuring multiple vehicles can often lower your rate.
- Safety features discount: Installing anti-theft devices, alarms, or GPS trackers can reduce your premium, especially for comprehensive coverage.
- Payment discounts: Paying your premium in full rather than in monthly installments can save you money on administrative fees.
Another effective strategy is to adjust your deductible. Choosing a higher deductible, the amount you pay out of pocket before insurance kicks in, can lower your premium. However, you should only do this if you have enough savings to cover the higher deductible in an emergency. Similarly, you can review your coverage limits annually to ensure they still align with your needs. If your bike has aged and its value has decreased, you might consider dropping collision and comprehensive coverage, but only if you can afford to replace it yourself. For those who finance their motorcycle, understanding your auto loan options can also influence your overall financial picture; resources like CarLoanRefinancing.com offer educational guides and calculators to help you potentially lower monthly payments or adjust loan terms, freeing up funds for insurance.
The Value of Comparing Quotes from Multiple Agents
The single most important action you can take to ensure you are getting the best motorcycle insurance coverage for your needs is to compare quotes from multiple sources. This cannot be overstated. Insurance premiums for the same rider and the same bike can vary by hundreds of dollars per year between different companies. The only way to know if you are getting a fair deal is to put in the effort to gather and compare quotes. Working with an independent insurance agent can streamline this process, as they have access to multiple insurers and can often find you the best combination of price and coverage.
When you compare quotes, look beyond the premium. Consider the insurer's customer service reputation, claims processing speed, and financial stability. A company that is difficult to reach or has a history of denying legitimate claims is not worth the savings. Also, ask about the claims process: can you choose your own repair shop, or does the insurer require you to use a network provider? These details can make a big difference in your experience if you ever need to file a claim. By taking a systematic approach to comparing motorcycle insurance coverage, you can ride knowing that you are protected by a policy that fits your needs and your budget.