Massachusetts Car Insurance Laws and Coverage Options
Understand Massachusetts car insurance laws and coverage options, from no-fault rules to optional add-ons. Call (833)-214-7506 to compare tailored quotes today.
By Sebastian Rowe Sebastian Rowe
Massachusetts drivers face a car insurance system unlike any other in the country. The state combines strict minimum coverage requirements with a no-fault framework, meaning your own policy pays for your medical bills after an accident regardless of who caused it. That structure sounds simple, but the details matter enormously when you are shopping for a policy, filing a claim, or trying to keep premiums under control. Understanding how Massachusetts car insurance laws and coverage options actually work can save you thousands of dollars over time and prevent nasty surprises when you need your policy most.
Whether you are new to the state, buying your first vehicle, or simply reviewing your renewal, this guide breaks down the legal requirements, the optional coverages worth considering, the factors that drive rates, and a practical approach to comparing quotes. The goal is straightforward: help you make an informed decision without drowning in jargon.
Massachusetts Minimum Coverage Requirements and No-Fault Rules
Massachusetts law requires every registered vehicle to carry a specific set of minimum coverages. These are not suggestions; driving without them can lead to fines, license suspension, and personal financial liability. The core mandatory coverages include Bodily Injury to Others, Personal Injury Protection (PIP), Bodily Injury Caused by an Uninsured Auto, and Property Damage. Each serves a distinct purpose, and together they form the legal foundation of your policy.
The minimum limits are relatively modest compared to some states. Bodily Injury to Others is required at $20,000 per person and $40,000 per accident. Property Damage is set at $5,000. PIP is required at $8,000, which covers medical expenses, lost wages, and other costs for you and your passengers regardless of fault. Uninsured motorist coverage must match your bodily injury limits. These minimums satisfy the law, but they rarely reflect the true cost of a serious accident in a high-cost state like Massachusetts.
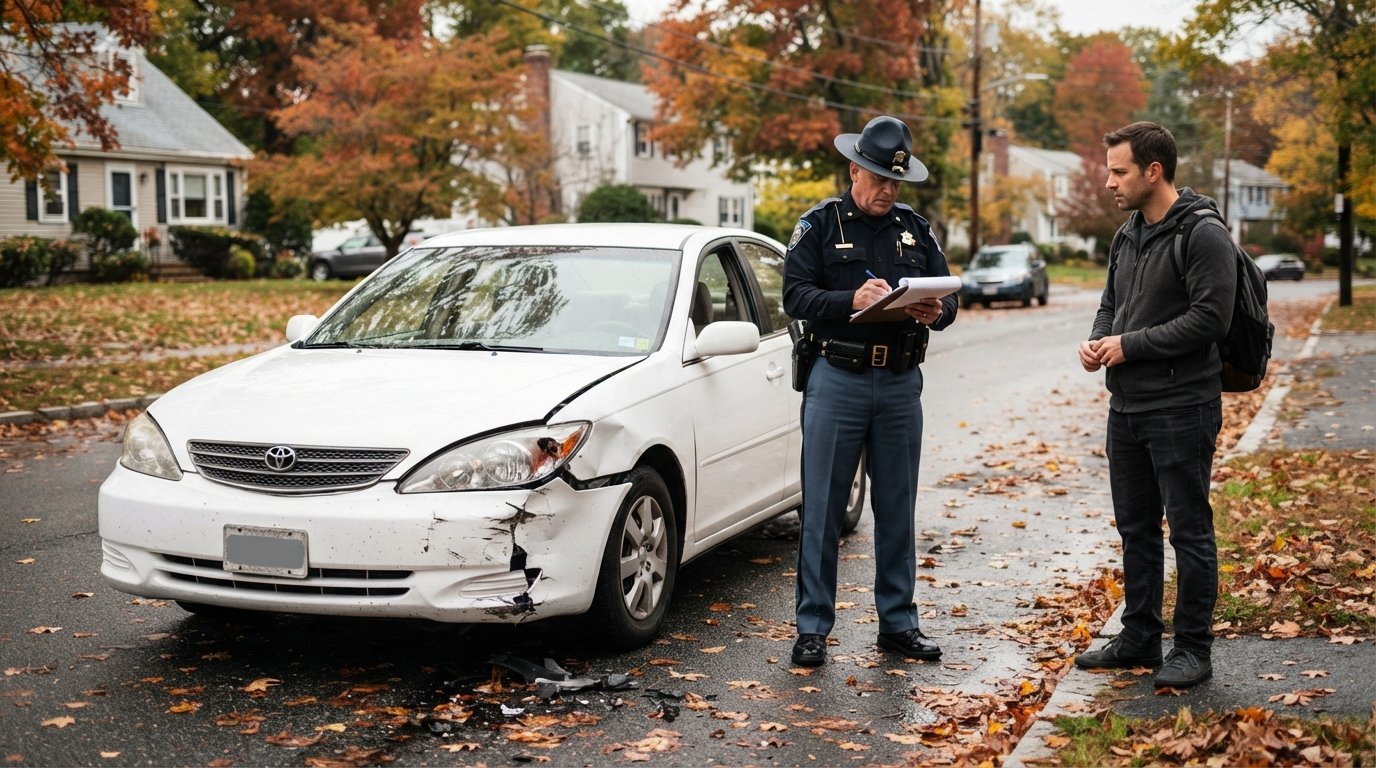
The no-fault system is the defining feature of Massachusetts car insurance. After an accident, your own PIP coverage pays for your medical bills and related expenses up to the policy limit, no matter who caused the crash. This design speeds up payments and reduces litigation for minor injuries. However, no-fault does not eliminate fault entirely. You can still be held responsible for property damage and for injuries that exceed certain thresholds, and your premiums can rise if you are found at fault. Understanding this balance helps you see why higher PIP limits and adequate liability coverage are often worth the extra cost.
Massachusetts also imposes strict penalties for driving uninsured. These include license and registration suspension, reinstatement fees, and mandatory SR-22 filings in some cases. The state verifies insurance electronically, so gaps in coverage are detected quickly. Maintaining continuous coverage is not just legal compliance; it is also a practical way to avoid the high cost of reinstating your driving privileges.
Optional Coverages That Fill the Gaps
Beyond the mandatory minimums, Massachusetts offers a range of optional coverages that can significantly improve your financial protection. These options let you tailor your policy to your risk tolerance, your vehicle's value, and your budget. Choosing wisely among them is where the real value of understanding Massachusetts car insurance laws and coverage options becomes clear.
Collision coverage pays to repair or replace your vehicle after a collision with another object or vehicle, regardless of fault. If you drive a newer car or lease a vehicle, collision is often essential. Comprehensive coverage handles non-collision events such as theft, vandalism, fire, or weather damage. Many lenders require both collision and comprehensive until the loan is paid off. For older vehicles with low market value, you may reasonably decide to skip these coverages and bank the savings, but weigh that against the cost of replacing the car out of pocket.
Additional optional coverages worth reviewing include:
- Higher PIP limits above the $8,000 minimum, which can be valuable if you have a health insurance deductible or lack generous medical benefits.
- Increased bodily injury and property damage liability limits to protect your assets in a serious at-fault accident.
- Uninsured and underinsured motorist coverage above the minimum, given that a meaningful share of Massachusetts drivers carry only the legal minimum.
- Medical payments coverage, which can supplement PIP and health insurance for copays and deductibles.
- Roadside assistance and rental reimbursement, which are inexpensive add-ons that improve convenience.
Each optional coverage adds to your premium, so prioritize based on your circumstances. A driver with significant savings and a newer car should lean toward higher liability and collision coverage. A driver with an older paid-off vehicle and robust health insurance might choose a leaner policy with a higher deductible. The key is to make these decisions deliberately rather than accepting whatever a quote defaults to.
When you are ready to explore specific add-ons and compare how they affect your rate, our guide on the best affordable car insurance for new vehicles explains how to balance coverage and cost for newer models. That context is especially useful if you are insuring a recently purchased car in Massachusetts.
Average Premiums and the Factors That Drive Rates
Massachusetts car insurance premiums vary widely based on driving record, location, vehicle, and coverage choices. Statewide averages give a rough benchmark, but your own quote may land far above or below that figure. Urban areas like Boston typically command higher rates due to traffic density and theft risk, while rural western Massachusetts communities often see lower premiums. Even within a single city, your ZIP code can shift your rate meaningfully.
Several factors carry substantial weight in Massachusetts rate calculations. Your driving history is paramount; at-fault accidents, speeding tickets, and DUI convictions can raise premiums sharply and may trigger SR-22 requirements. Years of driving experience matter, with newer drivers facing higher rates. The vehicle itself plays a role through its safety ratings, repair costs, and theft susceptibility. Your credit history may also be used by some insurers in Massachusetts, subject to state rules. Finally, the coverages and deductibles you select directly determine your premium.
Massachusetts has specific rules that affect rates in ways drivers should understand. The state sets a framework for safe driver insurance plan credits, which reward clean driving records with discounts and penalize at-fault incidents. You can also earn discounts for bundling auto and home or renters policies, paying in full, insuring multiple vehicles, and completing defensive driving courses. These discounts can add up to meaningful savings, but they are not automatic. You often need to ask or verify that they are applied.
If you are financing or leasing your vehicle, your lender may require certain coverages and may also influence your overall budget. Drivers who want to reduce their monthly obligations sometimes explore car loan refinancing to lower their payment and free up room for adequate insurance. That is a separate decision from buying coverage, but it is worth considering when you are reviewing your total vehicle costs.
How to Compare Quotes and Choose the Right Coverage
Comparing Massachusetts car insurance quotes effectively requires more than lining up premium numbers. The cheapest quote may offer minimal limits or exclude coverages you need, leaving you exposed. Conversely, a higher premium may include valuable protections that cost far less than paying out of pocket after a serious accident. A disciplined comparison process helps you see the full picture.
Start by deciding your target coverage levels before you request quotes. Use the state minimums as a floor, then adjust upward based on your assets, your vehicle's value, and your risk tolerance. If you have significant savings or home equity, higher liability limits are usually wise. If you drive a newer car, collision and comprehensive are often worth including. Once you have a target policy structure, request quotes from multiple insurers using identical coverage details so the comparison is apples to apples.
A practical step-by-step approach looks like this:
- List your required coverages and desired limits, including any lender requirements.
- Gather your driving history, vehicle information, and current policy details.
- Request quotes from several insurers using the same coverage selections.
- Compare not just premiums but also deductibles, exclusions, and customer service reputation.
- Ask about every discount you might qualify for, then verify they appear on the final quote.
After you have quotes in hand, read the policy details carefully. Look at the deductible for collision and comprehensive, the PIP limit, and whether uninsured motorist coverage matches your bodily injury limits. Small differences in these terms can change your out-of-pocket costs dramatically. If a quote seems unusually low, check whether it omits a coverage you assumed was included. It is also smart to ask how claims are handled and whether the insurer offers local agents or only online service, since that affects your experience when you need help.
Finally, revisit your policy annually. Rates change, discounts evolve, and your circumstances shift. A policy that fit you two years ago may no longer be optimal. Reviewing your coverage at renewal, or after major life events like moving, buying a home, or adding a driver, keeps you aligned with Massachusetts car insurance laws and coverage options as they apply to your situation.
Massachusetts car insurance is not one-size-fits-all, but the framework is understandable once you break it down. The state requires a specific set of minimum coverages and operates under a no-fault system that pays your medical bills through PIP regardless of fault. Optional coverages like collision, comprehensive, and higher liability limits let you build protection around your actual risk. Rates depend heavily on your driving record, location, vehicle, and coverage choices, and discounts reward safe drivers and bundled policies. By setting your target coverage before you shop, comparing quotes on equal terms, and reviewing your policy regularly, you can secure solid protection without overpaying. The effort you put into understanding these rules pays off every time you drive.