Car Insurance New Hampshire: How to Find Low Cost Coverage
Find low cost car insurance in New Hampshire by comparing quotes and using discounts. Call (833)-214-7506 for expert guidance on coverage options.
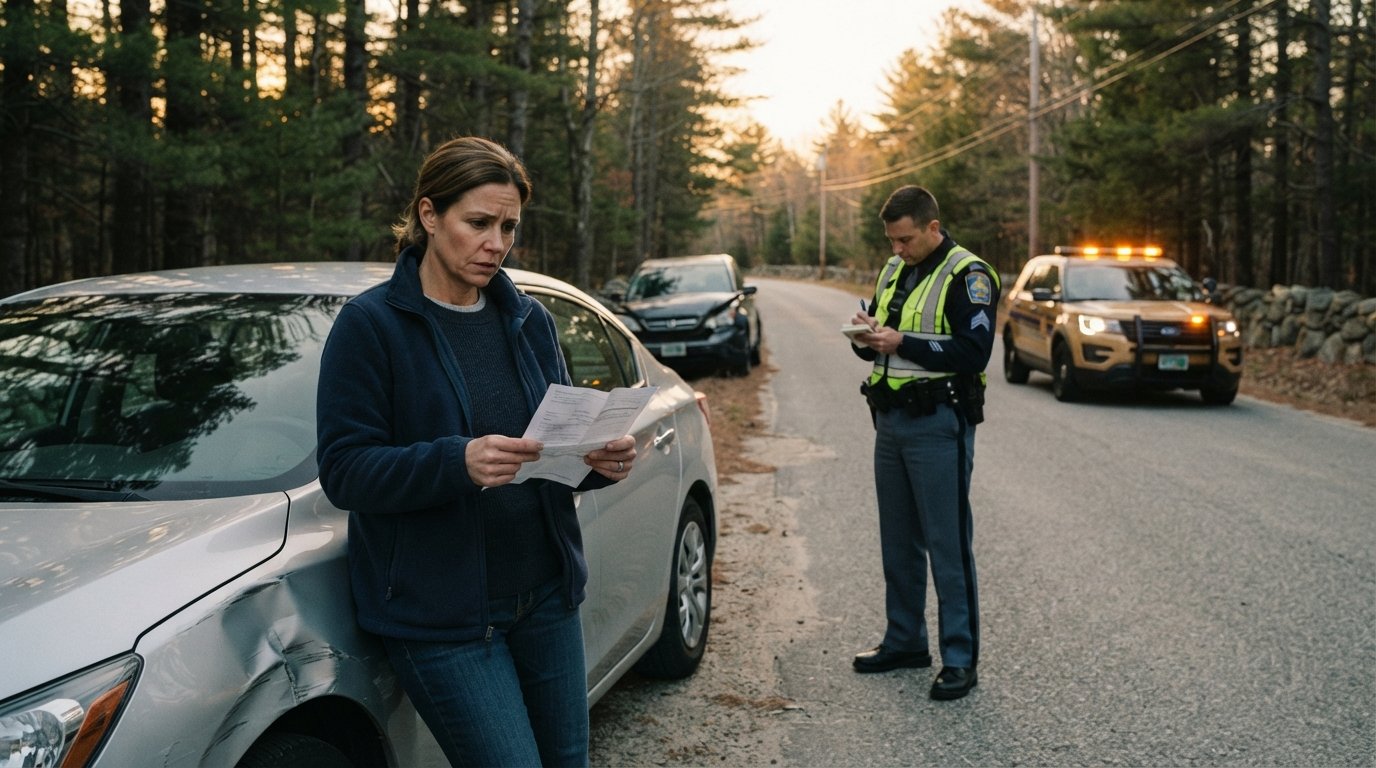
New Hampshire drivers enjoy a rare distinction: the state does not require you to carry auto insurance. But that freedom comes with a hidden risk. If you cause a crash, you are personally responsible for the damage, and if an uninsured driver hits you, you could be left paying your own medical bills. Finding low cost car insurance in New Hampshire is not about satisfying a legal mandate, it is about protecting your finances without overspending. This guide shows you how to navigate the Granite State's unique insurance landscape, identify the factors that drive your premium up or down, and locate the cheapest coverage that still keeps you safe.
New Hampshire's Optional Insurance System and Why Uninsured Motorist Coverage Matters
New Hampshire is the only state that does not require adults to carry auto insurance. Instead, the state relies on a financial responsibility law: if you are involved in an accident, you must be able to prove you can pay for the damages. Most drivers choose to buy coverage anyway, but the lack of a mandate means many people on the road have no insurance at all. According to the Insurance Research Council, New Hampshire has one of the highest rates of uninsured drivers in the country, often exceeding 10 percent of all motorists.
That reality makes uninsured motorist (UM) coverage one of the most important purchases you can make. UM coverage pays for your medical expenses and property damage when the at-fault driver has no insurance or insufficient coverage. It also typically includes underinsured motorist coverage, which kicks in when the other driver's policy limits are too low to cover your losses. Without UM, you could be stuck with thousands of dollars in bills through no fault of your own.
Even though insurance is optional, New Hampshire law requires you to purchase uninsured motorist coverage if you buy any auto insurance at all. The minimum UM limits are $25,000 per person and $50,000 per accident for bodily injury, plus $25,000 for property damage. You can purchase higher limits, and for most drivers, doing so is worth the extra few dollars per month. Medical payments coverage is also worth considering, especially if you have a high-deductible health plan.
Factors That Affect Your Car Insurance Rate in New Hampshire
Insurance companies in New Hampshire evaluate a long list of variables when setting your premium. Understanding these factors gives you leverage to improve your rate or at least avoid unnecessary surcharges. The most influential factors include your driving record, your credit history, and the vehicle you drive, but there are others that matter as well.
Your driving record is the single biggest factor for most drivers. A clean record with no accidents or moving violations in the past three to five years qualifies you for the lowest rates. One at-fault accident or a DUI can raise your premium by 40 percent or more, and multiple incidents may make you a high-risk driver that some carriers refuse to insure. New Hampshire does not use a point system for insurance, but carriers still review your motor vehicle record and assign their own risk scores.
Credit history is another major rating factor in New Hampshire. Unlike some states, New Hampshire allows insurers to use credit-based insurance scores to determine rates. A poor credit score can increase your premium significantly, sometimes by hundreds of dollars per year. If your credit is less than perfect, focus on improving it before you shop for new coverage, and ask each insurer whether they use credit scoring and how much weight it carries.
The vehicle you drive also matters. New cars cost more to insure because they are worth more and cost more to repair. Sports cars, luxury vehicles, and cars with high theft rates carry higher premiums. On the other hand, vehicles with strong safety ratings and anti-theft devices often qualify for discounts. If you are shopping for a new vehicle, check the insurance cost before you buy. Our guide on affordable car insurance for new vehicles explains how to keep premiums low on a newer model.
Other factors include your age (teen drivers pay the most), your gender (statistically, young males pay more), your marital status (married drivers often pay less), where you live in New Hampshire, and how much you drive. Urban areas like Manchester and Nashua tend to have higher rates than rural towns due to more traffic and theft. If you have a long commute, you may pay more than someone who works from home.
Common Discounts That Lower Your New Hampshire Premium
Most insurers offer a range of discounts that can shave 5 to 30 percent off your premium. You often have to ask for them, and some require you to meet specific criteria. The most widely available discounts in New Hampshire include safe driver, multi-policy, and good student discounts, but there are others worth exploring.
- Safe driver discount: Available to drivers with no accidents or violations for three to five years. Some carriers offer an additional telematics discount if you allow them to monitor your driving habits through a smartphone app or plug-in device.
- Multi-policy (bundling) discount: Save 10 to 25 percent when you combine auto insurance with homeowners, renters, or life insurance from the same insurer. This is one of the easiest discounts to qualify for and often delivers the biggest savings.
- Good student discount: Full-time students with a B average or better can save 5 to 15 percent. The discount typically applies to drivers under 25 who are still in school.
- Vehicle safety and anti-theft discounts: Cars with airbags, electronic stability control, and alarm systems often qualify for small discounts.
- Low-mileage discount: If you drive fewer than a certain number of miles per year (often 7,500 to 10,000), you may qualify for a reduced rate.
To maximize savings, ask every insurer you contact for a complete list of discounts and confirm which ones you qualify for. Do not assume that a discount will be applied automatically. In many cases, you have to opt in or provide documentation, such as a transcript for the good student discount or a declaration page from your homeowners policy for the bundling discount. Stacking multiple discounts can cut your premium by hundreds of dollars per year.
Average Rate Ranges for Different Coverage Levels in New Hampshire
New Hampshire's optional insurance system means there is no single "average" rate that applies to everyone. Your cost depends heavily on how much coverage you choose. To give you a realistic picture, here are typical annual premium ranges for various coverage levels for a 40-year-old driver with a clean record driving a mid-size sedan. These figures are estimates based on industry data and can vary by insurer, town, and personal factors.
- Minimum liability only (25/50/25): $400 to $700 per year. This is the cheapest option but leaves you exposed to uninsured drivers and serious accidents.
- Liability plus uninsured motorist (50/100/50 UM): $600 to $900 per year. A smarter choice for most drivers, providing a balance of affordability and protection.
- Full coverage (100/300/100 with comprehensive and collision, $1,000 deductible): $1,200 to $2,000 per year. Recommended if you have a newer vehicle or significant assets to protect.
- High-risk driver with one at-fault accident or DUI: $2,000 to $4,000 per year. Rates drop as incidents age off your record.
Keep in mind that these ranges are for illustration only. The only way to know your exact rate is to get personalized quotes from multiple insurers. Rates can differ by hundreds of dollars for the same driver and coverage level, so comparing is essential. If you have bad credit or a spotty driving record, you may face higher rates or rejection from some carriers. In that case, you might need to work with a specialist. If you are also financing a vehicle and struggling to get approved, AutoTitleLoan connects consumers with auto loan financing options, including for those with bad credit or past bankruptcies, which can help you secure a vehicle while you rebuild your insurance profile.
How to Compare Quotes and Find the Lowest Cost Coverage
Comparison shopping is the single most effective way to lower your car insurance cost in New Hampshire. Because rates vary so widely, getting quotes from at least three to five insurers can save you 20 to 50 percent compared to accepting the first offer. The process is straightforward if you gather the right information and approach it systematically.
Start by deciding on the coverage levels you need. At a minimum, carry uninsured motorist coverage at the state minimum or higher, and consider medical payments coverage if your health insurance has a high deductible. If you have a newer car or a loan, full coverage is usually required by the lender and is wise anyway. Once you know your target coverage, gather your personal information: driver's license numbers for all household drivers, vehicle identification numbers, current insurance declarations, and details about your driving history.
Then request quotes from multiple sources. You can contact insurers directly, use an independent agent who represents several companies, or use an online comparison tool. Independent agents are particularly valuable in New Hampshire because they can shop your policy among multiple carriers and explain the nuances of state-specific coverage. When you get a quote, ask about every discount you might qualify for and confirm that the quote includes all the coverage you requested. Be wary of quotes that seem unusually low; they may exclude uninsured motorist coverage or use minimum limits that leave you underprotected.
After you have several quotes, compare them side by side. Look beyond the premium to consider the insurer's financial strength, customer service ratings, and claims handling reputation. A slightly higher premium from a well-rated insurer can be worth it if you ever need to file a claim. Also ask about payment plans and whether you can save by paying in full or enrolling in autopay. Once you choose a policy, review it annually and re-shop every two to three years or whenever your circumstances change (marriage, moving, buying a new car) to make sure you are still getting the best rate.
Additional Strategies to Keep Your New Hampshire Car Insurance Affordable
Beyond discounts and comparison shopping, several habits and decisions can help you maintain low premiums over the long term. Raising your deductible is one of the simplest ways to reduce your premium: moving from a $500 deductible to $1,000 can save 10 to 20 percent on comprehensive and collision coverage. Just make sure you have the cash available to cover the higher deductible if you need to file a claim.
Maintaining a clean driving record is the most powerful long-term strategy. Every accident and ticket raises your rate, and the effect can last three to five years. Defensive driving courses can help you brush up on skills and may qualify you for a discount with some insurers. If you have a teen driver, adding them to your policy will increase your premium, but you can manage the cost by choosing a safe vehicle, enrolling them in a driver training course, and asking about good student discounts.
Consider your vehicle choice carefully. Before you buy a car, get insurance quotes for the models you are considering. A car with a high safety rating, inexpensive parts, and a low theft rate will cost less to insure than a sports car or a luxury SUV. Also, think about dropping comprehensive and collision coverage on an older vehicle that is worth less than the premiums you would pay for that coverage. If your car is worth only a few thousand dollars, the extra premium may not be worthwhile.
Finally, review your policy regularly. Life changes such as moving to a new town, changing jobs, or paying off your car can affect your rate. Notify your insurer of any changes that could lower your premium, such as a shorter commute or installing a security system. And always ask about new discounts when you renew. Insurers frequently introduce new programs, and you may qualify for savings you did not have before.
Low cost car insurance in New Hampshire is within reach if you understand the state's optional system, prioritize uninsured motorist coverage, and take advantage of every discount available. By comparing quotes from multiple insurers and staying proactive about your policy, you can protect yourself and your wallet without paying more than necessary.