Auto Insurance for College Students Living Away From Home
Keep your college student covered without overpaying. Call (833)-214-7506 for help comparing auto insurance for college students living away from home.
By John Miller
When your child heads off to college, the logistics pile up fast: housing forms, meal plans, class registration, and that lingering question about the car. If your student is taking a vehicle to campus, you need to understand exactly how auto insurance for college students living away from home works. The good news is that in many cases, you can keep your student on your existing policy and pay far less than you might expect. The bad news is that a few common mistakes, like failing to report a new address or assuming a dorm counts as a permanent move, can create coverage gaps or surprise premium hikes. This guide walks you through the rules, the savings, and the practical steps to get it right.
How Your Student's Living Situation Affects Auto Insurance
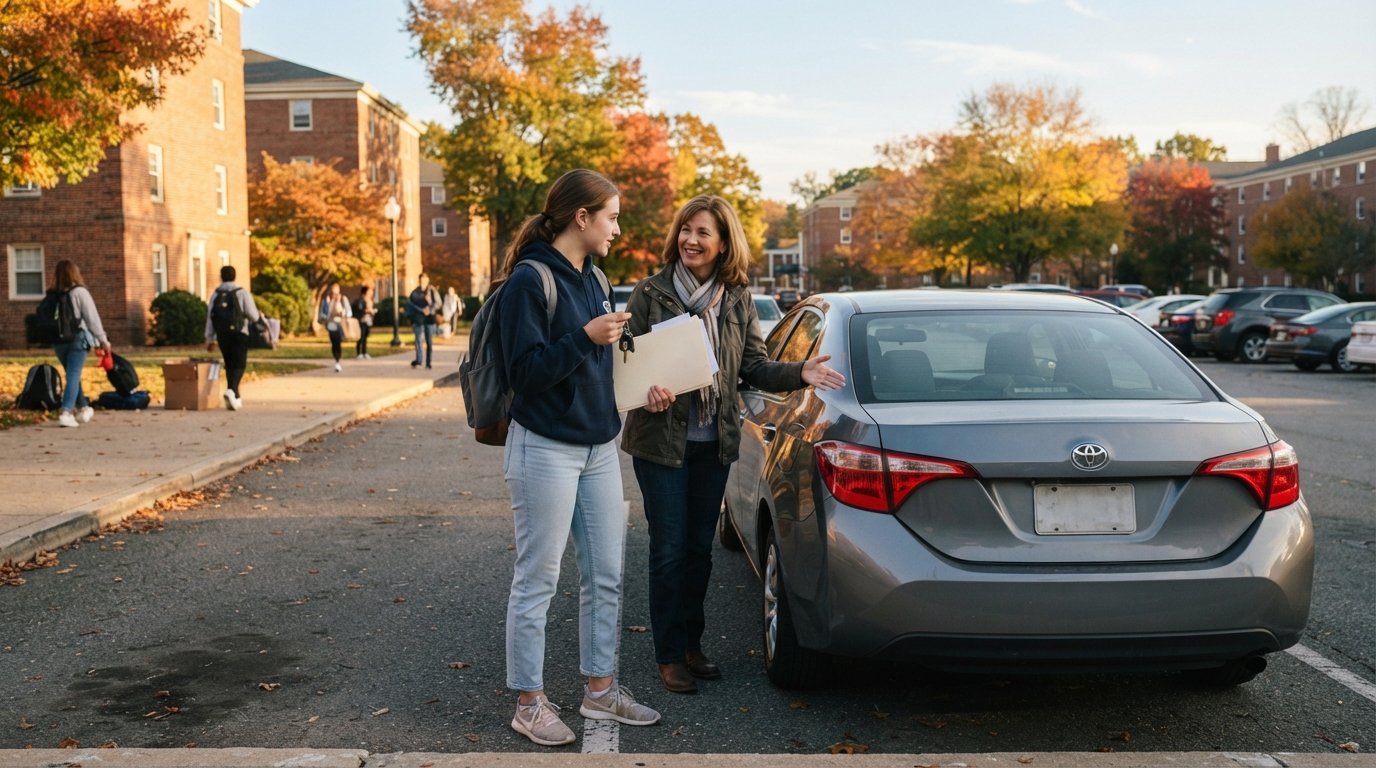
Insurance companies care about where a vehicle is garaged, meaning the address where it is primarily parked and driven. When a college student lives away from home, that location may change depending on the type of housing. A dormitory, a fraternity or sorority house, and an off-campus apartment all get treated differently by insurers. In most states, living in a dorm while enrolled full time does not count as establishing a new permanent residence, so the student can usually remain on the parent's policy. Off-campus apartments, however, often require the student to be listed at that new address, which can change rates based on the local area's accident and theft statistics.
The distance between home and school also matters. Many insurers have a threshold, often 100 miles, that determines whether a student is considered "away at school" for rating purposes. If your student attends a college more than 100 miles from home and does not have a car on campus, you may qualify for a distant student discount. If the student does bring a car, the rating territory shifts to the campus zip code, and rates can go up or down depending on that area. Always tell your insurer the truth about where the car is kept; misrepresenting the garaging address can lead to a denied claim.
Another factor is whether the student is listed as a primary or occasional driver. If your student has their own car at school and drives it daily, they should be the primary driver on that vehicle. If they only use the car for occasional trips home, they might be listed as an occasional driver, which can lower the premium. Getting this classification right protects you at claim time and keeps your rates accurate.
Why Keeping Your Student on Your Policy Usually Saves Money
For most families, the cheapest option is to keep the college student on the parent's auto policy. Multi-car discounts, multi-policy discounts, and the length of your customer history all work in your favor. A separate policy for a young driver often costs significantly more because the student loses access to those household discounts and may be rated as a new customer with no loyalty benefits. Even if your premium rises when you add a driver, that increase is usually far less than the cost of a standalone policy.
There is a catch: not all insurers allow a student to stay on the policy if they live in a different state. Some companies require the student to be listed on a policy in the state where the car is garaged, especially if the student has a driver's license from that state. If your student crosses state lines for school, call your insurer and ask about their rules. You may need to add the student as a driver on your policy while keeping the car registered at your home address, or you may need a separate policy in the campus state. Understanding these rules early prevents mid-semester surprises.
If you are also insuring a rental property or a home, bundling your auto and property policies can unlock additional savings that offset the cost of adding a student driver. Our guide on auto insurance for renters and homeowners explains how bundling works and where the biggest discounts hide, which is especially useful if your student lives off campus in a rented apartment.
Key Discounts for College Students Living Away From Home
Insurers offer several discounts aimed squarely at students, and stacking them can meaningfully reduce your premium. The most common is the good student discount, which rewards students who maintain a B average or higher. You will typically need to provide a transcript or a letter from the registrar each semester or year. Another is the distant student discount, which applies when the student attends school far from home and does not keep a car on campus. Some companies also offer a student away at school discount that reduces the premium while the student is living on campus without a vehicle.
Here are the discounts most worth asking about:
- Good student discount: for maintaining a GPA of 3.0 or higher (or a B average).
- Distant student discount: for students living more than 100 miles from home without a car at school.
- Driver training discount: for completing an approved defensive driving or safety course.
- Multi-car discount: for keeping multiple vehicles on the same policy.
- Multi-policy discount: for bundling auto with renters or homeowners insurance.
Each discount has its own eligibility rules and verification requirements. For example, the good student discount may need to be renewed every term, and the distant student discount may require proof of enrollment and a statement that no vehicle is kept at school. Ask your insurer for a full list of discounts and confirm which ones your student qualifies for before you assume the rate is final. In many cases, a single phone call can shave hundreds of dollars off the annual premium.
When Your Student Needs Their Own Policy
There are situations where a separate policy makes more sense than staying on a parent's plan. If your student is financially independent, owns the car outright, and lives in a different state permanently, a standalone policy may be required by state law. Similarly, if your student's driving record includes accidents or violations that would raise the entire household's rates, separating them onto their own policy can protect the rest of the family from premium increases. Finally, if your student is a graduate student or older than the typical undergraduate age, some insurers will no longer allow them to remain on a family policy.
Before making a switch, compare the total cost. A separate policy means losing the multi-car and multi-policy discounts, and the student may pay a higher base rate because they are a new customer. However, if the student has a clean record and lives in a low-risk area, their own policy could be cheaper than the increase on the family plan. Run the numbers both ways, and ask about paid-in-full discounts and paperless billing credits, which can lower the cost of a standalone policy.
If your student is moving into an off-campus apartment, they may also need renters insurance to cover their personal belongings. Bundling renters and auto insurance is often the fastest way to save, and it ensures that a theft or fire at the apartment does not leave them without recourse. Many insurers offer a bundling discount of 5 to 15 percent when both policies are with the same company.
Steps to Update Your Policy When Your Student Moves
Moving to college is a transition, and your insurance policy should transition with it. The most reliable approach is to call your insurer or agent before the move and confirm exactly what they need. Then follow these steps in order:
- Notify your insurer of the new address and the date the student will be living there.
- Confirm whether the student will have a car on campus or will be a distant student without a vehicle.
- Provide documentation for any discounts, such as a transcript for the good student discount or proof of enrollment for the distant student discount.
- Ask whether the student should be listed as a primary or occasional driver on each vehicle.
- Request a new declaration page showing the updated drivers, vehicles, and garaging address.
After the update, review the policy to make sure the coverage limits still make sense. If your student is driving in a state with different minimum liability requirements, you may need to adjust your limits to comply. Also check whether your policy includes uninsured and underinsured motorist coverage, which protects your student if they are hit by a driver with no insurance. This coverage is especially valuable for students driving in unfamiliar areas.
If you want to compare rates from multiple carriers before you commit, you can use a free quote comparison service to see what different insurers would charge for your student's situation. Getting quotes from several companies side by side is the fastest way to find out whether staying on your policy or switching to a new one is the better financial move. For a no-obligation look at available rates, you can compare free auto insurance quotes online and see how your student's profile affects pricing across carriers.
Common Mistakes That Cost Families Money
The single most expensive mistake is failing to report that the student has a car at school. If the insurer believes the car is garaged at home but it is actually 200 miles away, a claim could be denied or the policy could be cancelled for misrepresentation. Another common error is assuming that a dorm address automatically qualifies for the distant student discount. The discount usually requires that the student does not have a vehicle at school, so if they take a car, the discount does not apply.
Families also lose money by forgetting to renew student discounts. The good student discount often expires after one semester or one academic year, and if you do not resubmit the transcript, the discount silently drops off the renewal. Set a calendar reminder to send in updated grades each term. Finally, many parents neglect to shop around after adding a student driver. The premium increase can be substantial, and a different insurer may offer a much better rate for the same coverage. Spending 20 minutes comparing quotes can save hundreds of dollars over the course of a year.
Another overlooked issue is the gap between semesters. If your student comes home for the summer and the car is back in your driveway, tell your insurer. Some companies offer a reduced rate when the vehicle is not being driven at school, while others may need to adjust the garaging address again. Keeping the policy accurate year-round prevents billing surprises and ensures that coverage is in force whenever and wherever the car is driven.
Auto insurance for college students living away from home does not have to be complicated or expensive. By keeping your student on your policy when possible, claiming every discount they qualify for, and updating your insurer whenever the living situation changes, you can maintain solid coverage without overpaying. Start the conversation with your insurer early, document every change, and revisit your policy each semester. A few proactive steps now will protect your student and your budget all year long.