Online Auto Insurance Comparison Sites: Pros and Cons
Online auto insurance comparison sites can save you time and money, but they also come with trade-offs. Here is what to know before you enter your details.
By Elowen Parker
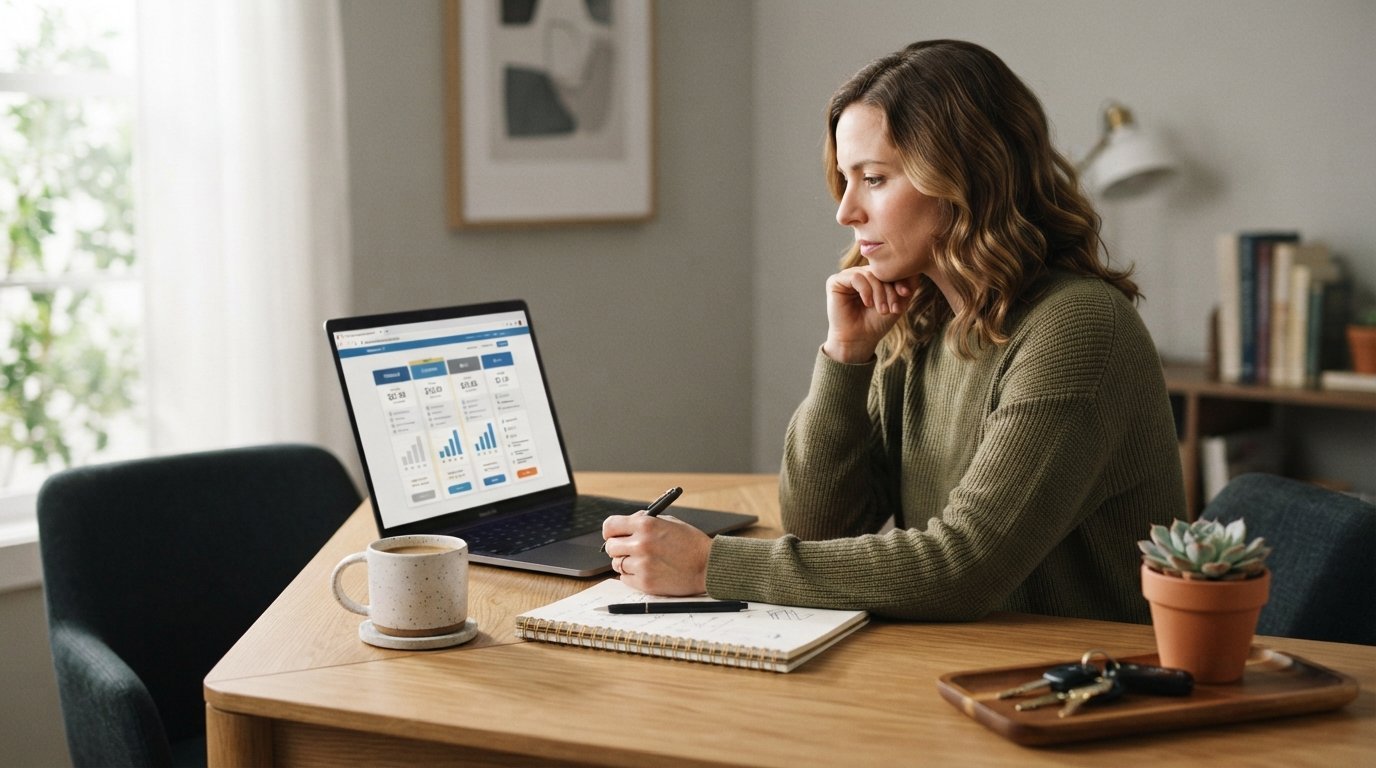
You sit at your laptop with three browser tabs open, each showing a different car insurance quote that looks almost identical but costs $400 more per year than the next. One site asked for your driving record, another wanted your VIN, and the third promised a rate that vanished after you entered your actual address. This is the reality of shopping for coverage in the digital age, and it raises a fair question: are these platforms actually helping drivers save money, or are they simply collecting your data and selling it to the highest bidder? Understanding online auto insurance comparison sites pros and cons before you hand over your personal information is the difference between a smart purchase and a privacy headache.
At their core, these platforms exist to solve a simple problem: finding the lowest rate without calling twenty different agents. However, the convenience comes with trade-offs that range from minor annoyances (endless email follow-ups) to significant risks (lead generation that sells your contact info to dozens of agencies). This article breaks down exactly how these sites work, where they deliver real value, and where they fall short, so you can decide when to use them and when to pick up the phone instead.
How Comparison Sites Actually Operate
The phrase "comparison site" covers a wide spectrum of business models, and confusing them can lead to unrealistic expectations. Some platforms are true aggregators that pull real-time quotes from a network of carriers through direct integrations. Others are lead-generation engines that collect your information, sell it to a handful of agents, and let those agents contact you with their own quotes. A third category operates as a hybrid, showing you a few instant estimates while simultaneously selling your data to partner agencies for follow-up calls.
The distinction matters because it determines what happens after you hit submit. If you use a genuine aggregator, you will typically see a list of prices from named insurers within minutes, and you can proceed to purchase directly from the carrier. If you use a lead-generation site, you will not see actual quotes at all. Instead, you will receive phone calls and emails from agents who have purchased your information and who each want to earn your business. Neither model is inherently dishonest, but they serve different purposes.
Most consumer-facing platforms fall somewhere in the middle. They show you a teaser rate or a "starting at" figure to get you in the door, then require full personal details before revealing the real price. Once you provide that information, the site either displays quotes from its carrier partners or routes your details to agents. This is why two people with identical driving records can have wildly different experiences on the same website: the back-end partnerships vary by state, vehicle type, and even the time of day.
Understanding this landscape is essential because the online auto insurance comparison sites pros and cons depend heavily on which type you are using. A true aggregator saves time and provides transparency. A lead-generation site might save you the effort of calling around, but it also exposes you to a barrage of sales outreach. Knowing which one you are dealing with before you enter your phone number is half the battle.
The Real Advantages of Comparing Coverage Online
The most obvious benefit is speed. In the past, getting five quotes meant five phone calls, each lasting twenty minutes or more. Today, you can enter your details once and receive multiple rates in under ten minutes. For drivers who value their time, this efficiency alone justifies using a comparison platform. The convenience is particularly valuable for people with straightforward profiles: clean driving records, standard vehicles, and no unusual coverage needs.
Beyond speed, these sites offer a level of transparency that was previously difficult to achieve. When you call an agent directly, you have no idea whether the rate they quote is competitive or inflated. A comparison site, by contrast, shows you multiple prices side by side, which gives you leverage. Even if you ultimately choose to buy from a specific carrier, you can use the competing quotes as a negotiation tool. Insurers know that shoppers who compare are more likely to switch, so they often reserve their best rates for these platforms.
Another advantage is educational. Many comparison sites include guides, glossaries, and coverage explanations that help you understand what you are buying. This is especially useful for first-time buyers, people new to a state, or anyone who has always relied on a partner or parent to handle insurance decisions. The best platforms explain the difference between liability, collision, comprehensive, and uninsured motorist coverage without overwhelming you with jargon.
Here are the primary benefits that make these platforms worth considering:
- Time savings: Multiple quotes in minutes rather than hours of phone calls.
- Price transparency: Side-by-side rates that reveal how much you could save by switching.
- Educational resources: Guides and FAQs that explain coverage options in plain language.
- Negotiation power: Competing quotes give you leverage when speaking with agents.
- Access to niche carriers: Some platforms surface smaller insurers you might not find on your own.
These benefits are real, but they come with caveats. The quotes you see are only as accurate as the information you provide, and some platforms inflate savings estimates to encourage you to complete the form. Additionally, not every carrier participates in every comparison network, so you may miss out on the best rate if your ideal insurer does not partner with the site you are using. The advantages are substantial, but they are not unconditional.
Where Comparison Sites Fall Short
The most common complaint about comparison sites is the flood of follow-up communication. Once you submit your information, you may receive calls, texts, and emails from multiple agents for weeks. This happens because many sites sell your data as a lead to several agencies at once. While this can result in competitive offers, it also means your phone will not stop ringing until you explicitly ask to be removed from each agent's list. For anyone who values privacy or dislikes pushy sales tactics, this is a significant drawback.
Another issue is the accuracy of the quotes themselves. A rate that looks too good to be true often is. Some platforms display teaser rates that assume perfect credit, a spotless driving record, and maximum discounts that you may not qualify for. When you dig deeper, the actual premium can be hundreds of dollars higher. This bait-and-switch dynamic erodes trust and makes it difficult to know whether you are truly getting a good deal.
Coverage details are another area where comparison sites can mislead. A low monthly payment means nothing if the policy excludes the coverage you need. Some platforms prioritize price over protection, showing you the cheapest option without explaining that it carries state-minimum liability limits only. If you have a loan or lease, you need collision and comprehensive coverage, and if you have significant assets, you may need higher liability limits. A site that focuses solely on the lowest number can steer you toward inadequate protection.
Finally, there is the question of data security. When you enter your name, address, date of birth, and driving history into a website, you are trusting that site to protect your information. Not all comparison platforms have robust security measures in place. Some sell data to third parties without clear disclosure, and others have experienced breaches. Reading the privacy policy before entering personal details is a basic precaution that many users skip.
The online auto insurance comparison sites pros and cons are not evenly balanced for every driver. If you have a complex profile, such as a recent accident, a DUI, or a specialized vehicle, the automated nature of these platforms may not serve you well. In those cases, working directly with a licensed agent who can advocate on your behalf is often the better path.
When to Use a Comparison Site and When to Call an Agent
Comparison sites work best for drivers with simple, predictable profiles. If you have a clean record, a standard vehicle, and you are simply looking for the most competitive rate on a policy that meets your state's requirements, these platforms can save you time and money. They are also useful for window shopping: even if you do not buy immediately, seeing the range of available rates gives you a benchmark for what you should expect to pay.
For more complex situations, a direct conversation with a licensed agent is usually more effective. Agents can explain nuances that a website cannot, such as how a recent claim will affect your premium, whether a specific discount applies to your situation, or how to structure a policy that covers a teenage driver without breaking the bank. They can also shop your profile with carriers that do not participate in comparison networks, which may yield a better rate than anything you see online.
If you are a renter or homeowner, bundling your auto insurance with your renters or homeowners policy can unlock discounts that comparison sites often overlook. Our guide on auto insurance for renters and homeowners explains how to combine policies strategically to reduce your overall premium. This is a case where a human agent can identify savings that an automated platform might miss.
One practical approach is to use a comparison site as a starting point, then verify the best quotes with a direct call to the carrier or an independent agent. This hybrid strategy gives you the speed of online comparison and the accuracy of a personalized review. It also ensures that you are not missing out on discounts or coverage options that only become apparent in conversation.
For drivers who want a no-obligation starting point, platforms like Free Auto Insurance Quotes Online provide free quotes from multiple carriers and educational resources that explain coverage options in plain language. These services can be a useful first step before you commit to a specific policy or agent.
How to Get the Most From Comparison Platforms
If you decide to use a comparison site, a few simple habits can improve your results and reduce the downsides. First, use a dedicated email address and a Google Voice number or similar secondary phone number. This keeps your primary inbox and phone line free from the inevitable follow-up barrage. You can always provide your real contact information later, once you have narrowed your options to one or two serious contenders.
Second, be honest about your driving record and vehicle details. Inflating your good driving history or underestimating your annual mileage may produce a lower quote, but the carrier will verify your information before issuing a policy. If discrepancies are found, your rate will increase, and in some cases, the insurer may cancel the policy. Accurate inputs produce accurate quotes, which saves you from unpleasant surprises.
Third, compare coverage, not just price. Look at the liability limits, deductible amounts, and optional coverages included in each quote. A policy that costs $20 less per month but drops rental reimbursement or roadside assistance may not be the better deal. The goal is to find the best value, not the lowest number.
Finally, do not rely on a single comparison site. Different platforms partner with different carriers, so using two or three increases your chances of finding the best rate. It takes a few extra minutes, but the potential savings are worth it. Once you have a shortlist, call the top two or three carriers directly to confirm the quote and ask about additional discounts.
Understanding the online auto insurance comparison sites pros and cons empowers you to use these tools strategically rather than passively. They are not a replacement for informed decision-making, but they can be a valuable part of your research process when used with clear expectations and a healthy dose of skepticism.
The right approach depends on your profile, your patience for sales calls, and how much time you are willing to invest in the process. For some drivers, a comparison site is the fastest path to savings. For others, a conversation with a licensed agent yields better results. By knowing the strengths and weaknesses of each option, you can choose the method that works best for your situation and drive away with a policy that protects you without overpaying.