How to Get Car Insurance with a Foreign Drivers License
Learn how to get car insurance with a foreign drivers license and drive legally. Call 8332147506 for expert assistance on securing your policy.
By Adrian Fox
Navigating the American roadways is a rite of passage for many newcomers, whether you are an expat, an international student, or a visitor planning an extended stay. You have your vehicle, your enthusiasm for the open road, and your home country's driving permit in hand. Then comes the administrative wall: securing auto insurance. For many drivers, the process of learning how to get car insurance with a foreign drivers license feels like solving a riddle wrapped in bureaucratic red tape. You might assume that without a state-issued United States license, you are uninsurable. Fortunately, that assumption is incorrect. While the process requires a bit more documentation and patience, major carriers and specialized agencies do provide coverage for drivers holding international permits.
Understanding the landscape is the first step toward getting legally behind the wheel. Insurance companies in the United States are private businesses, and their risk assessment rules vary wildly. Some carriers will reject a foreign license outright, while others will welcome you with open arms, albeit often at a higher premium. The key is knowing which insurers to approach, what documentation to prepare, and how to present your driving history in a way that satisfies underwriters. This guide will walk you through the specific steps to secure a policy, ensuring you avoid gaps in coverage that could lead to legal trouble or financial ruin.
Understanding the Legal Requirements and Risk
Before diving into applications, it is crucial to understand why insurers view foreign licenses with skepticism. In the United States, auto insurance is mandatory in almost every state. The system relies on a points system and driving records that are easily accessible via state databases. When you present a license from another country, the insurer cannot instantly verify your history. They cannot see if you have a history of DUIs, reckless driving, or accidents in your home country. This lack of verifiable data translates to perceived risk. Consequently, you are often categorized as a "high-risk" driver simply because you are an unknown quantity.
However, driving with a foreign license is generally legal in the US for a certain period, provided you meet specific conditions. Most states allow you to drive with a valid foreign license for a limited time, often ranging from 30 days to a year, depending on your visa status and the state's specific laws. During this grace period, you are required to carry insurance that meets the state's minimum liability requirements. If you are caught driving without insurance, the penalties can be severe, including fines, license suspension, and even vehicle impoundment. Therefore, securing a policy is not just a financial safeguard; it is a legal necessity.
The challenge lies in the fact that many standard online quoting tools are not built to handle foreign license numbers. They often require a state-issued license number to proceed. If you try to enter a foreign number into a standard online form, the system will likely reject it. This does not mean you cannot get insurance; it simply means you need to bypass the automated systems and speak with a human being. Understanding this distinction saves hours of frustration and prevents you from mistakenly believing you are ineligible for coverage.
Steps to Secure Coverage with an International Permit
Securing a policy requires a proactive approach. You cannot simply wait for the insurance to find you; you must actively seek out carriers that specialize in or accommodate international drivers. The process generally follows a structured path, starting with gathering the right documents and moving toward specialized quotes. Following a clear framework helps you avoid the common pitfalls that lead to denied applications.
Here is a step-by-step framework to guide you through the process:
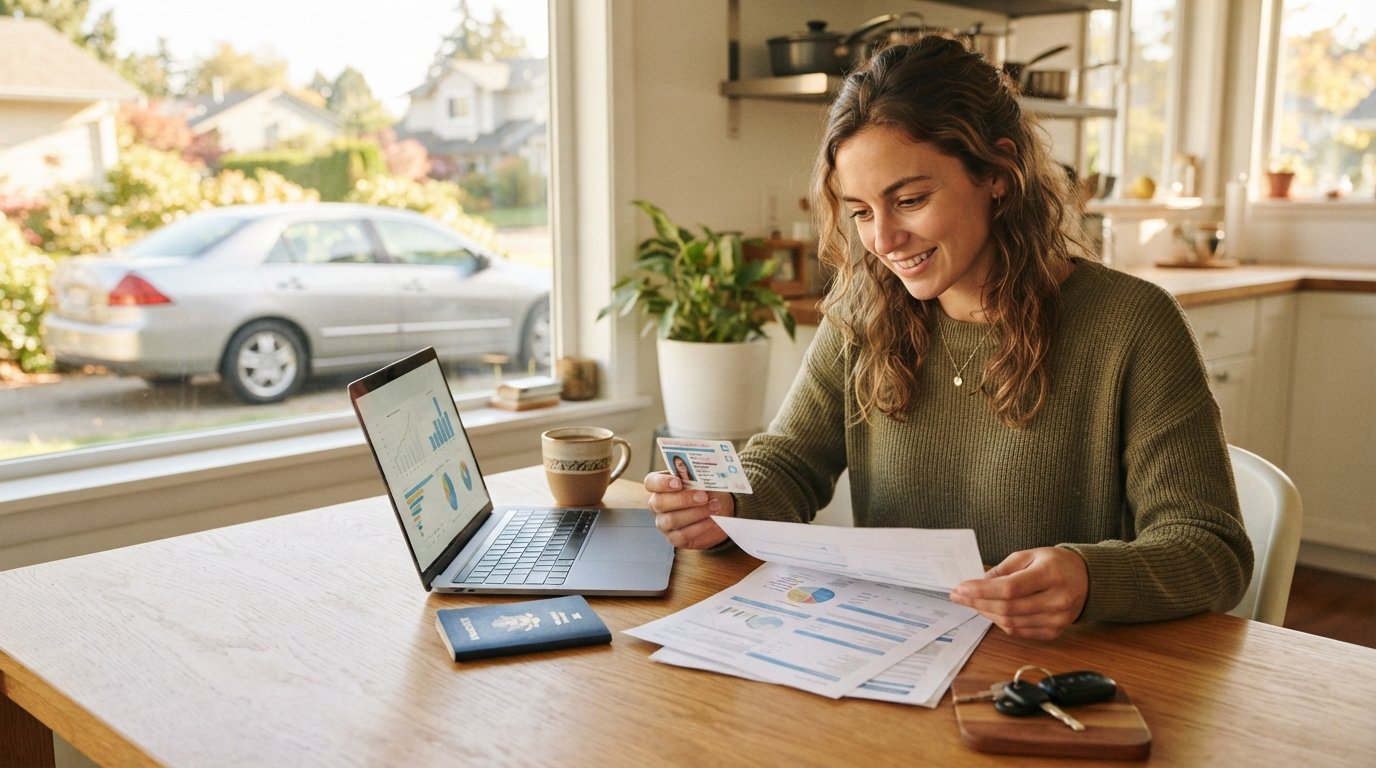
- Gather Your Documentation: Before contacting any agent, have your passport, visa, foreign drivers license, and proof of address (utility bill or lease) ready. If you have an International Driving Permit (IDP), include that as well, as it serves as a translation of your license.
- Obtain a Driving History Letter: Contact your home country's motor vehicle department or embassy to request a certified letter detailing your driving record. A clean history from your home country can sometimes be used to prove you are a safe driver, potentially lowering your premium.
- Target the Right Carriers: Avoid the temptation to only use large, national online comparison sites. Instead, look for regional carriers or agencies that specialize in "non-standard" auto insurance. These insurers are more accustomed to handling unique situations like foreign licenses.
- Visit a Local Agency: Walk into a local insurance agency in your city. Independent agents often have relationships with multiple carriers and can manually submit your information to underwriters who are willing to consider foreign documentation.
- Be Transparent: Do not attempt to use a fake Social Security Number or someone else's license number to get a quote online. This constitutes fraud and will void your policy if discovered. Always be upfront about your status and documentation.
After you have gathered these documents, the conversation with the insurer changes. You are no longer a generic data point in an algorithm; you are a specific case that an underwriter can evaluate. This human element is often the deciding factor between a rejection and an approval. It is also worth noting that if you are in the process of buying a new car, you might find specific guidance on best affordable car insurance for new vehicles to help you understand how vehicle value impacts your premium, regardless of your license status.
Once you have a policy in place, you must maintain it. Some insurers may require you to obtain a state license within a certain timeframe, such as 30 or 60 days, as a condition of continued coverage. Failing to do so could result in your policy being cancelled. Therefore, it is vital to understand the terms of your specific agreement. If you are planning to stay long-term, you should begin the process of getting a state license immediately, as this will eventually lower your insurance costs significantly.
Factors Influencing Your Premium
When you finally find an insurer willing to write a policy for a foreign license holder, the price tag might be higher than you expect. This is not necessarily a penalty for being foreign; it is a reflection of the risk profile associated with unverified driving history. However, several factors can influence how much you pay, and understanding these can help you find ways to mitigate the costs.
The type of vehicle you drive plays a massive role. If you are driving a high-performance sports car, you will pay more than if you are driving a used sedan. Similarly, your age and marital status factor into the equation. Younger drivers, particularly those under 25, are statistically riskier to insure, and this holds true regardless of where their license was issued. Your location also matters; urban areas with high traffic density and theft rates typically have higher premiums than rural areas.
One of the most effective ways to lower your premium is to demonstrate a clean driving history. If you can provide a certified translation of your driving record from your home country showing no accidents or violations, some insurers will take this into account. Additionally, if you have a history of insurance in your home country, providing proof of that continuous coverage can sometimes help. Insurers like to see that you are a responsible driver who maintains coverage, even if the previous policy was in a different country.
It is also important to consider the coverage limits you select. While it is tempting to choose the state minimum liability coverage to save money, this can be a dangerous gamble. If you cause an accident, the state minimum might not be enough to cover the damages, leaving you personally responsible for the excess. For drivers with foreign licenses, who are already in a precarious position regarding documentation, having robust coverage is even more critical to protect your assets and your ability to stay in the country.
Using Comparison Tools and Resources
Finding the right policy requires comparison. You should not settle for the first quote you receive, as prices can vary by hundreds of dollars for the same coverage. However, as mentioned, standard online comparison tools often fail when they encounter a foreign license number. This is where specialized consumer resources become invaluable. Platforms like FreeAutoInsuranceQuotesOnline are designed to help drivers understand their options and connect with carriers who can handle unique situations. These platforms provide educational articles and tools that can guide you through the process of comparing quotes, ensuring you are not overpaying for coverage.
When using these tools, be prepared to input your information manually or speak with a representative. The goal is to get your information in front of as many underwriters as possible. If one carrier rejects you, another might accept you. The key is volume and persistence. Do not get discouraged by automated rejections. Instead, use them as a signal to pivot your strategy toward more flexible, human-centric agencies.
Furthermore, consider bundling your auto insurance with other policies if you have them. If you are renting an apartment, you likely have renters insurance. If you own a home, you have homeowners insurance. Bundling these policies with your auto insurance can lead to significant discounts. Even with a foreign license, many carriers are eager to get your entire insurance portfolio and will work with you on the auto policy to secure the home or renters business. This is a powerful negotiation tool that you should leverage during your search.
Getting Quotes and Finalizing the Policy
Once you have identified a potential carrier or agency, the final step is to get a formal quote and bind the policy. This process typically involves a phone call or an in-person meeting. You will need to provide all the documentation gathered in the earlier steps. The agent will then run your information through their system. Be prepared for the agent to ask questions about your driving history in your home country. Answer honestly and provide documentation where possible.
If the quote is acceptable, you will need to pay the premium. Most insurers require a down payment, with the remainder paid in monthly installments. Be aware that some insurers may require a larger down payment for drivers with foreign licenses, as they are considered a higher credit risk. Once payment is made, you will receive your insurance card and declaration page. Keep these documents in your vehicle at all times, as you will need to show them if you are pulled over by law enforcement.
Finally, remember that this policy is likely a temporary solution. As soon as you are eligible, you should obtain a state-issued drivers license. This will not only simplify the insurance process but will also likely lower your premiums substantially. Once you have a state license, you can re-shop your policy and take advantage of the standard discounts and rates available to domestic drivers. Until then, the policy you have secured will keep you legal and protected on the road.
Securing auto insurance with a foreign license is a hurdle, but it is one that thousands of drivers clear every year. With the right documentation and a willingness to look beyond the standard online forms, you can find a policy that fits your needs and your budget. Drive safely, stay insured, and enjoy the freedom of the American road.