How to Add a Driver to Your Car Insurance Policy
Adding a driver to your policy is simple when you know the steps. Get a quote and call (833)-214-7506 for help comparing options.
By James Morgan
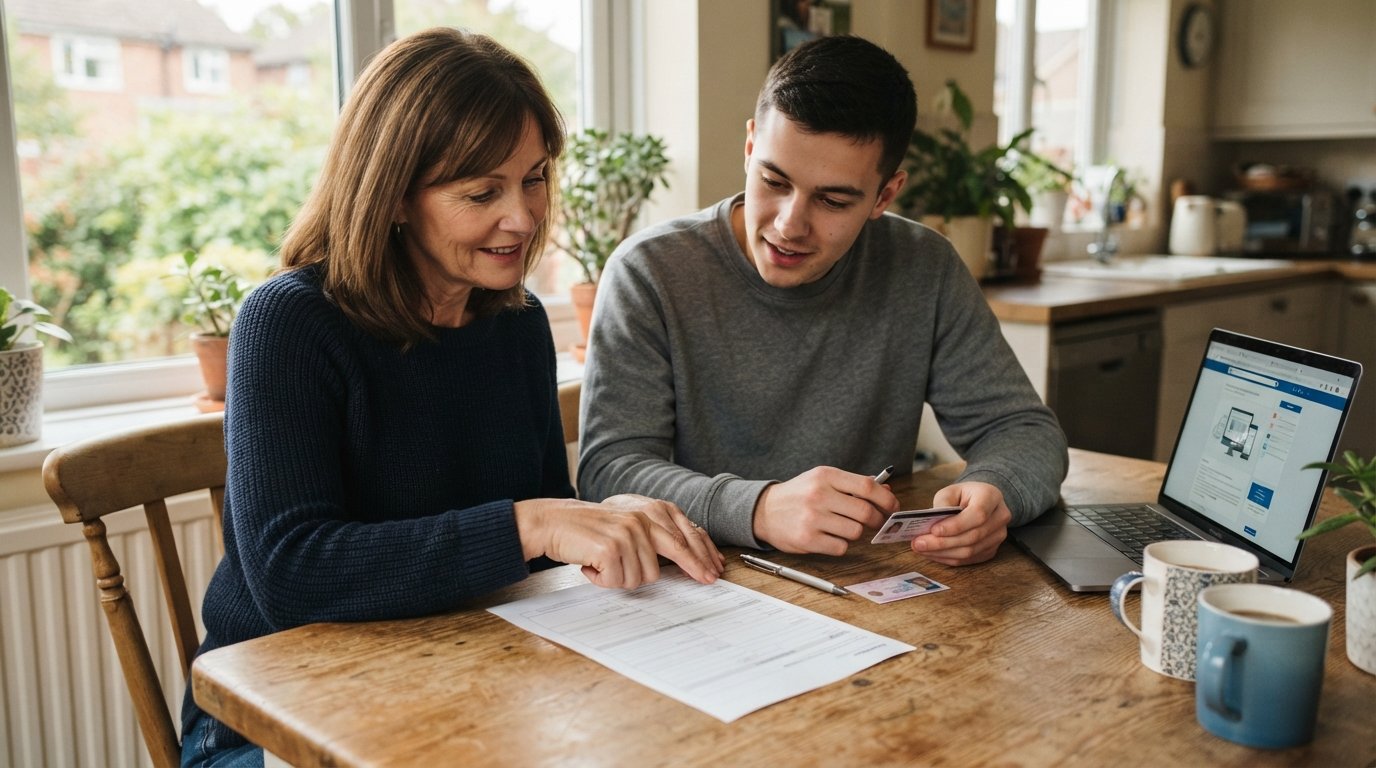
Adding a driver to your car insurance policy is one of those tasks that feels simple until you actually sit down to do it. Maybe your teenager just got a learner's permit. Maybe you got married and your spouse needs coverage. Or maybe a roommate borrows your car often enough that you want to make sure everyone is protected. Whatever the reason, the process is manageable when you know what information to gather, what questions to ask, and how the change might affect your premium. This guide walks you through how to add a driver to your car insurance policy step by step, including the details insurers typically request, the scenarios that change the math, and the timing that keeps you compliant.
Information You Need Before You Add a Driver
Insurance companies price risk based on who is likely to be behind the wheel. Before you call your insurer or log into your account, collect the basics for the person you want to add. Having this information ready speeds up the process and reduces the chance of errors that could cause a claim denial later.
Most insurers will ask for the following details about the new driver:
- Full legal name, date of birth, and driver's license number
- License status (learner's permit, provisional, or full license) and the state that issued it
- Driving history for the past three to five years, including accidents, tickets, or claims
- Relationship to you (spouse, child, roommate, or other)
- Estimated annual mileage or percentage of time they will drive your vehicle
If the person is a teen with a learner's permit, some insurers only require a name and date of birth until they get a full license. Others want the permit number right away. If the driver lives in your household but will have their own separate policy, you still need to tell your insurer they live there, because many companies require you to list all household members even if they are not added as drivers. This is a common source of confusion: listing a household member is not the same as adding them as a rated driver, but both require disclosure.
Gather your own policy number and vehicle information as well. You will need to confirm which vehicle the new driver will primarily operate. If your policy covers multiple cars, the insurer may assign the new driver to a specific vehicle for rating purposes.
How to Add a Driver to Your Car Insurance Policy: Step by Step
The exact process varies by insurer, but the sequence is fairly consistent. Following these steps helps you avoid gaps in coverage and surprise charges.
- Contact your insurer or log into your online account. Many companies let you add a driver through their mobile app or website. If you prefer human help, call the customer service number on your policy declarations page.
- Provide the new driver's information. Share the details listed above. Be honest about driving history. Omitting a ticket or accident can be considered misrepresentation and may lead to a denied claim.
- Confirm the effective date. Ask when the coverage for the new driver begins. Some insurers add drivers immediately; others process the change at the next renewal. You want coverage to start the day the person begins driving your car.
- Review the updated premium and coverage. The insurer will recalculate your premium based on the new driver's risk profile. Ask for the new total in writing before you agree.
- Check for discounts. Adding a teen or a student may qualify you for a good student discount, a driver training discount, or a multi-policy discount if the new driver has their own renters or homeowners policy. Ask specifically which discounts apply.
After the change is processed, request an updated insurance ID card that lists the new driver. Keep a copy in the vehicle and save a digital version on your phone. If you are adding a driver to a policy that includes rental car coverage, confirm that the new driver is also covered under that provision. You can review the details in our guide on rental car coverage in your auto insurance policy to understand how permissive driving rules apply.
One more administrative note: if you are financing a vehicle, your lender may require proof of insurance that lists all drivers. Adding a driver usually does not violate a loan agreement, but it is worth a quick check with your lienholder if you are unsure.
How Adding a Driver Changes Your Premium
Adding a driver almost always changes your premium, but the direction and size of the change depend on the driver's age, record, and relationship to you. A spouse with a clean record often adds little or nothing, especially if you already have a multi-driver discount. A teen driver, on the other hand, can increase your premium significantly because statistics show young, inexperienced drivers file more claims.
Insurers use a rating factor that considers the highest-risk driver on the policy. If you add a teenager to a policy that covers a sports car, your premium may jump more than if you add them to a policy covering a minivan with safety features. Some companies offer a specific teen driver discount if the teen completes a defensive driving course or maintains a B average or better in school.
Roommates and occasional drivers fall somewhere in the middle. If a roommate drives your car only a few times a month, the insurer may classify them as an occasional driver and charge a smaller additional premium. However, if the insurer believes the roommate has regular access to your vehicle, they may require you to add them as a rated driver. The key is to describe the driving arrangement accurately. If you are unsure how to frame it, ask the insurer: "This person borrows my car about once a week for errands. How should I list them?"
It is also worth noting that adding a driver can sometimes lower your premium. If you add a spouse with a better credit-based insurance score or a longer clean driving history, the combined policy may qualify for a lower rate than your individual policy. This is not guaranteed, but it happens often enough that it is worth asking for a quote before you assume the change will cost more.
Different Scenarios: Spouse, Teen, Roommate, and Occasional Driver
The rules for adding a driver depend heavily on the person's relationship to you and how often they use your car. Here is how insurers typically treat each scenario.
Spouse. Most insurers require you to add a spouse to your policy if they live with you and have a license, unless they have their own separate policy and you provide proof. Adding a spouse is usually straightforward and often comes with a marriage discount or a multi-driver discount. If your spouse has a poor driving record, expect a higher premium, but you cannot simply leave them off the policy if they live in the same household and drive your car. Some states allow a named driver exclusion for a spouse, but that exclusion means the spouse has no coverage at all when driving your vehicle, which is rarely a good idea.
Teen driver. This is the most expensive scenario. Teens are statistically more likely to be involved in accidents, so insurers charge accordingly. You have a few options: add the teen to your policy, buy a separate policy for the teen (which is usually more expensive), or list the teen as an occasional driver if they only drive your car infrequently. Most parents add the teen to their own policy because it is cheaper than a standalone policy and because it keeps the teen covered under the family's liability limits. Be prepared for the premium to rise, and ask about good student and driver training discounts to offset the cost.
Roommate. If a roommate borrows your car regularly, you should tell your insurer. Some companies will require you to add the roommate as a driver; others will allow you to keep them as an occasional driver with a note on the policy. If the roommate has their own car and insurance, your insurer may only need to know that they live with you. If the roommate has no car and no insurance, adding them to your policy is the safest way to ensure they are covered if they drive your car. Do not assume your policy automatically covers any driver who borrows your car. Permissive use coverage exists, but it has limits, and it often does not apply to household members or regular users.
Occasional driver. A friend who drives your car once a month for a favor is usually covered under permissive use, but a friend who drives your car every week is not an occasional driver in the eyes of an insurer. The distinction matters because if you misrepresent how often someone drives your car, the insurer can deny a claim. If you are unsure where the line falls, ask your insurer directly. It is better to ask a question now than to argue about coverage after an accident.
When to Notify Your Insurer After a Household Change
Timing is critical. Most policies require you to notify your insurer within a certain number of days after a household change, such as a marriage, a new roommate, or a teen getting a license. The exact window varies by state and insurer, but a good rule of thumb is to notify your insurer as soon as the change happens, or at least within 30 days.
Here are common household changes that should trigger a call to your insurer:
- Marriage or domestic partnership
- A child or stepchild gets a learner's permit or driver's license
- A new roommate moves in who has a driver's license
- A family member moves out and takes their car off your policy
- You or a household member buys a new vehicle
If you fail to notify your insurer and the new driver has an accident, the insurer may deny the claim or cancel your policy for misrepresentation. That outcome is far worse than a premium increase. If you are adding a driver who has a poor credit history or a limited driving record, you might wonder whether alternative financing options could help them get their own vehicle and policy. For drivers who have faced rejection from traditional lenders, platforms like AutoTitleLoan connect consumers with auto loan financing options, which can be a useful resource if the new driver is also trying to buy their own car. However, for insurance purposes, the priority is always to disclose the driver to your insurer accurately and on time.
If you are adding a driver to your policy and you are also shopping for a better rate, it helps to compare quotes from multiple insurers. NewAutoInsurance.com is an independent online resource that provides consumer guidance and educational content about auto insurance. It is not an insurance carrier or broker, but it can connect you with licensed insurance agents who can provide personalized quotes. Some agents may pay a fee to be promoted, which should be considered advertising. There is no obligation to buy a policy. If you want to explore how adding a driver affects your options across different companies, requesting a quote can give you a clearer picture of the market.
Common Mistakes to Avoid When Adding a Driver
Even careful policyholders make mistakes when adding a driver. Here are the most common ones and how to avoid them.
Assuming permissive use covers everyone. Permissive use is a valuable feature, but it typically does not cover household members or people who drive your car regularly. If your teen or roommate drives your car more than a few times a year, add them explicitly.
Leaving a driver off to save money. This is a form of rate evasion. If the driver has an accident, the insurer can deny the claim, cancel your policy, and in some states, report you for insurance fraud. The short-term savings are not worth the long-term risk.
Forgetting to update your policy after a move. If a driver moves out of your household, tell your insurer. If a new driver moves in, tell your insurer. Household composition is a rating factor, and failing to update it can cause problems at claim time.
Not asking about discounts. Many insurers offer discounts for adding a spouse, a good student, a driver who completes a safety course, or a driver who bundles auto with renters or homeowners insurance. Ask specifically which discounts apply to your situation. Some discounts are automatic; others require you to request them.
Ignoring the effective date. If you add a driver on Friday but the insurer processes the change on Monday, the driver is not covered for the weekend. Confirm the exact effective date and time, and do not let the new driver get behind the wheel until coverage is active.
Final Thoughts on Adding a Driver to Your Policy
Adding a driver to your car insurance policy is a routine administrative task that protects you, your family, and anyone else who drives your car. The process is simple when you gather the right information, contact your insurer promptly, and review the updated premium and coverage before you agree. Whether you are adding a spouse, a teen, a roommate, or an occasional driver, the goal is the same: make sure the policy reflects reality so that a claim is paid without dispute. If you are unsure about your options or want to compare rates after adding a driver, reach out to a licensed insurance agent through a trusted comparison resource. A few minutes on the phone or online can save you thousands of dollars and a lot of stress down the road.