Auto Insurance for Drivers with Epilepsy or Medical Conditions
Get practical guidance on auto insurance for drivers with epilepsy or medical conditions. Call (833)-214-7506 to compare tailored quotes from licensed agents.
By Emily Roberts
Getting behind the wheel after a seizure or a new medical diagnosis can feel like a legal and financial maze. You may be asking whether you are even allowed to drive, whether your insurer needs to know about your condition, and how a single medical event could ripple into your premiums for years. The good news is that auto insurance for drivers with epilepsy or medical conditions is not a dead end. With the right information and the right agent, you can secure coverage that protects you without punishing you for a health issue you manage responsibly.
How State DMVs Handle Medical Review and Driving Privileges
Every state sets its own rules for when a driver with a medical condition must be reported, evaluated, or restricted. For epilepsy specifically, most states require a seizure-free period before you can legally drive, commonly ranging from three to twelve months. Some states require physicians to report seizures to the DMV, while others rely on self-reporting. This patchwork means your first step is always to check the rules in your state, not a national guideline.
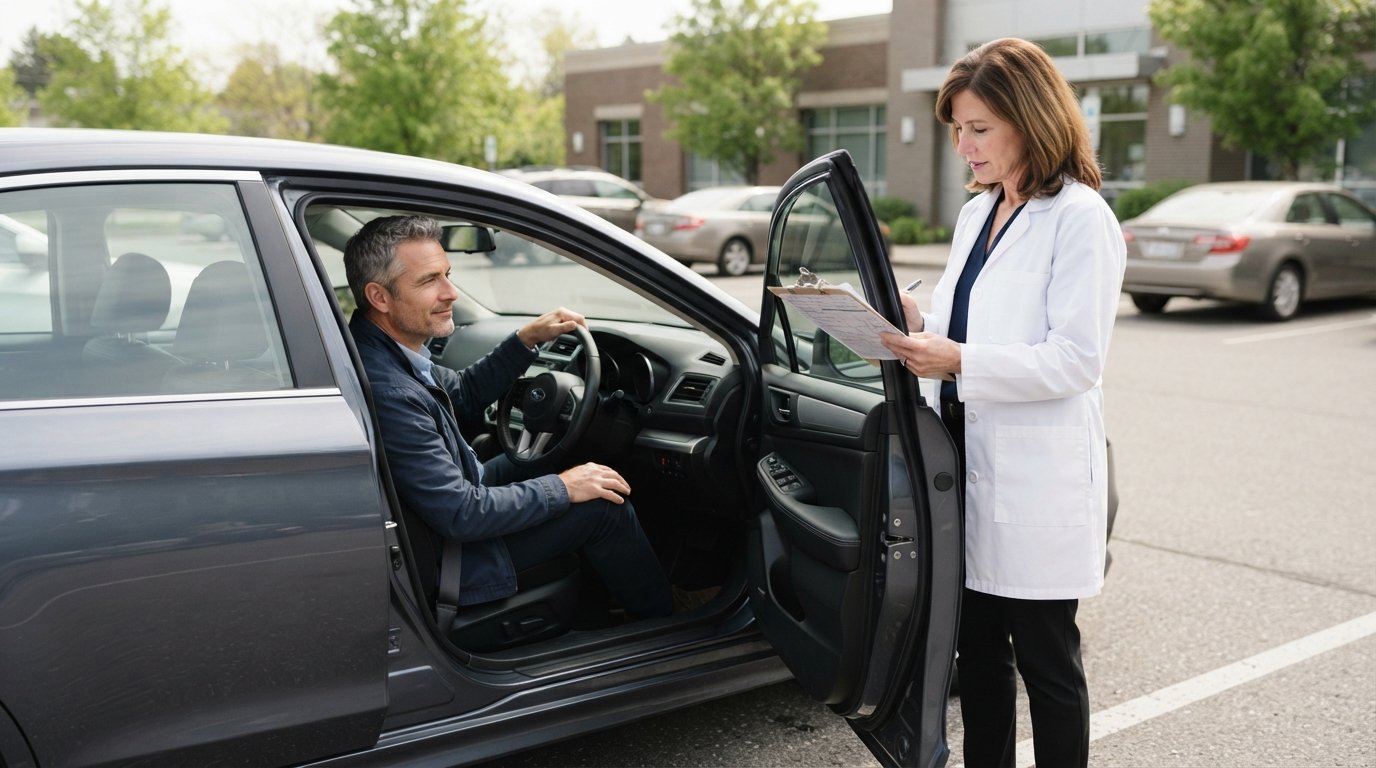
The medical review process typically works like this: a physician, a family member, or a law enforcement officer submits a report to the state DMV. The DMV then requests medical documentation, often a form completed by your neurologist or treating physician. A review board (sometimes called a medical advisory board) evaluates whether your condition is controlled enough to permit driving. Depending on the outcome, you may keep a full license, receive a restricted license (for example, limited to daylight hours or specific routes), or face a temporary suspension until your doctor clears you.
Understanding this process matters for insurance because your driving record and license status directly affect your premiums. A suspension triggered by a medical event is not the same as a suspension for reckless driving, but insurers may still see it as a lapse in coverage or a period of non-driving that needs to be explained. Keep every document from your medical review, including physician statements and DMV correspondence. These records become valuable evidence when you shop for auto insurance for drivers with epilepsy or medical conditions.
Do You Have to Disclose a Medical Condition to Your Insurer?
This is the question that keeps many drivers up at night, and the answer is more nuanced than a simple yes or no. In most states, you are not legally required to volunteer a medical diagnosis during a routine application unless the insurer asks a direct question that covers it. However, application forms often include broad questions such as whether you have any condition that impairs your ability to drive safely. Answering those questions falsely is a form of misrepresentation, and it can give the insurer grounds to deny a claim or rescind your policy after an accident.
The practical rule is this: answer every question truthfully and completely, but do not feel obligated to disclose information the insurer has not requested. If you are unsure whether your condition falls within a question's scope, ask the agent to clarify before you sign. A licensed agent who works with medically complex drivers will know how to phrase the disclosure so that it accurately reflects your situation without overstating the risk.
Disclosure does not automatically mean denial. Many insurers will issue a policy with a medical exclusion, a higher premium, or a requirement that your doctor confirm you are fit to drive. Some will simply note the condition and move on. The key is to disclose before an incident occurs, because a claim denial after a crash is far more damaging than a slightly higher premium. If you are comparing quotes, be upfront with each agent about your diagnosis and let them tell you how their carriers handle it. This transparency also protects you if the insurer later tries to argue that you withheld material information.
How a Lapse Caused by a Medical Event Affects Future Premiums
A lapse in auto insurance coverage is one of the most common consequences of a medical event, and it can follow you for years. If you have a seizure, surgery, or hospital stay that prevents you from driving for several months, you may let your policy lapse to save money. When you return to driving, insurers see that gap and often treat it as a risk factor, even if the reason was entirely medical. Premiums can increase by twenty to fifty percent after a lapse, depending on the state and the insurer.
There are ways to soften the blow. First, ask your insurer about a low-mileage or storage policy during your recovery period. Many carriers offer a reduced-premium option for vehicles that are parked and not driven, which keeps continuous coverage on your record without the full cost. Second, if you must cancel, request a letter from your physician documenting the medical reason for the lapse. Some insurers will accept this as mitigating evidence and waive the lapse penalty. Third, when you restart coverage, shop with agents who specialize in non-standard or high-risk auto insurance, because they have access to carriers that weigh medical explanations more fairly than mainstream insurers do.
It also helps to plan ahead. If your doctor advises you to stop driving for a set period, call your insurer before the policy lapses, not after. Explain the situation and ask what options exist. A short conversation can prevent a costly gap and preserve your good-driver status. Remember that auto insurance for drivers with epilepsy or medical conditions is often about documentation and communication, not just finding the cheapest quote.
Finding Licensed Agents Familiar with Medically Complex Drivers
Not every insurance agent understands the difference between a controlled seizure disorder and an uncontrolled one, or between a temporary medical suspension and a permanent revocation. That is why working with an agent who has experience in this niche can save you both money and frustration. These agents know which carriers are comfortable with medical disclosures, which ones offer storage policies, and how to present your situation in the most accurate and favorable light.
Start by asking prospective agents direct questions. How many clients do they have with epilepsy or other neurological conditions? Which carriers do they represent that have flexible underwriting for medical risks? Can they explain how a medical lapse will be treated by each carrier? A good agent will answer these questions without hesitation and will not pressure you toward a policy that does not fit. You can also check with patient advocacy groups such as the Epilepsy Foundation, which often maintain lists of insurance professionals who understand the community's needs.
When you are ready to compare options, use a service that connects you with licensed agents who can tailor quotes to your medical history. You can also explore broader savings strategies, such as combining your auto policy with renters or homeowners coverage, in our guide on auto insurance for renters and homeowners. Bundling does not erase a medical disclosure, but it can lower your overall premium and simplify your coverage. For drivers who have faced loan rejections or need vehicle financing alongside insurance, platforms like AutoTitleLoan.com can connect you with lending options, though always review the terms carefully before committing.
Practical Steps to Secure Coverage Without Overpaying
Securing affordable auto insurance for drivers with epilepsy or medical conditions is a process, not a single transaction. The drivers who succeed are the ones who prepare their documentation, communicate clearly, and compare multiple carriers before committing. Here is a sequence that works:
- Check your state DMV's medical review requirements and obtain a physician's statement confirming your fitness to drive.
- Gather your driving record, current policy documents, and any medical review paperwork so you can answer insurer questions accurately.
- Contact at least three licensed agents who have experience with medical disclosures and ask how each carrier handles your specific condition.
- Compare quotes side by side, paying attention not just to premium but to exclusions, lapse penalties, and reinstatement rules.
- Before your policy starts, confirm in writing how your condition is noted and what would happen if you need to pause coverage for a medical reason.
This preparation pays off. Drivers who disclose proactively and document their medical history often find that insurers treat them as responsible policyholders rather than high-risk applicants. The difference in premium between a well-documented medical disclosure and a hidden condition that surfaces after a claim can be thousands of dollars, not to mention the stress of a denied claim.
What to Expect When You Switch Insurers Mid-Treatment
Changing insurers while you are undergoing treatment for a medical condition adds another layer of complexity, but it is manageable. The new insurer will likely ask about your condition and may request a physician's clearance. If you are in the middle of a seizure-free waiting period required by your state, some carriers will postpone underwriting until the period ends. Others will issue a policy with a temporary exclusion that can be removed once your doctor provides an updated statement.
Timing matters. If possible, secure your new policy before canceling the old one so you avoid any gap in coverage. Ask the new agent whether the carrier will accept a letter from your neurologist in place of a formal DMV clearance, and get that answer in writing. If the new policy includes a medical exclusion, clarify exactly what it covers and what it does not. An exclusion for seizures might mean the insurer will not pay for an accident caused by a seizure, but it may still cover you for other types of incidents. Understanding these details prevents surprises later.
Finally, keep your renewal dates in mind. A medical event close to renewal can complicate the process, so start shopping at least thirty days before your current policy expires. That buffer gives you time to gather records and compare offers without pressure. With the right approach, auto insurance for drivers with epilepsy or medical conditions can be both affordable and reliable, allowing you to focus on your health and your daily driving needs.