ATV Insurance Coverage for Off Road Vehicles: What You Need
Understand atv insurance coverage for off road vehicles what you need, from liability to accessories. Call (833)-214-7506 to compare specialized quotes.
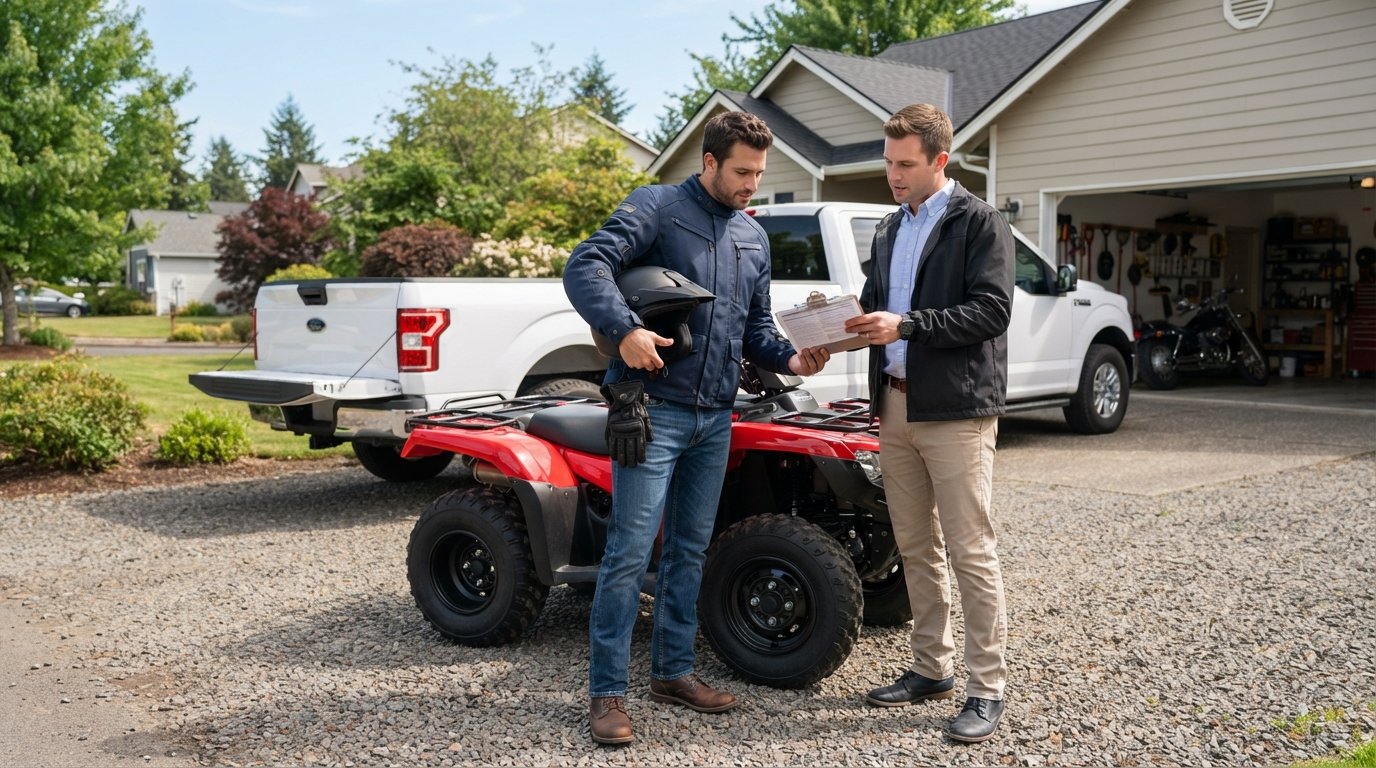
You just bought a side-by-side or a new four-wheeler, and the dealer handed you a set of keys and a bill of sale. What they probably did not hand you was a clear explanation of whether you need insurance, what it should cover, and how much it costs. That gap in information is where a lot of off-road owners get into trouble, because the rules for ATVs are not the same as the rules for cars. In many states you can legally ride without a policy until you hit a public trail system, and then suddenly proof of coverage becomes a requirement. In other states, your homeowner policy might cover a small ATV in the driveway but exclude it the moment you leave the property. Understanding atv insurance coverage for off road vehicles what you need means knowing three things: what your state requires, what your existing policies already include, and what gaps you are personally willing to carry.
Why ATV Insurance Is Different From Auto Insurance
ATVs, UTVs, side-by-sides, and dirt bikes occupy a strange middle ground in the insurance world. They are motor vehicles, but most of them are not titled or registered the way a car is. They are often stored at home, which makes people assume their homeowners policy covers them, and that assumption is only partially true. A typical homeowners policy extends liability coverage to recreational vehicles in limited situations, usually low-powered models used only on the insured property, and it almost always excludes damage to the ATV itself. The moment you trailer the machine to a trailhead or let a friend ride it on public land, that thin layer of protection often disappears.
Standalone ATV policies are built to close those gaps. They function more like motorcycle insurance than car insurance, with a narrower set of coverages and a heavier emphasis on physical damage protection because off-road machines are easy to flip, sink, or total on a rock. Insurers also price them differently, weighing engine displacement, rider age, and where you ride more heavily than they weigh annual mileage. If you are used to shopping for auto coverage, the logic will feel familiar but the details will not. A good starting point is to treat an ATV policy as its own product rather than an add-on, and then decide which pieces you actually need.
The Core Coverages You Should Understand
Most ATV policies are assembled from a small menu of coverage types, and each one answers a different question. Before you compare quotes, it helps to know what you are being quoted, because a cheap policy that skips physical damage coverage is not really cheaper, it is just narrower. The building blocks below appear on nearly every off-road policy in some form.
- Liability coverage: Pays for injuries or property damage you cause to other people while riding. This is the coverage that trail systems and state agencies usually want to see proof of.
- Collision coverage: Pays to repair or replace your ATV after a crash with another vehicle or object, regardless of fault.
- Comprehensive coverage: Pays for damage that is not a crash, including theft, fire, vandalism, hail, and falling branches.
- Accessory coverage: Protects added equipment such as winches, plows, light bars, upgraded tires, and trailers, usually up to a stated limit.
- Medical payments or personal injury protection: Helps with medical bills for you or a passenger after an accident, no matter who caused it.
Liability is the backbone of any policy because it protects your savings from a lawsuit, and it is the piece most likely to be required by law or by a landowner who lets you ride on private property. Collision and comprehensive are optional on most policies but matter enormously if your machine is financed, since lenders typically require them until the loan is paid off. Accessory coverage is easy to overlook and easy to regret: a winch and a plow can add a thousand dollars or more to the value of a machine, and a base policy will not automatically include them. When you request quotes, ask specifically whether accessories are covered and at what limit.
State Requirements: Where ATV Insurance Is Mandatory
There is no single national rule for ATV insurance, which is why the answer to "is it required" depends entirely on where you live and where you ride. A handful of states require liability coverage for ATVs registered or operated on public land, and some require it only for certain riders, such as minors or those using specific trail systems. Other states have no insurance mandate at all but still require registration and a safety certificate. A third group requires nothing for private property use, which is exactly where the homeowners policy assumption causes problems.
The practical rule is to check two authorities before you ride: your state's motor vehicle or parks department, which sets registration and insurance rules, and the land management agency that controls the trail you plan to use. Federal and state trail systems sometimes impose their own proof-of-insurance requirements even when state law does not. If you ride across state lines, which is common for owners who trailer to national forests, you may need to satisfy the rules of the state you are visiting, not just your home state. Because these rules change and vary by vehicle class, confirm the current requirement directly with the agency before your trip rather than relying on a forum post from three seasons ago.
What Actually Drives Your ATV Premium
Insurers price off-road policies using a mix of vehicle and rider factors, and understanding them lets you see why two neighbors with similar machines pay very different rates. The biggest single factor is usually engine size: a 250cc youth quad and a 1000cc side-by-side are in completely different risk categories, and the larger machine will cost more to insure because it costs more to repair or replace and is capable of more damage. Rider age matters just as much, and young riders on high-displacement machines can see premiums several times higher than an experienced adult on the same vehicle.
Location and usage also move the number. Theft rates vary widely by region, so comprehensive coverage costs more in areas where ATVs are frequently stolen. Riding on public trails, racing, or using the machine for farm or ranch work can change how an insurer classifies the policy. Your claims history and whether you have completed a recognized safety course can work in your favor. Even the storage situation matters: a machine kept in a locked garage is a better risk than one parked in an open carport. If you want a realistic sense of how insurers weigh these factors across vehicle types, the same logic shows up in other specialty policies, and our guide on rental car insurance coverage needs walks through how usage and location shape premiums in a comparable way.
Practical Ways to Lower Your ATV Insurance Cost
Off-road insurance is usually inexpensive compared with auto coverage, but there is still room to save, and the savings tend to compound when you combine them. The most reliable discount for most owners is a safety course: many insurers reduce premiums for riders who complete a certified ATV or off-road safety program, and the course itself often satisfies state certification requirements at the same time. Bundling is the second big lever. If you already insure a car, a home, or a renters policy, ask whether the company offers a multi-policy discount for adding the ATV, because the combined savings often beat shopping each policy separately.
Beyond those two, a few habits help. Raising your deductible lowers the premium, as long as you can absorb the difference if you do damage the machine. Choosing a policy that reflects actual seasonal use, rather than paying for year-round coverage on a machine that sits from November to April, can help in states where insurers offer that flexibility. Keeping safety gear, a winch, and a lock in use reduces the chance of a claim, which protects your claims history over time. Finally, compare at least three quotes before renewing, because off-road pricing varies more between insurers than auto pricing does, and the cheapest option in year one is not always the cheapest after a claim.
How to Shop for Coverage Without Overpaying
Buying ATV insurance is a short process if you prepare the right information. You will need the vehicle identification number, engine size, model year, any accessories you want covered, the address where the machine is stored, and the ages and driving records of everyone who will ride it. With those details in hand, you can request quotes in a single sitting rather than gathering paperwork three times. The sequence below keeps the comparison clean and makes it harder for an agent to leave out a coverage you assumed was included.
- Confirm your state and trail requirements so you know the minimum liability limit you must carry.
- Check your homeowners or renters policy to see whether it already covers the ATV, and under what conditions it stops covering it.
- Decide whether you need collision and comprehensive based on the machine's value and whether it is financed.
- Request quotes from multiple insurers using identical coverage limits and deductibles so the comparison is fair.
- Ask each agent to confirm accessory coverage limits, trailer coverage, and whether passengers are protected.
That last step matters more than most buyers expect. Two policies with the same headline price can differ significantly in whether they cover a passenger, a plow, or a trailer, and those differences only surface when you file a claim. If you want a broader view of how specialty vehicle policies fit into a household's overall insurance plan, the same comparison discipline applies across vehicle types, and platforms that focus on vehicle loan and insurance planning can help you think through the financing and coverage decisions together rather than in isolation.
Common Mistakes That Leave Riders Unprotected
The most expensive ATV insurance mistake is assuming coverage exists when it does not. Homeowners policies are the usual source of that confusion, because they do extend some liability protection to recreational vehicles, but the exclusions are broad: business use, racing, riding on public roads, and damage to the vehicle itself are typically outside the policy. Owners discover this after an accident, when the claim is denied and the repair bill lands on their own budget. A second common mistake is underinsuring accessories, which are frequently worth more than the base machine after a few seasons of upgrades.
Another frequent problem is letting a friend or family member ride without checking whether the policy covers other operators. Some policies cover any licensed operator with permission, while others list named riders only, and a claim involving an unlisted rider can be denied outright. Finally, many owners skip liability coverage entirely because their state does not mandate it, then find themselves personally responsible for injuries they cause on a crowded trail. Liability is inexpensive relative to the protection it provides, and it is the one coverage that protects your assets rather than just your machine.
Getting the right ATV policy comes down to matching three things: your state and trail requirements, the real value of your machine and its accessories, and the level of risk you are willing to carry yourself. Start by checking what your existing policies already cover, then fill the gaps with a standalone off-road policy that includes liability and, if the machine is financed or valuable, physical damage coverage. Compare quotes using identical limits, confirm the accessory and passenger details in writing, and revisit the policy each year before renewal. NewAutoInsurance.com is an independent educational resource, not an insurance carrier or broker, and it can connect you with licensed agents who specialize in off-road vehicles so you can compare real quotes and choose the coverage that fits how you actually ride.