Why Car Insurance Rates Are Rising in 2026
Car insurance rates are rising due to repair costs, inflation, and severe weather. Compare quotes to pressure insurers and avoid surprise bills.
By Emily Roberts
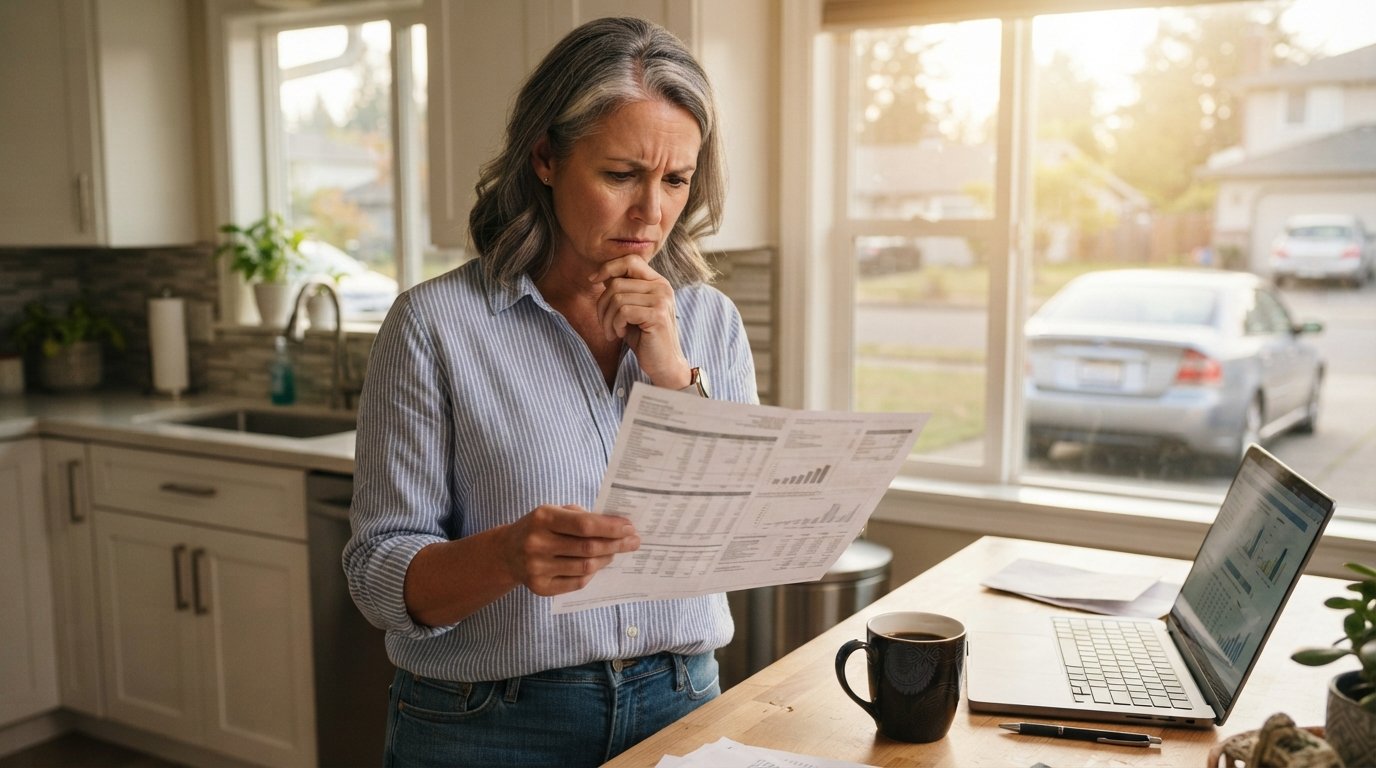
If your auto insurance renewal quote arrived with a higher number than last year, you are not imagining it. Across the United States, drivers are opening bills that have jumped by double digits, and in some states the increase has been steep enough to force real changes in household budgets. The reasons behind this trend are not mysterious, but they are layered: they involve inflation, repair costs, legal settlements, weather patterns, and the simple economics of risk. Understanding what is driving the increases can help you respond strategically, rather than simply accepting the new number as inevitable.
This article breaks down the main forces pushing premiums upward, explains how those forces interact, and offers practical steps you can take to keep your own costs as low as possible. Whether you drive a standard sedan, a commercial vehicle, or a classic car, the same broad pressures apply, though they may hit different vehicle categories at different intensities. By the end, you should have a clear picture of the landscape and a set of actions you can take immediately.
The Post-Pandemic Repair Cost Shock
One of the most powerful drivers of rising auto insurance rates is the cost of repairing a vehicle after an accident. Between 2020 and 2024, the price of new and used cars surged, and the cost of parts and labor followed. Supply chain disruptions made certain components scarce, and when parts are scarce, their prices rise. Simultaneously, modern vehicles have become more complex. A minor fender bender that once required a simple bumper replacement may now involve sensors, cameras, radar units, and calibration procedures that add hundreds or even thousands of dollars to the repair bill.
Insurance companies pay for these repairs, and when their costs go up, they pass those costs to policyholders in the form of higher premiums. The effect is not uniform across all vehicles. A basic economy car with few advanced driver assistance systems may still be relatively cheap to repair, while a luxury vehicle or a newer model with extensive electronics can be dramatically more expensive. This is one reason why the same driver with the same record can see very different rate increases depending on the vehicle they drive.
Another factor is the rising cost of labor. Skilled auto body technicians are in short supply, and their wages have risen. Shops also face higher costs for equipment, paint, and compliance with environmental regulations. All of these expenses flow into the repair invoice, and ultimately into the premium you pay. Even if you are a safe driver, you share in the collective cost of repairing vehicles in your rating territory.
Inflation and the Rising Cost of Claims
Inflation affects auto insurance in two directions. First, it raises the cost of the goods and services that insurers must pay for when a claim occurs. Second, it raises the cost of medical care for injuries sustained in accidents. Both bodily injury and property damage liability claims have become more expensive. Medical inflation has outpaced general inflation for years, and when an accident results in injuries, the bills can be enormous. Insurers must set aside reserves to cover these costs, and those reserves are funded by premiums.
Litigation trends also play a role. In some states, attorneys are more aggressively pursuing claims, and juries have awarded larger settlements. This increases the average cost of a bodily injury claim, which in turn pushes up rates for everyone in that state. The effect is especially pronounced in urban areas where accident frequency and severity are higher. Even drivers with clean records in those areas may see increases because the overall risk pool has become more expensive to insure.
It is worth noting that insurance is a regulated industry, and rate increases must typically be approved by state insurance departments. When you see a rate hike, it often reflects a filing that the insurer made months earlier, supported by data showing that claims costs have risen. The approval process can delay the impact, but it does not prevent it. In a high-inflation environment, rate filings become more frequent and more substantial.
Severe Weather and Climate-Related Losses
Weather-related claims have become a major driver of auto insurance costs, particularly in states prone to hurricanes, hailstorms, wildfires, and flooding. Comprehensive coverage, which pays for damage from these events, has seen a sharp increase in claim frequency and severity. A single hailstorm can damage thousands of vehicles in a matter of minutes, and the resulting repair bills can be staggering. Unlike collision claims, which are tied to driver behavior, weather claims are largely unavoidable and can affect entire regions at once.
Insurers use complex models to predict weather-related losses, and as climate patterns shift, those models are being updated. In some coastal areas, insurers have reduced their exposure or withdrawn entirely, leaving state-backed residual markets to pick up the slack. These residual markets often charge higher premiums because they cover higher-risk drivers and properties. Even if you do not live in a high-risk area, you may see rate increases if your insurer operates in multiple states and needs to recoup losses from a catastrophe in another region.
The rise in weather-related claims is not limited to traditional disaster zones. Hail and windstorms can strike inland areas, and flooding can occur far from coastlines. As a result, more drivers are finding that their comprehensive coverage premiums are rising, even if they have never filed a weather-related claim. This is a systemic issue, not a reflection of individual driving records.
Supply Chain Issues and Parts Shortages
The global supply chain has not fully normalized after the disruptions of the early 2020s. Semiconductor shortages, shipping delays, and geopolitical tensions continue to affect the availability of auto parts. When parts are hard to get, repair times lengthen, and the cost of rental cars and substitute transportation rises. Insurers often cover rental reimbursement as part of a claim, so longer repair times directly increase claim costs.
In addition, the increased use of advanced materials in vehicle construction, such as high-strength steel and aluminum, has made repairs more challenging. These materials require specialized tools and training, and they cannot always be repaired in the same way as traditional steel. In some cases, parts must be replaced rather than repaired, which adds to the cost. The net effect is that even a modest accident can result in a bill that would have been unthinkable a decade ago.
For drivers of specialized vehicles, such as commercial trucks, RVs, or antique cars, the parts challenge can be even more acute. Parts for older or less common vehicles may be scarce, and sourcing them can take weeks or months. This increases the cost of claims and can lead to higher premiums for those vehicle categories. If you own a specialized vehicle, it is worth understanding how these dynamics affect your rates and what steps you can take to mitigate them.
Distracted Driving and Accident Frequency
Despite improvements in vehicle safety technology, accident frequency has not declined as much as many hoped. Distracted driving, particularly smartphone use behind the wheel, remains a significant problem. When drivers take their eyes off the road, even for a moment, the risk of a crash rises sharply. The resulting claims add to the overall cost pool and contribute to rate increases.
At the same time, traffic volumes have returned to pre-pandemic levels in many areas, and in some cases they have exceeded them. More miles driven means more opportunities for accidents. The combination of higher traffic density and distracted driving has kept claim frequency elevated, even as vehicles become safer in other respects. Insurers look at these trends when setting rates, and they adjust premiums to reflect the elevated risk.
It is also worth noting that the severity of accidents has increased. Higher speeds, heavier vehicles, and more complex repair requirements mean that when a crash does occur, it is more likely to result in serious injuries and expensive repairs. This severity trend is a major factor in the rate increases that many drivers are experiencing.
Regulatory and Legal Environment
State regulations play a significant role in auto insurance rates. Some states have stricter rate filing requirements, while others allow insurers more flexibility. In states where the legal environment is favorable to large jury awards, insurers must charge more to cover potential losses. Similarly, states with no-fault systems or mandatory personal injury protection (PIP) can have different cost structures than tort states.
Recent legislative changes in some states have also affected rates. For example, changes to uninsured motorist laws or the introduction of new mandates can increase costs. Insurers must comply with these laws, and the costs are ultimately borne by policyholders. If you live in a state with a high-risk environment, your rates may be higher than those in neighboring states with more favorable conditions.
It is important to understand that rate increases are not arbitrary. They are the result of a complex interplay of factors, many of which are outside the control of any individual driver. However, that does not mean you are powerless. By understanding the drivers of rate increases, you can take steps to position yourself more favorably and potentially reduce your own premium.
What You Can Do to Manage Rising Rates
While you cannot control the broader market forces, you can control several factors that affect your individual premium. The first step is to shop around regularly. Insurers use different rating models, and the company that offered you the best rate two years ago may no longer be competitive. Getting quotes from multiple carriers can reveal significant savings.
You can also review your coverage options. If your vehicle is older and has a lower market value, you might consider dropping collision and comprehensive coverage, provided you have enough savings to cover repairs or replacement out of pocket. Increasing your deductible can also lower your premium, though you should ensure you can afford the higher out-of-pocket cost if you have a claim.
Here are some practical steps to consider:
- Shop around and compare quotes from at least three insurers. Rates can vary widely for the same driver and vehicle.
- Ask about discounts for safe driving, low mileage, bundling auto with home or renters insurance, and paying in full.
- Improve your credit score if you live in a state where credit-based insurance scores are used. A better score can lead to lower rates.
- Consider usage-based insurance if you drive fewer miles or drive safely. These programs can offer significant savings.
- Review your coverage limits and adjust them to match your actual risk and assets.
For drivers with a history of violations or accidents, the options may be more limited. In our guide on navigating high-risk car insurance rates, we explain how to find coverage even when your record makes you a higher-risk applicant. The key is to be persistent and to work with an independent agent or comparison tool that can access multiple markets.
Another strategy is to bundle your auto insurance with other policies, such as homeowners or renters insurance. Bundling can often produce a meaningful discount, and it simplifies your insurance management. However, it is important to compare the bundled rate against separate policies to ensure you are actually saving money.
Finally, consider working with a licensed insurance agent who can help you understand your options and find the best combination of price and coverage. A good agent can identify discounts you may have missed and help you structure your policy to avoid gaps. If you are looking for free, no-obligation quotes from multiple carriers, you can use FreeAutoInsuranceQuotesOnline to compare offers and potentially lower your premium.
The Road Ahead
Auto insurance rates are likely to remain under pressure for the foreseeable future. The underlying cost drivers, including repair costs, medical inflation, and weather-related losses, are not going away. However, the market is cyclical, and rate increases may moderate if claims costs stabilize. In the meantime, the best approach is to stay informed, review your coverage annually, and take advantage of every legitimate discount and savings opportunity.
By understanding why car insurance rates are rising, you can make more informed decisions and avoid overpaying. Whether you choose to adjust your deductible, switch insurers, or bundle policies, there are concrete actions you can take to protect your budget. The goal is not to eliminate risk, but to manage it in a way that is both affordable and responsible.