Travel Trailer Insurance Coverage and Costs Explained
Understand travel trailer insurance coverage and costs before you tow. Call (833)-214-7506 to compare personalized quotes and avoid coverage gaps.
By Ezra Whitlock
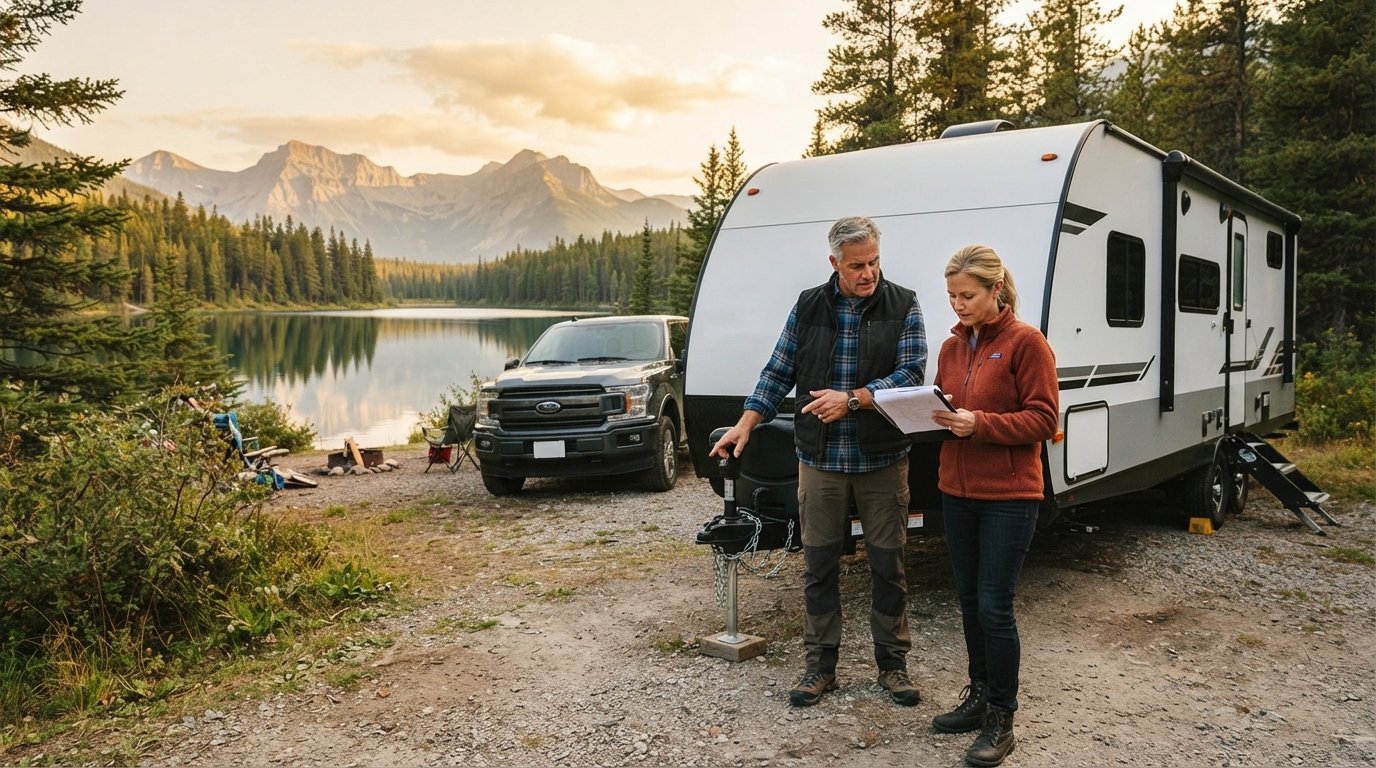
Your travel trailer opens up weekends at the lake, cross-country road trips, and a comfortable base camp wherever you park it. But that freedom comes with financial exposure that your standard auto policy may not fully address. Understanding travel trailer insurance coverage and costs is the difference between a minor fender bender that is fully covered and a totaled camper that drains your savings. Whether you are towing a small pop-up or a 35-foot bunkhouse model, the right policy protects your investment, your liability, and your peace of mind.
Many owners assume their car insurance automatically extends to a trailer. Sometimes it does, but only partially, and the gaps can be costly. This guide breaks down how travel trailer insurance actually works, what it covers, what drives your premium up or down, and how to compare quotes without overpaying. The goal is simple: help you make an informed decision before you hitch up and hit the road.
How Travel Trailer Insurance Works With Your Auto Policy
The first thing to understand is that travel trailer insurance is rarely a standalone product. In most cases, it is an extension of your existing auto insurance policy. When you tow a travel trailer, your liability coverage from the towing vehicle typically extends to the trailer while it is attached. That means if you cause an accident while towing, your auto liability limits may respond. However, that extension comes with limits, and it usually does not cover the trailer itself for physical damage.
This is where the distinction matters. Liability coverage pays for injuries or property damage you cause to others. It does not pay to repair or replace your own trailer. To protect the trailer itself, you need physical damage coverage, which is typically added as a rider or endorsement to your auto policy. Some insurers offer a dedicated travel trailer policy, but even then, it is often bundled with your auto coverage for simplicity and savings.
If you are a homeowner or renter, your existing property policy may also offer limited coverage for a travel trailer, but those limits are usually low and may not apply while the trailer is in transit. Relying on homeowners insurance alone is risky. A dedicated endorsement or a standalone travel trailer policy closes those gaps. For a broader look at how auto coverage interacts with property policies, see our guide on renters and homeowners auto insurance coverage fit.
Coverage Types for Travel Trailers: Liability, Collision, and Contents
Travel trailer insurance coverage is not a single product. It is a set of protections that you can mix and match based on your trailer's value, how you use it, and your risk tolerance. The core coverage types fall into three categories: liability, collision, and contents. Understanding each one helps you avoid paying for coverage you do not need while ensuring you are not exposed to a major loss.
Liability coverage is the foundation. It pays for bodily injury and property damage you cause to others while towing or using your trailer. This includes accidents on the road and incidents at a campsite, such as your trailer's awning damaging a neighbor's vehicle. Liability limits are typically expressed as split limits (for example, $100,000 per person and $300,000 per accident) or a combined single limit. Higher limits cost more but protect your assets if you are sued after a serious accident.
Collision coverage pays to repair or replace your travel trailer if it is damaged in an accident with another vehicle or object, regardless of fault. This includes rollovers, jackknifes, and collisions with guardrails. Collision coverage is usually subject to a deductible, which is the amount you pay out of pocket before insurance kicks in. A higher deductible lowers your premium but increases your financial responsibility at claim time.
Contents coverage protects the personal property inside your trailer, such as clothing, cookware, electronics, and camping gear. It may also cover items attached to the trailer, like awnings and stabilizer jacks. Contents coverage often comes with a limit, and high-value items like jewelry or expensive fishing gear may need a scheduled endorsement. If you use your trailer as a second home, contents coverage becomes even more important.
Beyond these three, you may also consider comprehensive coverage, which pays for damage from non-collision events like fire, theft, vandalism, hail, or falling trees. Comprehensive coverage is often required by lenders if you finance your trailer. Additionally, emergency roadside assistance and vacation liability coverage are optional add-ons that can be valuable for frequent travelers. Vacation liability coverage protects you if someone is injured while your trailer is parked and used as a temporary residence.
Factors That Influence Travel Trailer Insurance Rates
Travel trailer insurance costs vary widely based on several factors. Insurers assess risk differently, so the same trailer might cost $300 per year with one company and $700 with another. Knowing what drives your premium helps you shop smarter and identify potential discounts.
The type and value of your trailer is the biggest factor. A small, lightweight pop-up costs far less to insure than a luxury fifth-wheel with a generator, solar panels, and premium finishes. Insurers consider the trailer's age, purchase price, and replacement cost. Newer, more expensive trailers cost more to insure because repairs and replacements are pricier. Customizations and modifications can also increase your premium unless you document them and add them to your policy.
Your towing vehicle and driving history also matter. If you tow with a heavy-duty truck that has a strong safety rating, you may qualify for lower rates. Conversely, a history of accidents, tickets, or claims will raise your premium. Some insurers offer discounts for safe drivers, defensive driving courses, and bundling your auto and trailer coverage. Where you store your trailer when not in use is another factor. Storing it in a secure garage or fenced lot reduces theft and weather risk, which can lower your rate compared to storing it outdoors on the street.
Usage patterns play a role as well. Full-time travelers who live in their trailers may pay more than weekend campers because they face more exposure. Similarly, if you use your trailer for business purposes, such as a mobile office or rental, you need a commercial policy, which costs more. Finally, your location matters. States with high insurance rates, frequent natural disasters, or high theft rates will have higher premiums. Rural areas often have lower rates than urban areas.
To give you a sense of the range, basic liability and collision coverage for a travel trailer might cost $200 to $500 per year, while comprehensive coverage and higher limits can push the annual premium to $800 or more. Full-time RV coverage or policies for high-value trailers can exceed $1,500 per year. These are general estimates; your actual cost depends on your specific situation.
Comparing Travel Trailer Insurance Quotes
Comparing quotes is the most effective way to control your travel trailer insurance costs. Insurers use different rating formulas, so loyalty to a single company may cost you hundreds of dollars per year. The process is straightforward if you gather the right information and ask the right questions.
Start by collecting your trailer's details: make, model, year, VIN, purchase price, and any modifications. You will also need your towing vehicle's information and your driving history. Then, request quotes from multiple insurers. You can do this through an independent agent or a comparison platform that connects you with licensed agents. NewAutoInsurance.com is an independent resource that can connect you with agents who offer personalized quotes for travel trailer insurance and other specialized vehicle coverage.
When comparing quotes, do not focus only on price. Look at the coverage limits, deductibles, and exclusions. A cheaper policy with low liability limits may leave you underinsured. Ask each insurer the following questions:
- Does the policy cover the trailer while it is being towed, or only when parked?
- What is the deductible for collision and comprehensive claims?
- Are contents covered, and what is the limit?
- Is there vacation liability coverage, and what are the limits?
- Are there discounts for bundling with my auto or home policy?
- How are claims handled, and is there a 24/7 claims hotline?
After you gather quotes, compare them side by side. Pay attention to the total annual cost, not just the monthly payment. Also, consider the insurer's reputation for customer service and claims handling. A slightly higher premium from a reliable insurer may be worth it if you ever need to file a claim. Finally, ask about bundling discounts. Many insurers offer significant savings when you combine your auto, home, and travel trailer policies. If you are financing your trailer, your lender may have specific coverage requirements, so confirm those before you buy.
Remember that travel trailer insurance coverage and costs are not one-size-fits-all. The best policy for you depends on how you use your trailer, your budget, and your risk tolerance. Take the time to compare at least three quotes and ask questions. A few hours of research can save you hundreds of dollars and ensure you have the protection you need when you are on the road.
If you are also managing other vehicle loans, keeping your overall financial picture in mind is wise. For tips on optimizing auto loans, you can explore resources at CarLoanRefinancing.
Ultimately, insuring your travel trailer is about matching coverage to your actual risk. Whether you are a weekend warrior or a full-time nomad, the right policy lets you enjoy the journey without worrying about what happens if something goes wrong. Use the information here to ask better questions, compare quotes confidently, and choose a policy that protects your home away from home.