RV Insurance Protection for Motorhomes: Coverage Guide
RV insurance protection for motorhomes blends auto liability with property coverage. Compare policies to avoid gaps and protect your coach.
By Nyla Kensington
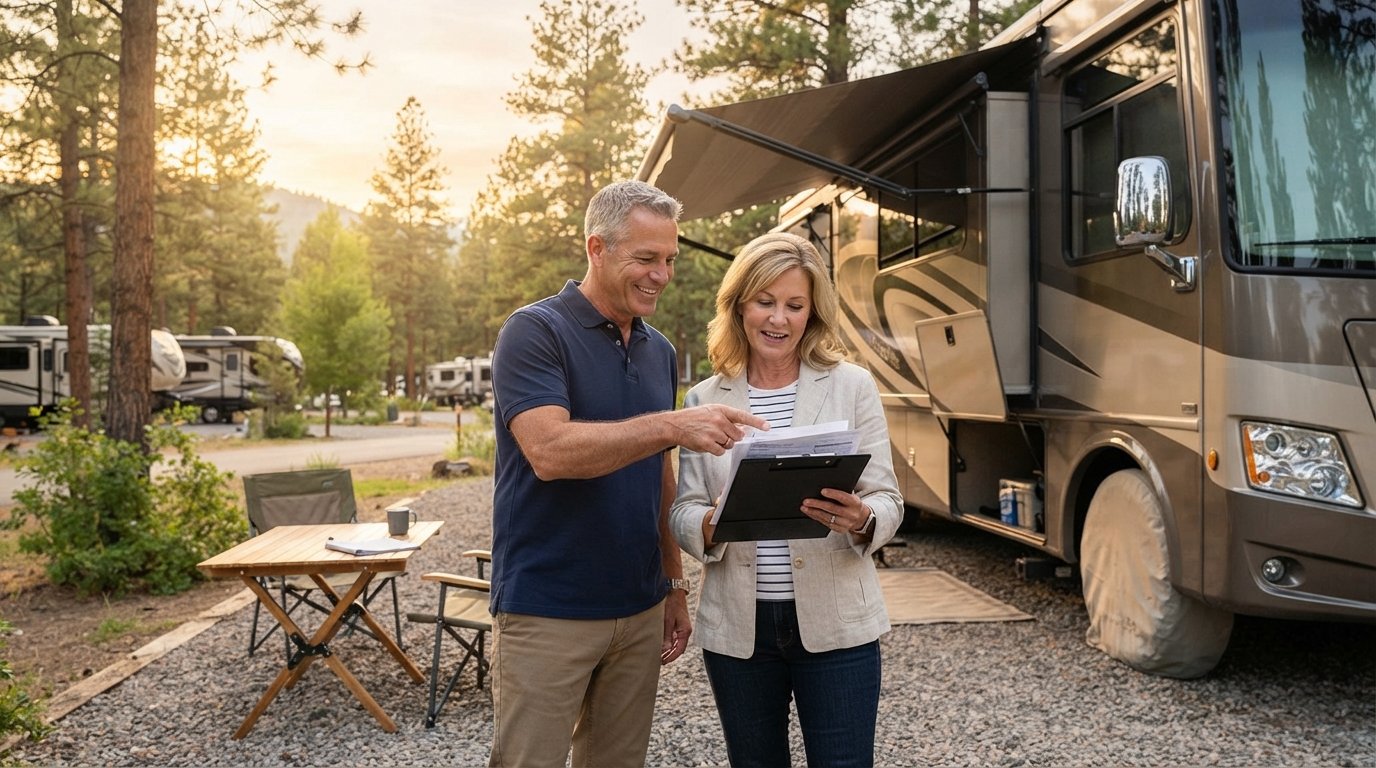
A motorhome is not just a vehicle. It is a house on wheels, a vacation investment, and sometimes a full-time residence. When you combine a drivable chassis with plumbing, appliances, electronics, and personal belongings, you create a property that standard auto policies were never designed to handle. That is why rv insurance protection for motorhomes exists as its own specialized category of coverage, blending the liability features of a car policy with the property protections of a homeowners policy. Understanding how these pieces fit together can mean the difference between a minor claims headache and a financial disaster after an accident, a storm, or a theft.
This guide walks through the coverage types that matter most for motorhome owners, the situations where gaps commonly appear, and the practical steps you can take to compare policies with confidence. Whether you drive a Class A diesel pusher, a Class C mini motorhome, or a camper van conversion, the principles are similar, though the limits and endorsements will vary. You will also see how to gather quotes from multiple carriers and how tools like an auto insurance protection options guide can help you frame the right questions before you call an agent.
Why Motorhomes Need Specialized Coverage
A typical auto policy assumes your vehicle is transportation. A motorhome is transportation plus a temporary or permanent dwelling. That dual nature creates exposures a standard policy does not address. If a pipe bursts and ruins your cabinetry, a regular auto policy will not pay. If a guest trips on your steps and breaks an arm, you may need liability protection that extends beyond driving. If your onboard generator is stolen while you are parked at a campsite, you need contents coverage that follows the vehicle.
Specialized RV policies solve this by combining several protection types into one contract. The liability section handles bodily injury and property damage you cause to others, whether you are driving or parked. The physical damage section covers the motorhome itself against collision, fire, theft, and weather. The contents section covers personal property inside the coach. Many policies also add vacation liability, which protects you when you are using the RV as a temporary residence and someone is injured on or around it.
Another reason specialization matters is valuation. Motorhomes depreciate differently than cars, and some models hold value well or even appreciate if they are rare or well maintained. Agreed value or replacement cost coverage can be important for newer coaches, while actual cash value may be acceptable for older units. Getting this wrong can leave you with a settlement that does not cover a comparable replacement.
Core Coverages in an RV Policy
Most motorhome policies are built from a set of standard components. The exact names vary by carrier, but the functions are consistent. Reviewing each one helps you spot where you may need higher limits or an add-on endorsement.
Here are the main coverage categories you will typically see:
- Bodily injury and property damage liability: Pays for injuries or property damage you cause to others in an at-fault accident.
- Collision: Covers damage to your motorhome from a collision with another vehicle or object.
- Comprehensive: Covers theft, fire, vandalism, hail, flooding, and other non-collision events.
- Contents and personal property: Protects belongings inside the RV, such as electronics, clothing, and camping gear.
- Vacation liability: Provides liability protection when the RV is parked and used as a residence.
- Roadside assistance and towing: Handles flat tires, battery jumps, fuel delivery, and towing to a repair facility.
Beyond these basics, you may see endorsements for full-timer coverage, which is designed for people who live in their motorhome year round and have no fixed home base. Full-timer policies often add personal liability and medical payments coverage that a standard policy lacks. There are also options for custom equipment, awnings, satellite dishes, and solar panels, which may need to be scheduled separately if their value is high.
Deductibles work much like they do on a car policy. You choose an amount, and you pay that out of pocket before the insurer pays a claim. A higher deductible lowers your premium, but it also means more financial exposure when something goes wrong. Many owners choose a moderate deductible for collision and a lower one for comprehensive, since glass and storm claims are common and relatively inexpensive.
How RV Coverage Differs From Standard Auto Insurance
It is tempting to assume your existing auto policy will simply extend to a motorhome. Sometimes it can, especially for smaller Class B vans, but the coverage is usually inadequate for a larger coach. Standard auto policies typically exclude or limit coverage for living quarters, built-in appliances, and personal belongings. They also may not include vacation liability, which is critical when you are parked and using the RV as a dwelling.
Another difference is the claims process. RV claims often involve two types of adjusters: one for the vehicle portion and one for the property portion. A specialized policy is written to handle both under one claim, which reduces the back-and-forth and the chance that each side blames the other. This matters most after a major event like a fire or a rollover, where the structure and the chassis are both damaged.
Pricing also reflects the differences. Motorhome policies are usually more expensive than car policies because the vehicle is worth more and the liability exposure is higher. However, many carriers offer discounts for safe driving, storing the RV during off-season, belonging to an RV association, or bundling with a homeowners policy. Comparing quotes across several carriers is the most reliable way to find a fair price.
Common Gaps and Mistakes to Avoid
Even owners who buy a specialized policy can end up underinsured if they do not review the details. One frequent mistake is choosing actual cash value when the motorhome is newer and still financed. If the coach is totaled, the settlement may be far less than the loan balance, leaving you to pay the difference. Agreed value or replacement cost coverage avoids that problem, though it costs more.
Another gap involves personal belongings. Some policies cap contents coverage at a relatively low amount, such as $1,000 or $2,000. If you travel with expensive cameras, laptops, or sporting equipment, that limit may not be enough. You can often raise it with an endorsement or schedule specific items. Similarly, custom modifications like wheelchair lifts, upgraded suspension, or solar arrays may not be covered unless you document them and add them to the policy.
Full-timers face a unique set of gaps. If you live in your motorhome and do not own a home, you may not have the personal liability coverage that a homeowners policy would normally provide. A full-timer endorsement or a standalone policy is essential. Without it, you could be personally responsible for an injury that occurs at your campsite or in your coach.
Finally, many owners forget to update their policy after a move, a major upgrade, or a change in usage. If you start using your RV for business purposes, such as renting it out or using it as a mobile office, your personal policy may not respond to claims. Notify your insurer or agent whenever your usage changes.
Steps to Compare RV Insurance Quotes
Getting the right coverage starts with preparation. Before you contact carriers or use a comparison platform, gather the details that determine your rate and eligibility. This will speed up the process and help you compare apples to apples.
Follow these steps to organize your search:
- Write down the motorhome's year, make, model, length, and current value.
- Decide whether you want actual cash value, agreed value, or replacement cost coverage.
- List your personal belongings and estimate their total value.
- Determine how you use the RV: occasional trips, seasonal travel, or full-time living.
- Collect your driving records and any RV association memberships that may qualify for discounts.
- Request quotes from at least three carriers or use a platform that connects you with licensed agents.
When you review quotes, do not look only at the premium. Compare the liability limits, deductible amounts, contents coverage, and whether vacation liability is included. Ask about exclusions for full-timing, business use, and custom equipment. A slightly higher premium with better limits can save you thousands after a claim.
It also helps to ask about the claims process. Some carriers have dedicated RV claims teams, while others route RV claims through their auto division. A dedicated team often understands the nuances of motorhome repairs and total loss valuations. If you are unsure where to start, a service like FreeAutoInsuranceQuotesOnline can help you request no-obligation quotes from multiple carriers so you can see how rates and coverage options compare side by side.
Ways to Lower Your RV Insurance Premium
Motorhome insurance can be a significant line item in your travel budget, but there are legitimate ways to reduce it without gutting your protection. The key is to target discounts and coverage choices that match your actual risk profile.
Common savings strategies include:
- Raise your deductible: A higher deductible lowers your premium, but make sure you can cover it if a claim occurs.
- Bundle policies: Combining your RV and auto or homeowners coverage with one carrier often unlocks a multi-policy discount.
- Store seasonally: If you do not use your RV year round, ask about a storage or lay-up period that reduces coverage and cost.
- Join an RV association: Some organizations have partnerships that qualify members for discounts.
- Maintain a clean driving record: Safe driving is one of the most reliable ways to keep premiums low.
- Pay annually: Paying your premium in full instead of monthly can avoid installment fees and sometimes earn a discount.
Be cautious about cutting liability limits to save money. Liability claims can far exceed the value of the motorhome itself, and a serious accident could put your personal assets at risk. It is usually wiser to raise your deductible or trim optional coverages than to reduce liability protection below a comfortable level.
Special Considerations for Full-Timers and Part-Timers
How you use your motorhome changes the coverage you need. Part-timers who take occasional trips can often rely on a standard RV policy plus a homeowners or renters policy for personal liability. Full-timers who live in the RV for most or all of the year need a policy designed for that lifestyle, because their homeowners or renters coverage may not extend to the RV as a residence.
Full-timer policies typically include personal liability, medical payments, and loss assessment coverage, which can pay for assessments levied by a campground or homeowners association. They may also include coverage for a storage unit or a small amount of coverage for a mailing address. If you work from your RV, check whether business equipment and liability are covered, since many personal policies exclude business use.
Part-timers should still review their homeowners policy to confirm how it interacts with the RV. Some policies provide liability coverage when you are using the RV as a residence, but others exclude it. A quick call to your agent can clarify the boundaries and help you avoid a gap.
Filing a Claim: What to Expect
When something goes wrong, the claims process can feel overwhelming, especially if you are far from home. Knowing the general steps can help you respond quickly and document the damage properly.
Most claims follow a similar path:
- Ensure everyone is safe and call emergency services if needed.
- Document the damage with photos and notes as soon as it is safe to do so.
- Contact your insurer or agent to report the claim and get a claim number.
- Provide any police or incident reports and cooperate with the adjuster.
- Get repair estimates from approved facilities and keep receipts for temporary lodging or transportation if your policy covers them.
Be honest and thorough when describing what happened. Adjusters are trained to spot inconsistencies, and a clear, accurate account speeds up the process. If the claim involves both the vehicle and the living quarters, ask whether one adjuster will handle both or whether you need to coordinate with two. Keeping a single point of contact can reduce confusion.
If you disagree with a settlement, you have the right to ask for an explanation and, in some cases, to request a second opinion or appraisal. Your policy documents outline the dispute resolution process, so review them before you accept a final offer.
Final Thoughts on Protecting Your Motorhome
RV insurance protection for motorhomes is not a one-size-fits-all product. The right policy depends on the type of coach you own, how you use it, and how much financial risk you are willing to carry. By understanding the core coverages, recognizing common gaps, and comparing quotes from multiple carriers, you can build a policy that protects both your vehicle and your lifestyle. Take the time to review your options each year, especially before a long trip or a change in usage. A few hours of research now can prevent a financial setback later, leaving you free to enjoy the road ahead.