Rideshare and Delivery Driver Insurance Coverage Guide
This rideshare and delivery driver insurance coverage guide explains platform gaps, endorsements, and how to avoid surprise bills. Call 8332147506 for help.
By Sebastian Rowe Sebastian Rowe
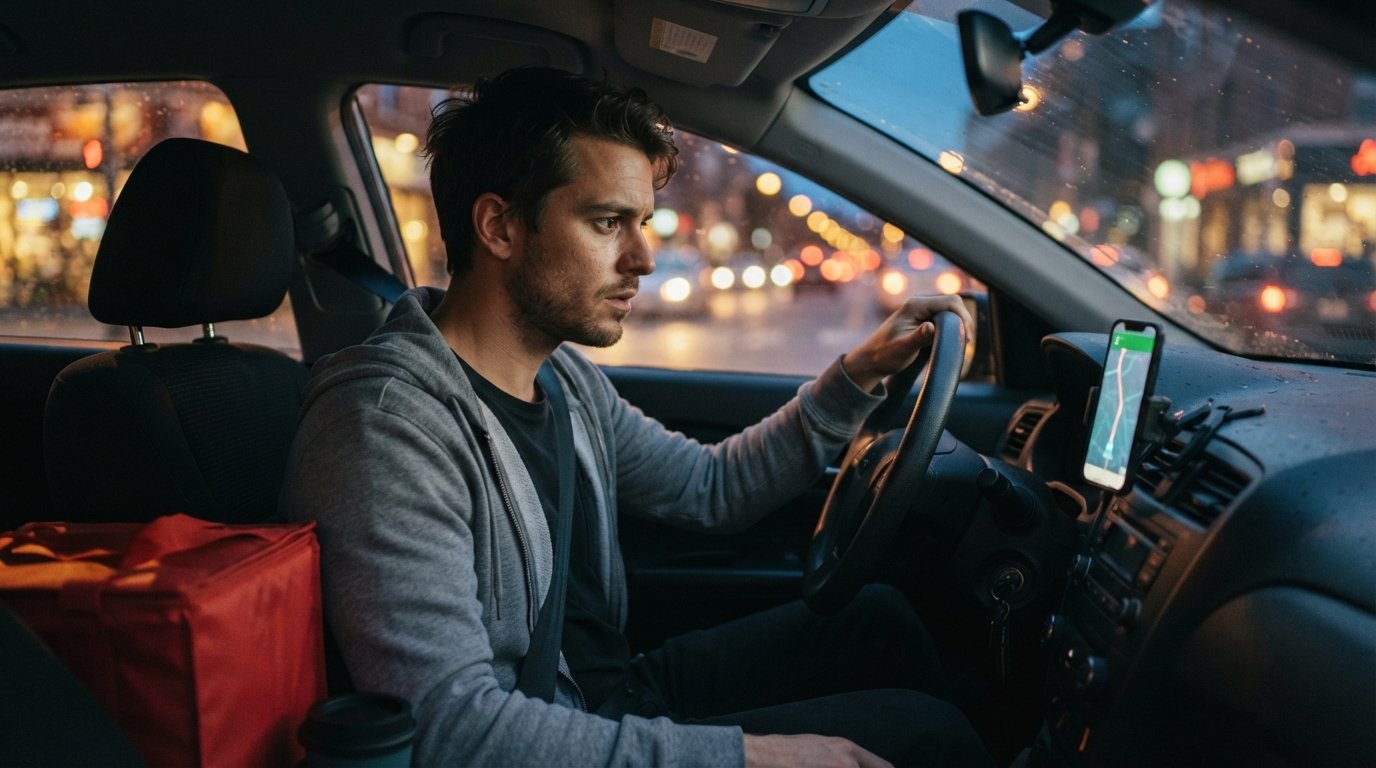
You just accepted a delivery request on your phone, and a thought flashes through your mind: if something goes wrong on this trip, does my personal auto policy actually protect me? For millions of rideshare and delivery drivers across the United States, that question carries real financial weight. A minor fender bender during a fare or a food run can turn into thousands of dollars in out-of-pocket costs if your coverage gap is exposed at the worst possible moment.
This rideshare and delivery driver insurance coverage guide walks through how coverage works when you drive for platforms like Uber, Lyft, DoorDash, Instacart, or Amazon Flex. You will learn where the gaps hide, what the platforms actually pay for, and how to structure your own policy so a single incident does not wipe out months of earnings.
Understanding the difference between personal, commercial, and platform-provided coverage is the foundation. Once you see how those layers interact, you can make smarter decisions about your policy, your endorsements, and your budget.
Why Personal Auto Policies Leave Rideshare and Delivery Drivers Exposed
Standard personal auto insurance is built for commuting, errands, and occasional road trips. It is not designed for vehicles used to generate income. Most personal policies include a clause that excludes coverage for livery or business use, which means any trip you accept through a platform can fall outside your protection.
Insurers classify driving into three broad periods: personal use, app-on but waiting for a request, and actively engaged in a delivery or passenger trip. Personal policies typically cover the first period only. The moment you toggle on and start accepting requests, you enter a gray zone that most personal carriers treat as either excluded or heavily restricted.
This is why so many drivers discover the gap only after a claim. If you are researching how different policy structures interact, our guide on bundling auto insurance for renters and homeowners explains how combining policies can close coverage gaps and reduce premiums at the same time.
Some insurers now offer rideshare endorsements that extend personal coverage into the app-on period for an additional premium. These endorsements vary widely by state and carrier, so it is important to confirm exactly what is included before assuming you are protected.
How Platform-Provided Coverage Actually Works
Uber, Lyft, DoorDash, and similar platforms do provide some coverage, but it is not a substitute for a personal policy with the right endorsements. The coverage is contingent, meaning it only activates when certain conditions are met, and it typically sits behind your own insurance in the claims hierarchy.
For rideshare platforms, coverage generally follows this structure:
- Period 1 (app on, waiting for a request): Limited liability coverage, often matching state minimums, with no collision or comprehensive protection for your vehicle.
- Period 2 (request accepted, en route to pickup): Higher liability limits, but collision and comprehensive may still require your personal policy to respond first.
- Period 3 (passenger in the vehicle): The platform's full commercial liability coverage applies, often up to $1 million, plus contingent collision and comprehensive if you carry those on your personal policy.
Delivery platforms follow a similar but often more limited framework. Many delivery apps only provide coverage during active deliveries, leaving the waiting period entirely on your personal policy. Some platforms offer optional occupational accident insurance, but that is not the same as auto liability coverage.
The critical takeaway is that platform coverage is a backstop, not a primary shield. If your personal policy excludes business use, you may still face a denied claim even when the platform has coverage, because the platform's policy often requires your personal coverage to respond first.
Rideshare Endorsements and Commercial Policies: Your Two Main Options
Drivers have two primary paths to close the coverage gap: add a rideshare endorsement to a personal policy, or purchase a commercial auto policy designed for livery and delivery use. Each approach has trade-offs in cost, complexity, and protection.
A rideshare endorsement is the simpler and often cheaper option. It extends your personal policy to cover the app-on period, typically adding liability, collision, and comprehensive coverage while you are waiting for a request. The endorsement does not turn your policy into a commercial policy, so it may still have limitations on the types of vehicles covered or the total mileage allowed.
A commercial auto policy is the more robust option, especially for full-time drivers or those using a vehicle primarily for business. It covers the vehicle for business use without the exclusions found in personal policies, and it can be tailored to match the specific requirements of the platforms you drive for.
Before choosing, gather these details:
- Your average weekly miles driven for personal versus business use.
- The specific coverage periods your platform provides and their limits.
- Whether your state requires additional filings or minimum limits for rideshare drivers.
- Your budget for monthly premiums and your tolerance for out-of-pocket risk.
Once you have those numbers, you can compare quotes for both options side by side. Comparing multiple carriers is the only reliable way to know which structure delivers the best value for your situation.
State Regulations and Minimum Coverage Requirements
Rideshare and delivery insurance is regulated at the state level, and requirements vary significantly. Some states mandate that platforms carry specific minimum limits during all three driving periods. Others place more responsibility on the driver to maintain adequate coverage.
California, for example, requires rideshare platforms to carry $1 million in liability coverage during active trips and at least $50,000 in liability during the app-on period. New York has its own set of rules that differ for rideshare versus delivery. Texas and Florida have their own thresholds that may be lower or structured differently.
Because these rules change and vary, it is essential to verify your state's specific requirements before relying on platform coverage alone. A licensed insurance agent can confirm the minimums in your state and help you structure a policy that meets them without overpaying for unnecessary coverage.
If you want to compare quotes from multiple carriers and see how rideshare endorsements affect your rate, you can use a free quote comparison tool to get personalized numbers in minutes. Getting quotes from several carriers is the fastest way to find out whether an endorsement or a commercial policy makes more financial sense for your driving profile.
Delivery Driver Insurance: Special Considerations
Delivery drivers face a slightly different insurance landscape than rideshare drivers. Food delivery, grocery delivery, and package delivery often involve more frequent stops, shorter trips, and a higher volume of low-speed incidents. These patterns can affect both your risk profile and your premium.
Many delivery platforms only provide liability coverage during active deliveries, and some provide no coverage at all during the waiting period. That means your personal policy is the primary source of protection for a significant portion of your working hours.
If you deliver for multiple platforms, your coverage needs become even more complex. Each platform may have different coverage terms, and stacking them does not necessarily create seamless protection. A commercial policy or a rideshare endorsement that covers business use broadly is often the cleaner solution.
Some insurers offer specific delivery driver endorsements that cover the app-on period for delivery platforms. These endorsements are becoming more common as the gig economy grows, but they are not available in every state or from every carrier. Checking with a licensed agent is the most reliable way to find out what is available in your area.
How to Evaluate Your Coverage Needs Step by Step
Building the right coverage starts with a clear assessment of your driving habits and financial risk tolerance. The following framework can help you move from uncertainty to a concrete plan.
Start by tracking your driving for a typical week. Separate personal miles from business miles and note how many hours you spend in each of the three driving periods. This data gives you a realistic picture of where your risk actually sits.
Next, review your current personal policy and identify the exclusions related to business use. Call your insurer and ask directly whether rideshare or delivery use is covered. If it is not, ask what endorsement or policy change would be required to add it.
Then, compare the cost of a rideshare endorsement against the cost of a commercial policy. In many cases, the endorsement is cheaper for part-time drivers, while a commercial policy is more cost-effective for full-time drivers who rack up significant business miles.
Finally, confirm that your coverage limits are high enough to protect your assets. State minimums are rarely sufficient to cover a serious accident, especially if the other party sues for damages beyond your policy limits. Higher liability limits cost more, but they provide a critical layer of financial protection.
Common Mistakes That Cost Drivers Thousands
The most expensive mistake is assuming that platform coverage eliminates the need for personal coverage. Drivers who rely solely on platform insurance often discover that the coverage does not respond until their own policy is exhausted, leaving them responsible for deductibles, gaps, and denied claims.
Another common error is failing to notify your insurer that you drive for a platform. Even if you have a rideshare endorsement, some carriers require you to disclose your gig work explicitly. Non-disclosure can lead to a denied claim or a cancelled policy.
Underinsuring the vehicle itself is also a frequent problem. If you carry only liability coverage, you will not be reimbursed for damage to your own car after an at-fault accident. Collision and comprehensive coverage are essential for drivers who depend on their vehicle for income.
Finally, many drivers never revisit their coverage after their first policy purchase. As your driving habits change, your coverage needs change too. An annual review with a licensed agent can catch gaps before they become claims.
Finding the Right Coverage Without Overpaying
The good news is that you do not have to choose between adequate coverage and affordable premiums. With the right endorsements and a clear understanding of your driving profile, you can build a policy that protects you without draining your earnings.
Start by getting quotes from multiple carriers. Rates for rideshare and delivery endorsements vary widely, and the same driver profile can produce significantly different premiums depending on the insurer. Comparing quotes is the single most effective way to reduce your costs.
You can also explore discounts that apply to your situation. Safe driver discounts, multi-policy discounts, and annual payment discounts can all lower your premium. Bundling auto with renters or homeowners coverage is another proven strategy for reducing costs while improving protection.
If you want to see how different coverage structures affect your rate, use a comparison platform that connects you with licensed agents who can explain your options. There is no obligation to buy, and the information you gather can help you make a confident decision.
For drivers who want a straightforward way to compare free auto insurance quotes online, a consumer education and comparison platform can help you understand coverage options, compare rates, and connect with licensed agents in your state. The goal is not to sell you a policy on the spot, but to give you the information you need to choose wisely.
Take the time to review your policy, confirm your coverage periods, and compare quotes from multiple carriers. A few hours of research today can save you thousands of dollars and a great deal of stress if an accident happens tomorrow. FreeAutoInsuranceQuotesOnline