Optional Auto Insurance Coverages Worth Adding in 2026
Optional auto insurance coverages worth adding can close costly gaps in a minimum policy. See which add-ons protect your assets and which you can skip.
By Elowen Parker
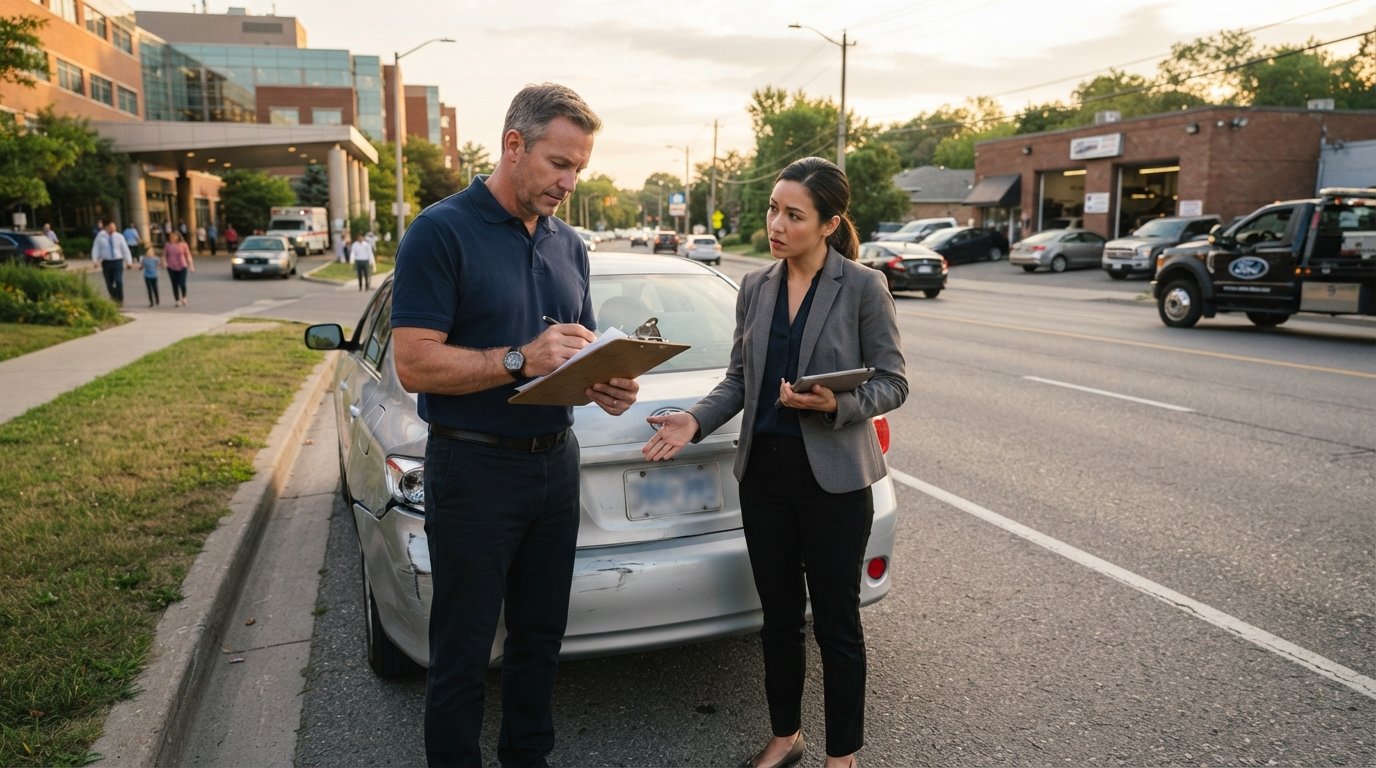
Your state's minimum liability requirements keep you legal, but they rarely keep you whole after a serious crash. The gap between what the law demands and what a real accident actually costs is where optional auto insurance coverages worth adding start to matter. A driver carrying only the minimum in most states could be personally responsible for tens of thousands of dollars in medical bills, lost wages, and vehicle replacement costs that the other driver's policy does not cover. The good news is that most of these add-ons cost surprisingly little per month, and a few of them can mean the difference between a manageable claim and a financial crisis.
This guide breaks down which optional coverages deserve a spot in your policy, which ones depend on your situation, and how to evaluate them without overpaying. If you want to see how these options affect real quotes from multiple carriers, you can compare free auto insurance quotes online side by side before committing to anything.
Why Minimum Coverage Rarely Protects You
Every state except New Hampshire requires some form of auto liability insurance. The problem is that minimum limits were set years ago and have not kept pace with the cost of medical care or vehicle repairs. In many states, the minimum bodily injury liability limit is $25,000 per person and $50,000 per accident. A single night in a hospital trauma unit can exceed $50,000 before surgery or rehabilitation even begins.
If you cause an accident and the damages exceed your liability limits, the injured party can pursue you personally for the difference. That means wage garnishment, lawsuits, and long-term financial damage. Optional coverages exist precisely to close these gaps, and they fall into two broad categories: coverages that protect you from other drivers, and coverages that protect your own vehicle and financial standing.
Understanding the difference between required and optional coverage is the first step toward building a policy that actually fits your life. Your lender or lease company may also require certain coverages, such as collision and comprehensive, before you can drive the car off the lot. Beyond those contractual requirements, the rest of your policy is a series of choices.
Uninsured and Underinsured Motorist Coverage
Roughly one in seven drivers nationwide operates without insurance, according to Insurance Research Council estimates, and the ratio is far higher in some states. Uninsured motorist coverage (UM) steps in when a hit-and-run driver or an uninsured driver causes your injuries. Underinsured motorist coverage (UIM) applies when the at-fault driver has insurance, but not enough to cover your total damages.
These two coverages are the strongest candidates for the "always add" list. They typically cost a few dollars per month, and they protect you in scenarios where you have no other recourse. Some states require insurers to offer UM/UIM, and a few mandate it outright. Even where it is optional, declining it is a gamble most drivers should not take.
UM/UIM usually covers medical expenses, lost wages, pain and suffering, and in some states property damage. It follows you even when you are a passenger in someone else's car or struck as a pedestrian. That portability makes it one of the most versatile protections in your entire policy.
Collision and Comprehensive Coverage
Collision coverage pays to repair or replace your vehicle after an accident with another car or object, regardless of who was at fault. Comprehensive coverage handles non-collision events: theft, fire, hail, flooding, vandalism, and animal strikes. Together they form the physical damage portion of your policy, and they are usually required if you have a loan or lease.
For older vehicles with low market value, the math gets trickier. If your car is worth $4,000 and your deductible is $1,000, you are effectively self-insuring the first quarter of its value. A common rule of thumb is to drop collision and comprehensive once the annual premium exceeds roughly 10 percent of the vehicle's value. Before making that call, it helps to understand what collision insurance covers and when it pays off, since the details vary by vehicle age, mileage, and your tolerance for risk.
One often-overlooked detail: comprehensive coverage also protects your car from damage that has nothing to do with driving, such as a tree limb falling on it during a storm. If you park on the street or live in an area with severe weather, that protection alone can justify the cost.
Medical Payments and Personal Injury Protection
Medical payments coverage (MedPay) pays for medical and funeral expenses for you and your passengers after an accident, regardless of fault. It works alongside your health insurance and can cover copays, deductibles, and ambulance rides that your health plan might not fully reimburse. Personal injury protection (PIP) goes further and is required in no-fault states.
PIP typically covers medical expenses, lost income, rehabilitation, and sometimes essential services like childcare or housekeeping while you recover. Even in states where PIP is optional, adding it can be smart if you have a high-deductible health plan or no health insurance at all. The coverage responds quickly, often without waiting for a fault determination, which matters when bills start arriving immediately.
If you already have robust health insurance and disability coverage, MedPay may feel redundant. But health plans frequently exclude auto-related injuries or apply separate deductibles, so a modest MedPay limit is often worth the small premium.
Roadside Assistance and Rental Reimbursement
These two coverages are convenience add-ons, but they earn their keep at the worst possible moments. Roadside assistance covers towing, jump-starts, flat tire changes, lockout service, and fuel delivery. Rental reimbursement pays for a rental car while yours is in the shop after a covered claim.
If you already belong to a motor club, compare the benefits before paying twice. Insurance-based roadside assistance usually costs less per month than a standalone membership, but the coverage limits may be lower. Rental reimbursement, meanwhile, is nearly essential if you have a long commute and no second vehicle. Without it, you could be paying out of pocket for a rental for weeks while your car is being repaired.
A simple decision framework helps here. Ask yourself three questions:
- Do I have another vehicle I can drive if mine is in the shop?
- Does my existing motor club or credit card already cover towing?
- Can I absorb a $40 to $80 per day rental cost for two weeks without financial strain?
If the answer to the first is no and the third is no, rental reimbursement is close to a must-have. If you already have a reliable motor club, you can likely skip insurance-based roadside assistance and put that money toward a higher liability limit instead.
Gap Insurance and New Car Replacement
If you financed or leased your vehicle with a small down payment, you may owe more than the car is worth the moment you drive off the lot. Standard collision and comprehensive pay only the actual cash value, which factors in depreciation. Gap insurance covers the difference between what you owe and what the insurer pays if the car is totaled or stolen.
New car replacement coverage goes a step further and pays for a brand-new vehicle of the same make and model, rather than the depreciated value. It usually applies only to cars within the first one to three model years, depending on the insurer. Both coverages are inexpensive relative to the risk they address, and both become unnecessary once your loan balance drops below the car's market value.
Lease drivers should pay particular attention here. Lease agreements often include gap coverage automatically, so buying it again through your auto policy would be redundant. Check your lease contract before adding it.
Accident Forgiveness and Minor Violation Forgiveness
Accident forgiveness prevents your premium from rising after your first at-fault accident. Minor violation forgiveness does the same for a single speeding ticket or similar infraction. These are not coverages in the traditional sense; they are pricing protections, but they can save hundreds of dollars over a policy term.
Availability varies widely by insurer and state, and some carriers offer them only to drivers with clean records and long tenure. If you have a teenage driver on your policy or you commute in heavy traffic, the value goes up. If you have a spotless record and a forgiving insurer already, the benefit may be marginal.
Ask your agent whether the feature is included automatically or costs extra, and whether it applies per policy or per driver. The details matter more than the marketing name.
Custom Parts, Sound Equipment, and Rideshare Coverage
Standard policies cap coverage for aftermarket modifications such as custom wheels, lift kits, audio systems, and specialty paint. If you have invested thousands in your vehicle's appearance or performance, custom parts coverage reimburses that investment after a covered loss. Limits are typically modest unless you buy additional coverage.
Rideshare coverage is a separate consideration. If you drive for a platform like Uber or Lyft, your personal auto policy likely excludes commercial use. The platform's insurance applies only during certain phases of a trip. A rideshare endorsement fills the gaps between your personal policy and the platform's coverage, and it is one of the most important optional coverages worth adding for gig drivers.
Delivery drivers face similar gaps, though the specifics differ by carrier and platform. If you use your car for any paid work, disclose it to your insurer. Nondisclosure can void a claim entirely.
How to Decide Which Optional Coverages to Add
The right mix depends on your assets, your vehicle, your driving habits, and your tolerance for financial risk. A useful starting point is to rank coverages by the size of the loss they protect against and the likelihood of that loss occurring. UM/UIM, for example, protects against a potentially catastrophic loss that is reasonably common. Roadside assistance protects against a small loss that is very common.
Budget matters too. Adding every optional coverage can inflate your premium by 30 percent or more. A smarter approach is to prioritize the coverages that protect your income and assets first, then add convenience coverages as your budget allows.
Quotes vary dramatically between carriers for the same coverage package. That is why comparing multiple quotes before you buy is one of the highest-value habits in personal finance. A few minutes of comparison can save hundreds of dollars per year, and it lets you see exactly how each optional coverage affects your total premium.
Review your policy annually, especially after major life changes such as buying a home, paying off a car, adding a teen driver, or switching jobs. Coverages that made sense two years ago may be redundant today, and new gaps may have opened up. Optional auto insurance coverages worth adding are not a one-time decision; they are part of an ongoing strategy to keep your protection aligned with your life.