How Your Auto Insurance Deductible Affects Claims Payout
Your deductible directly reduces every claim payout. Call 8332147506 to compare policies and find the right balance for your budget.
By Luca Harrington
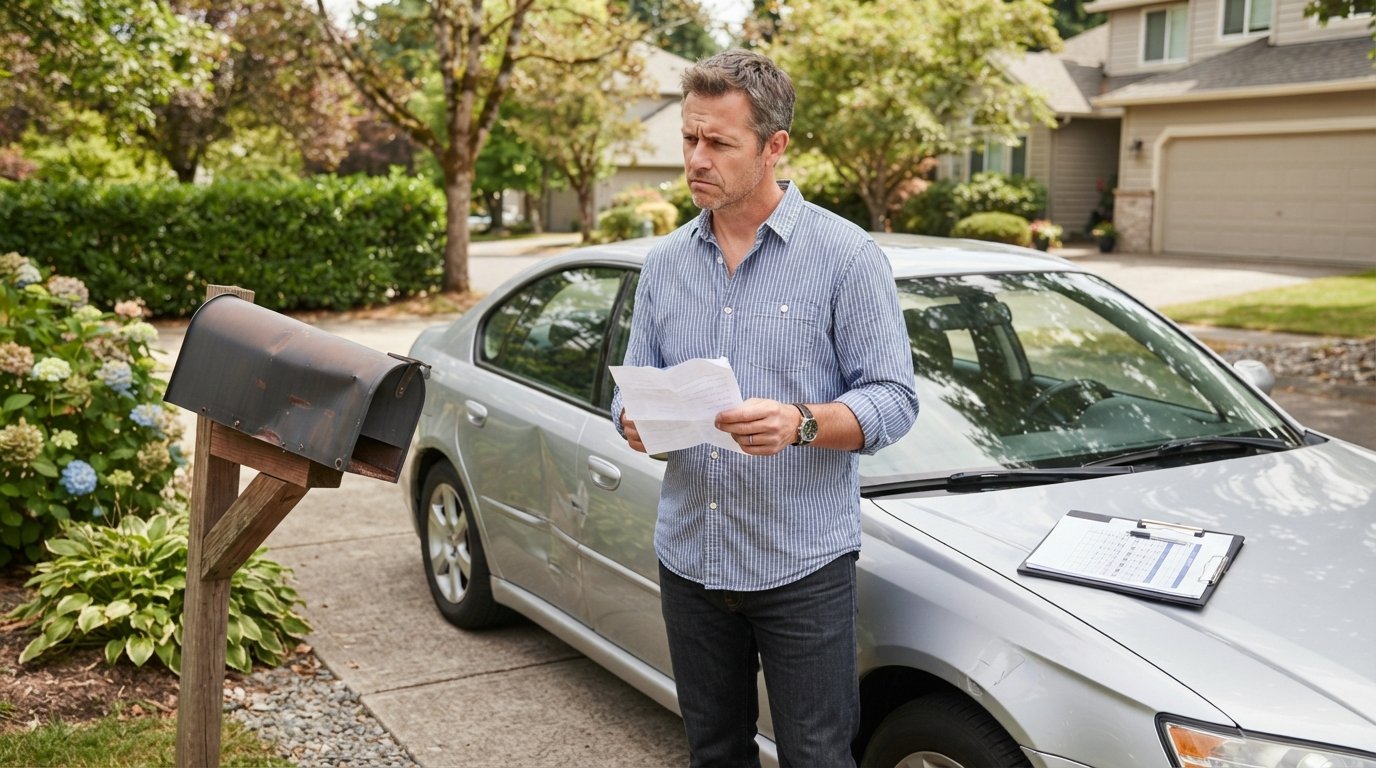
You just backed into a mailbox. The damage is minor, maybe $1,200. You file a claim, expecting your insurer to cover most of it, and then you remember your deductible: $1,000. Suddenly, the math changes. Your payout shrinks to $200, and you start wondering whether filing was even worth it. This scenario plays out every day, and it highlights a critical truth: your auto insurance deductible is not just a number on your policy. It directly determines how much money you actually receive when you file a claim.
Understanding how does an auto insurance deductible affect claims payout is essential for every driver. It influences your out-of-pocket costs, your premium, and even your decision about whether to file a claim at all. This guide breaks down the mechanics, the math, and the strategy behind deductibles so you can make smarter choices about your coverage.
What Is an Auto Insurance Deductible?
An auto insurance deductible is the amount you agree to pay out of pocket before your insurance company covers the rest of a covered claim. Think of it as your share of the financial responsibility. If your deductible is $500 and the covered damage is $3,000, you pay $500, and your insurer pays $2,500. The deductible is subtracted from the total claim amount, not added to it.
Deductibles apply to specific coverage types, primarily collision and comprehensive. Collision coverage handles damage from accidents involving another vehicle or object. Comprehensive coverage handles non-collision events like theft, vandalism, fire, or natural disasters. Liability coverage, which pays for damage you cause to others, typically does not have a deductible. That distinction matters because it determines which claims will reduce your payout and which will not.
Deductible amounts vary widely. Common choices include $250, $500, $1,000, and even $2,000. The amount you select when you purchase or renew your policy stays with you until you change it. Some insurers offer disappearing deductibles that reduce over time if you remain claim-free, but those programs are less common than standard fixed deductibles.
The Direct Math: How Deductibles Reduce Your Payout
The relationship between your deductible and your claims payout follows a simple formula. Your payout equals the covered damage minus your deductible. If the damage is less than or equal to your deductible, you receive nothing from your insurer. This is where many drivers get surprised.
Consider a few examples to see how the numbers work in practice. Suppose you have a $500 deductible and you file a $2,500 collision claim. Your insurer pays $2,000. If your deductible were $1,000, the payout drops to $1,500. If your deductible were $1,500, the payout falls to $1,000. The higher your deductible, the lower your payout for any given amount of damage.
Now imagine the damage is only $600. With a $500 deductible, you receive $100. With a $1,000 deductible, you receive nothing. In that second scenario, filing a claim may not make sense because you would pay the entire repair cost yourself, and you would still have a claim on your record that could raise future premiums. This is the break-even calculation every driver should understand before filing.
Here is a quick framework for deciding whether to file a claim based on your deductible:
- If damage is less than your deductible, paying out of pocket is usually the better choice.
- If damage is slightly above your deductible, compare the payout to the potential premium increase.
- If damage is significantly above your deductible, filing a claim typically makes financial sense.
- If the damage involves injuries or liability, always file regardless of your deductible.
The threshold where filing becomes worthwhile depends on your insurer and your claims history. A single at-fault claim can raise your premium by 20 to 40 percent or more, depending on your state and carrier. That increase can persist for three to five years. When you weigh a small payout against years of higher premiums, the math often favors handling minor damage yourself.
How Deductible Choices Affect Your Premium
Your deductible and your premium have an inverse relationship. Choosing a higher deductible lowers your premium because you are taking on more financial risk. Choosing a lower deductible raises your premium because your insurer bears more of the risk. This trade-off is one of the most direct ways to control your auto insurance costs.
The savings from a higher deductible can be substantial. Moving from a $250 deductible to a $1,000 deductible might reduce your annual premium by 15 to 30 percent, depending on your insurer and vehicle. On a $1,500 annual premium, that could mean $225 to $450 in savings per year. Over five years, that adds up to more than $1,000, which could offset the higher out-of-pocket cost if you file a claim.
However, the strategy only works if you have the cash reserves to cover the higher deductible when needed. A $2,000 deductible that you cannot afford to pay is a liability, not a savings strategy. The best deductible is one that balances premium savings with an amount you can comfortably pay after an accident. For many drivers, $500 to $1,000 represents a reasonable middle ground.
If you are exploring ways to reduce your overall insurance costs, including how bundling policies can complement your deductible strategy, our guide on smart savings for renters and homeowners explains how combining coverage can unlock additional discounts.
When Deductibles Do Not Apply
Not every claim involves a deductible. Understanding which coverage types include deductibles and which do not can help you anticipate your payout and avoid confusion during the claims process. Liability coverage, which pays for damage you cause to another person or their property, does not have a deductible. If you are at fault in an accident and your liability coverage responds, your insurer pays the full covered amount up to your policy limits.
Personal injury protection (PIP) and medical payments coverage, which pay for medical expenses regardless of fault, may or may not include a deductible depending on your state and policy. Some states require PIP with no deductible, while others allow you to choose one. Uninsured and underinsured motorist coverage sometimes includes a deductible, though many insurers waive it when the at-fault driver is identified.
The key takeaway is that deductibles primarily apply to first-party coverage, meaning coverage that pays for your own vehicle or injuries. Third-party coverage, which pays for damage you cause to others, generally does not involve a deductible. Knowing this distinction helps you set realistic expectations about your claims payout before you file.
Deductible Scenarios: Comprehensive vs. Collision
Collision and comprehensive deductibles can be set separately, and some insurers even allow you to choose different amounts for each. For example, you might select a $500 collision deductible and a $250 comprehensive deductible. This flexibility lets you tailor your coverage to the risks you face most often.
Comprehensive claims, such as theft or storm damage, are often smaller than collision claims. A cracked windshield might cost $400 to repair. A stolen catalytic converter might cost $1,500 to replace. A tree branch falling on your hood might cause $2,000 in damage. If your comprehensive deductible is $500, you would receive $1,100 for the catalytic converter claim and $1,500 for the tree branch claim, but you would pay the full $400 for the windshield if your deductible exceeds that amount.
Collision claims tend to be larger because they involve vehicle-to-vehicle or vehicle-to-object impacts. A typical fender bender might cause $2,000 to $5,000 in damage. A serious collision could total your vehicle, meaning the repair cost exceeds its market value. In a total loss scenario, your insurer pays the actual cash value of your vehicle minus your deductible. If your car is worth $12,000 and your deductible is $1,000, you receive $11,000.
Some drivers choose a lower comprehensive deductible because comprehensive claims are more frequent and often smaller. Others choose a higher comprehensive deductible to save on premiums, reasoning that they can absorb the cost of a windshield repair. There is no single right answer, but understanding how each deductible affects your payout in common scenarios can guide your decision.
The Total Loss Calculation and Your Deductible
When your vehicle is declared a total loss, the claims payout calculation follows a specific formula. Your insurer determines the actual cash value (ACV) of your vehicle at the time of the loss, then subtracts your deductible. The result is your settlement amount. If you have a loan or lease, your insurer may pay the lienholder directly, and you receive any remaining balance.
This is where a higher deductible can sting. If your vehicle is worth $8,000 and your deductible is $1,500, you receive $6,500. That $1,500 comes directly out of your settlement, leaving you with less money to put toward a replacement vehicle. If you have a loan balance higher than the ACV, you may owe the difference out of pocket unless you have gap insurance.
For drivers with newer vehicles or outstanding loans, a lower deductible may provide more financial protection in a total loss scenario. The higher premium is the trade-off for a larger settlement when you need it most. Conversely, drivers with older vehicles that have low market value might choose a higher deductible because the premium savings outweigh the reduced payout potential.
How Deductibles Interact With Premium Increases After Claims
Filing a claim does more than reduce your payout by the deductible amount. It can also trigger a premium increase at renewal. This double impact makes the decision to file more complex than simply comparing damage to deductible. You must also consider the long-term cost of a claim on your insurance record.
Most insurers surcharge for at-fault accidents, but the amount varies. A single at-fault claim might raise your premium by 20 to 40 percent. If your annual premium is $1,800, that could mean an extra $360 to $720 per year for three to five years. The total cost could reach $1,080 to $3,600. When you compare that to a payout of $500 or $1,000 after your deductible, filing a small claim rarely makes financial sense.
Some insurers offer accident forgiveness programs that waive the premium increase for your first at-fault accident. If you have accident forgiveness, the calculus changes because you avoid the surcharge. However, even with accident forgiveness, you still pay your deductible, and the claim remains on your record. Other insurers may not surcharge for comprehensive claims, such as theft or weather damage, because those are not considered your fault. Always check your policy or ask your agent before filing.
Choosing the Right Deductible for Your Situation
Selecting the optimal deductible requires balancing three factors: your premium budget, your emergency savings, and your risk tolerance. A deductible that saves you $300 per year but leaves you unable to cover a $2,000 repair is not a good fit. Conversely, a $250 deductible that costs you an extra $400 per year may not be worth it if you rarely file claims.
Start by calculating how much you could comfortably pay out of pocket tomorrow if you had an accident. That amount is your maximum reasonable deductible. If you have $1,000 in an emergency fund, a $1,000 deductible is manageable. If you have $3,000 saved, you might consider a $1,500 or $2,000 deductible for the premium savings.
Next, compare quotes from multiple insurers with different deductible levels. The premium difference between a $500 and $1,000 deductible varies by carrier. Some insurers offer steeper discounts for higher deductibles, while others offer minimal savings. Getting quotes at several deductible levels helps you see the actual trade-off for your specific situation.
Finally, consider your vehicle's value and your financial obligations. If you have a loan or lease, the lender may require a maximum deductible, often $500 or $1,000. If your vehicle is older and paid off, you have more flexibility. For drivers seeking free, no-obligation quotes from multiple carriers to compare deductible options, FreeAutoInsuranceQuotesOnline provides educational resources and rate comparison tools to help you make an informed decision.
Special Considerations for Different Vehicle Types
Deductible rules and options can vary for specialized vehicles. Motorcycles, RVs, antique cars, and commercial vehicles may have different deductible structures than standard passenger cars. For example, antique car insurance often includes agreed value coverage, which pays a predetermined amount rather than actual cash value. The deductible still applies, but the payout calculation starts from a different baseline.
Commercial auto policies may offer per-accident deductibles or split deductibles for different coverage types. If you use your vehicle for business, your personal auto policy may not cover accidents that occur during work-related driving. Understanding the deductible and coverage structure of a commercial policy is essential before you file a claim.
RV insurance often includes comprehensive and collision coverage with deductibles similar to auto insurance, but the amounts may be higher because RVs are more expensive to repair. Motorcycle insurance may offer lower deductibles for comprehensive coverage to encourage theft claims, which are common for motorcycles. Always review the specific deductible terms for your vehicle type before assuming they match standard auto insurance.
Steps to Take Before Filing a Claim
Before you pick up the phone to file a claim, take a few minutes to run the numbers. This simple process can save you thousands of dollars in unnecessary premium increases and help you make a rational decision rather than an emotional one.
- Get an estimate for the repair cost from a trusted mechanic or body shop.
- Compare the estimate to your deductible to see if you would receive any payout.
- Estimate the potential premium increase by checking your insurer's claims surcharge policy.
- Calculate the total cost of filing (deductible plus premium increase over three years).
- Compare that total cost to the payout you would receive.
- Decide whether to file, pay out of pocket, or negotiate with the other party if applicable.
This framework works for most collision and comprehensive claims. For liability claims involving injuries or significant property damage to others, always file because the costs can far exceed your deductible and your policy limits. The decision not to file is only appropriate for first-party claims where the math clearly favors paying out of pocket.
Remember that your deductible is a contract term you agreed to when you bought your policy. You cannot negotiate it after an accident. The time to adjust your deductible is at renewal, when you can compare quotes and choose a new amount based on your current financial situation.
Your auto insurance deductible is one of the most controllable variables in your policy. It determines your claims payout, influences your premium, and shapes your decision-making after an accident. By understanding the math and choosing a deductible that matches your finances, you can avoid surprises and make confident decisions when it matters most. Take a few minutes today to review your deductible, check your emergency savings, and see whether a different amount could better serve your needs.