How Vehicle Safety Features Lower Auto Insurance Costs
See how vehicle safety features lower auto insurance premiums and cut your monthly bill. Call 8332147506 to compare personalized quotes today.
By Theo Blackwe
Your car's safety technology does more than protect you in a crash. It can also trim the amount you pay for coverage every month. Insurers look closely at the vehicles they cover, and when a car arrives with automatic braking, lane-keeping assistance, and blind-spot monitoring, the risk profile changes. That shift in risk is the foundation of how vehicle safety features lower auto insurance premiums, and it is a lever you can pull even if you have not thought about it before.
At NewAutoInsurance.com, we have watched this trend reshape quotes for drivers across the United States. The site is an independent educational resource, not an insurance carrier or broker, so our role is to explain the mechanics clearly and then connect you with licensed agents who can turn that understanding into real numbers. The connection between safety equipment and price is not magic. It follows a logical chain of crash frequency, repair costs, and actuarial data, and once you see that chain, you can use it to your advantage.
This article walks through exactly how the discount works, which features carry the most weight, how to prove your car has them, and what to do when the savings are smaller than expected. Along the way, we will touch on related strategies such as bundling auto with renters or homeowners coverage, because safety discounts rarely work in isolation. They stack with other savings, and understanding the full picture helps you negotiate from a stronger position.
The Risk Math Behind Safety Feature Discounts
Insurance pricing is ultimately a prediction problem. Carriers estimate how often a driver will file a claim and how expensive that claim will be, then charge a premium that covers expected losses plus operating costs and profit. Safety features influence both sides of that equation. When a vehicle can prevent a collision, the frequency of claims drops. When a vehicle can reduce the severity of a collision, the average cost per claim drops. Lower frequency and lower severity translate into lower expected losses, and that is the direct path to a smaller premium.
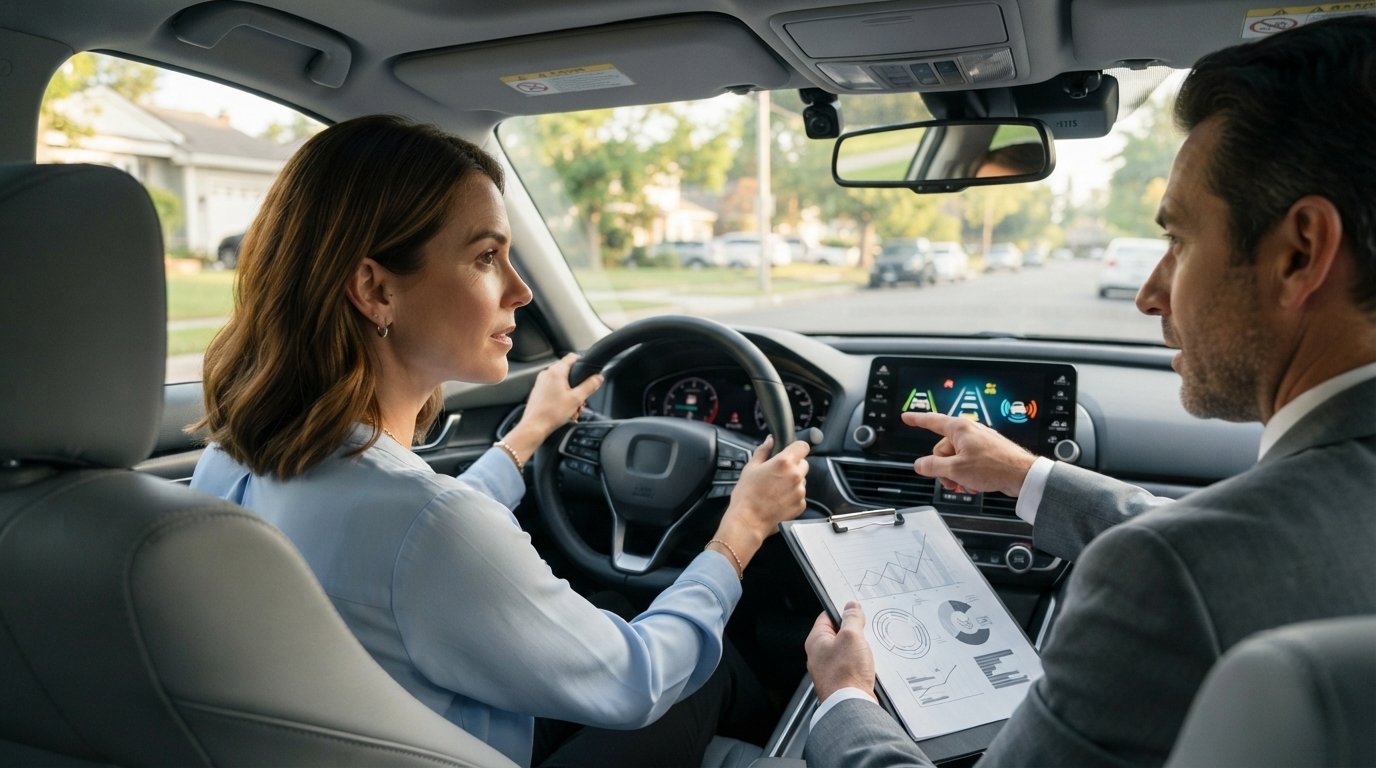
Consider automatic emergency braking. A driver who momentarily looks away may still avoid a rear-end collision because the car brakes on its own. That single avoided claim saves the insurer thousands of dollars in liability and collision payouts. Multiply that across thousands of policyholders, and the carrier can afford to reduce rates for vehicles equipped with the technology. The same logic applies to lane-departure warnings, which reduce sideswipe and runoff accidents, and to adaptive headlights, which improve night visibility and cut down on pedestrian and object strikes.
Insurers do not guess at these numbers. They rely on actuarial studies, crash data from the Insurance Institute for Highway Safety, and their own claims histories. When the data consistently shows that a feature reduces losses, the carrier files a discount with state regulators. That is why you sometimes see a specific line item on your policy declaration page that says something like "Safety Feature Discount" or "Advanced Driver Assistance Discount." It is not a marketing gimmick. It is a formal recognition that your car presents less risk than a comparable vehicle without the equipment.
It helps to think of the discount as a shared benefit. You pay less, but you also avoid the hassle, injury, and disruption of a crash. The insurer pays less, but it also retains a customer who is less likely to leave after a bad experience. That alignment is why safety discounts have become more common and more generous over the past decade, even as vehicles have become more expensive to repair.
Which Safety Features Deliver the Biggest Savings
Not every feature carries the same weight. Some are considered foundational and appear on nearly every discount schedule, while others are newer and may only qualify for a modest reduction or a pilot program. The table below reflects the general pattern we see across the market, though exact percentages vary by carrier and state.
- Automatic emergency braking (AEB): Often the single most valuable feature, with discounts that can reach 5 to 15 percent on certain coverages because it directly prevents rear-end and low-speed collisions.
- Lane-keeping and lane-departure warning: Frequently bundled with AEB in discount schedules, these systems reduce sideswipes and single-vehicle runoff crashes.
- Blind-spot monitoring: Valued for reducing lane-change collisions, which are common and expensive because they often involve multiple vehicles.
- Forward collision warning: Sometimes paired with AEB, sometimes separate, and usually worth a smaller but still meaningful reduction.
- Adaptive headlights and automatic high beams: Less publicized but increasingly recognized because they improve nighttime visibility, when fatal crashes are more likely.
- Rear cross-traffic alert and backup cameras: Helpful for parking lot and driveway incidents, which are frequent and can be costly even at low speeds.
Notice that these features share a common trait: they address the most common and most expensive claim types. Rear-end collisions, lane-change accidents, and parking lot incidents dominate claims frequency. Features that target those scenarios earn the most favorable treatment from insurers. Features that address rare events, such as rollover protection or pedestrian detection in limited conditions, may still be valuable but often carry smaller discounts because the actuarial impact is harder to measure.
There is also a category of features that can work against you. Advanced driver assistance systems often require calibration after a windshield replacement or a minor fender bender. That calibration can add hundreds of dollars to a repair bill. Some insurers have responded by raising comprehensive or collision premiums slightly for vehicles with complex sensor suites, even as they apply a safety discount elsewhere. The net effect is usually still positive, but it is not automatic. This is one reason it pays to ask an agent how a specific vehicle is rated before you assume the safety package will lower your total cost.
How to Prove Your Vehicle Qualifies
You cannot simply tell an insurer your car has automatic braking and expect the discount to appear. Carriers need documentation, and the process is more straightforward than many drivers expect. The first step is to identify the exact trim level and option packages on your vehicle. A base model may not include the same safety suite as a higher trim, even though both wear the same nameplate. Your VIN is the key. When you request a quote, the carrier decodes the VIN and pulls the factory build data, which tells them precisely which features were installed at the plant.
If you are already insured and want to confirm you are receiving every discount you deserve, gather a few documents before you call. The window sticker or Monroney label lists standard and optional equipment. Your purchase agreement or lease contract may also list option packages. If you bought the car used and the sticker is gone, a dealer can print a build sheet from the VIN, and some manufacturers offer this online. Having those details ready speeds up the conversation and reduces the chance that a discount is missed.
- Locate your VIN on the driver's side dashboard or inside the driver's door jamb.
- Request a build sheet from a dealership or use your manufacturer's owner portal.
- Compare the listed features against your insurer's discount schedule, which is often available on the company website or by asking an agent.
- Submit the documentation through your online account or provide it to your agent.
- Confirm the discount appears on your next declaration page, and follow up if it does not.
Timing matters here. If you are shopping for a new policy, provide the VIN at the quote stage so the discount is built into the initial price. If you are already insured, ask whether the discount can be applied mid-term or whether you need to wait until renewal. Many carriers will apply it immediately and adjust your remaining payments, but some only update at renewal. Knowing the answer prevents surprise when the bill arrives.
It also helps to ask which specific features triggered the discount. If your car has blind-spot monitoring but not automatic braking, you may qualify for a smaller reduction than you hoped. Understanding the breakdown lets you decide whether a different vehicle or a different carrier would produce a better outcome. It also gives you a concrete list to revisit if you add aftermarket equipment, though be aware that most insurers only recognize factory-installed systems.
Stacking Safety Discounts With Other Savings
Safety feature discounts are most powerful when combined with other reductions. A driver with a clean record, a paid-in-full policy, and a bundled home or renters policy can layer several discounts on top of the safety credit. The order in which discounts apply varies by carrier, and some discounts are multiplicative while others are additive, so the final percentage is not always a simple sum. Still, the principle holds: the more low-risk signals you present, the more room the insurer has to reduce your rate.
Bundling is one of the most reliable companions to a safety discount. When you combine auto coverage with renters or homeowners insurance, you often unlock a multi-policy credit that applies to both policies. That credit can be substantial on its own, and it does not compete with the safety discount. In many cases, the two work together, producing a total reduction that is larger than either would deliver alone. If you rent your home, do not assume bundling is only for homeowners. Renters insurance is inexpensive and frequently qualifies for the same multi-policy treatment.
Other discounts that pair well with safety features include low-mileage credits for drivers who work from home, good student discounts for younger drivers, and defensive driving course credits. Each one tells the insurer something favorable about your risk profile. The safety feature discount tells them your car is less likely to be in a crash. The others tell them you are less likely to cause one. Together, they paint a picture of a low-risk policyholder, and that picture is what ultimately determines your price.
One caution: do not assume every advertised discount will apply to you. Some are restricted by state law, some require specific coverages, and some are only available to new customers. A licensed agent can walk through your actual policy and identify which credits are realistic. That is why comparing quotes from multiple carriers matters. Two companies may treat the same safety feature very differently, and the only way to know which one values it more is to put them side by side.
When Safety Features Do Not Lower Your Premium
There are situations where a car full of advanced technology still produces a higher premium than an older, simpler vehicle. This can be frustrating, but the reasons are logical. The most common is repair cost. A minor collision that would have cost 800 dollars to fix on a 2010 sedan might cost 3,000 dollars on a 2024 model because of sensors, cameras, radar units, and the calibration required to make them work again. If the insurer expects to pay more per claim, it may charge more even after applying a safety discount.
Another factor is theft risk. Some vehicles with keyless entry and push-button start have been targeted by relay attacks, where thieves amplify the key fob signal to unlock and start the car. Insurers track theft claims by make and model, and a vehicle with a high theft rate may carry a higher comprehensive premium regardless of its crash-avoidance technology. Similarly, certain trim levels or performance packages may attract higher rates because they are associated with more aggressive driving, even if the same safety features are present.
Finally, state regulations and carrier philosophy play a role. Some states require insurers to offer safety discounts, while others leave it to the market. Some carriers are aggressive about rewarding new technology, and others wait for more data before committing to a discount. If your current insurer does not recognize the feature you have, that is not necessarily a dead end. It may simply mean you are with the wrong carrier for your vehicle. Shopping around is the most reliable way to find out.
It is also worth checking whether your policy includes coverage that interacts with safety systems. For example, if you have uninsured motorist coverage, the safety features on your car may reduce the likelihood that you need to use it, but they do not change the premium for that coverage in most cases. The discount usually applies to liability, collision, and comprehensive portions of the policy. Understanding which line items are affected helps you set realistic expectations and ask better questions.
Practical Steps to Capture the Savings
Capturing the savings from vehicle safety features is a process, not a single phone call. The drivers who do it well tend to follow a consistent pattern. They start by knowing exactly what equipment their car has, then they verify that each feature is recognized by their insurer, and finally they compare that result against other carriers to make sure they are not leaving money on the table. It sounds simple, but the details matter, and the difference between a good outcome and a great one often comes down to preparation.
If you are in the market for a new or used car, treat safety features as part of the purchase decision alongside price and fuel economy. A vehicle with automatic emergency braking and blind-spot monitoring may cost slightly more upfront, but the insurance savings over several years can narrow the gap. More importantly, those features reduce the chance that you will be involved in a crash at all, which is a benefit no discount can fully measure. When you request quotes, provide the VIN so the carrier can rate the exact vehicle rather than a generic model.
For drivers who already own their cars, the path is simpler. Pull your declaration page, look for any safety-related line items, and compare them against what your vehicle actually has. If something is missing, call your agent with the documentation in hand. If your current carrier does not offer a discount for a feature you have, ask why and then check competitors. The market is competitive, and carriers regularly adjust their discount schedules to attract low-risk drivers. A feature that was ignored two years ago may be rewarded today.
Finally, remember that safety features are only one input among many. Your driving record, location, annual mileage, credit-based insurance score (where permitted), and coverage choices all influence what you pay. The goal is not to chase every possible discount in isolation but to assemble a policy that reflects your actual risk. When you do that well, the savings tend to follow naturally, and you end up with coverage that protects you without overpaying for the privilege.
To see how your vehicle's safety equipment translates into real quotes, you can compare free auto insurance quotes online and put the theory to the test. A few minutes of comparison can reveal which carriers value your car's technology the most, and that knowledge is the first step toward a lower premium.
Vehicle safety features lower auto insurance premiums because they reduce the frequency and severity of claims, and insurers pass those expected savings back to drivers. The effect is not uniform, and it is not automatic, but it is real and measurable. By knowing your vehicle's equipment, documenting it clearly, and comparing carriers, you can make sure you receive the credit you have earned. The technology in your car is already working to keep you safe. With a little effort, it can also work to keep your insurance bill in check.