How to Lower Car Insurance Premiums Without Bundling
Stack quotes, discounts, and coverage tweaks to cut your auto premium without moving your home or renters policy.
By James Carter
Many drivers assume the only real path to cheaper auto insurance runs through a homeowners or renters bundle. That assumption costs them money. If you rent, if you live with family, if your home policy sits with a carrier that charges high auto rates, or if you simply prefer to keep your policies separate, you still have plenty of levers to pull. Learning how to lower car insurance premiums without bundling is less about one magic discount and more about stacking several smaller wins until the total drops by hundreds of dollars per year.
This guide walks through the strategies that work independently of any bundle: shopping multiple carriers, adjusting coverage smartly, using usage-based programs, and claiming every discount you already qualify for. It also explains when a bundle genuinely helps and when walking away from one saves you more.
Shop Multiple Carriers At Every Renewal
The single most effective way to cut premiums without bundling is to compare quotes from several insurers side by side. Carriers price risk differently. One company may penalize a recent fender bender heavily while another barely flinches. One may love your ZIP code, vehicle, and credit profile, while another treats the same combination as high risk. Loyalty rarely pays in this market: long-term customers often absorb rate increases that new customers never see.
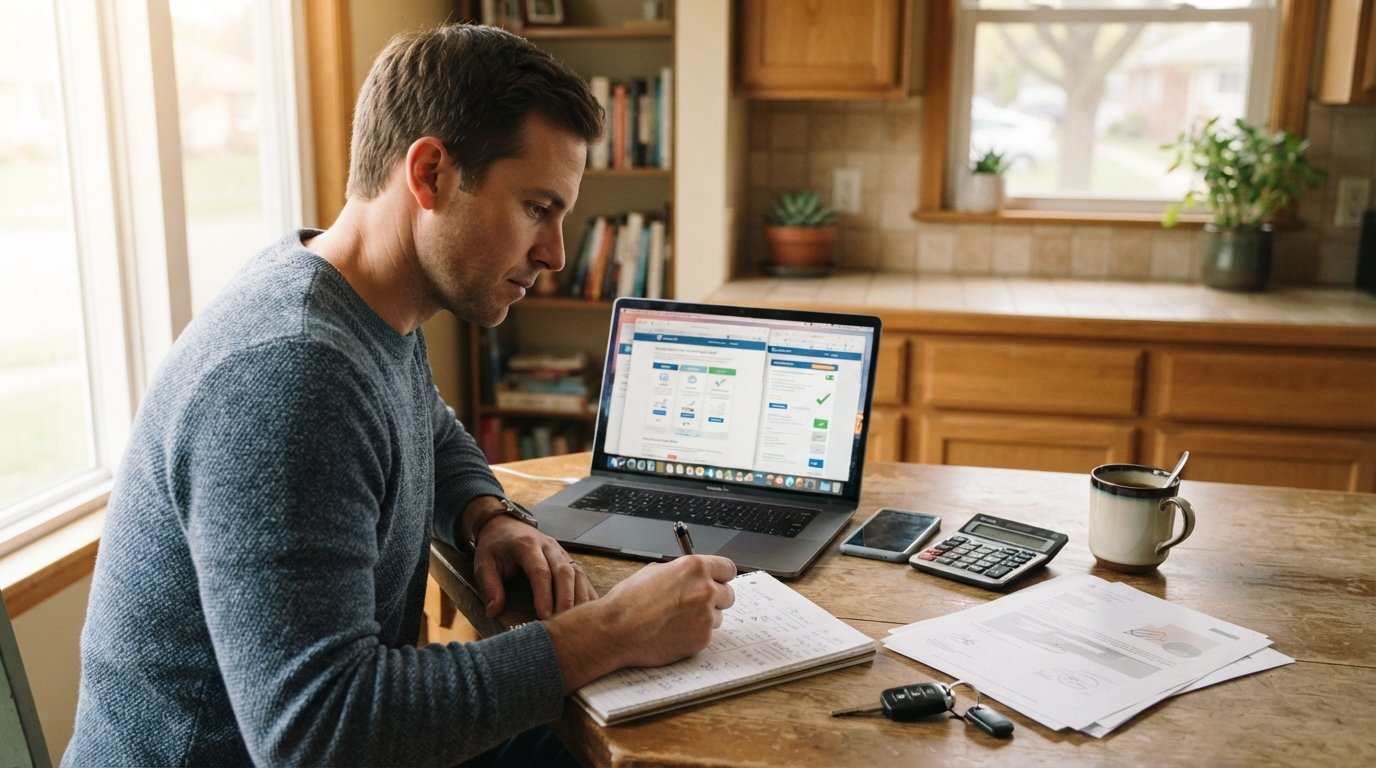
The practical move is to gather at least three to five quotes at each renewal, not just when you buy a new car. Rates shift constantly, and a carrier that was expensive two years ago may now be the cheapest option for your profile. Comparison platforms make this fast because you enter your details once and receive multiple offers. For example, free auto insurance quotes online let you see competing rates from multiple carriers without phone calls or pressure, which is exactly the kind of leverage you need when you are not relying on a bundle discount.
When you compare, keep the coverage limits and deductibles identical across quotes. Otherwise you are comparing apples to oranges, and a cheap quote may simply reflect weaker protection. If you find a lower rate, give your current insurer a chance to match it. Retention departments often have flexibility they do not advertise, especially when they know you are actively shopping.
Rightsize Your Coverage Without Gutting Protection
Overpaying for coverage you do not need is one of the most common forms of insurance waste. On the flip side, cutting the wrong coverage can leave you exposed to a claim that wipes out your savings. The trick is to trim intelligently.
Start with your deductibles. Raising a comprehensive or collision deductible from $500 to $1,000 can cut those portions of your premium by 15 to 30 percent, depending on the carrier. The tradeoff is that you pay more out of pocket after a claim, so this works best if you have an emergency fund that can absorb the difference. Never raise a deductible beyond what you could comfortably pay tomorrow.
Next, look at optional coverages. Roadside assistance, rental reimbursement, and gap insurance are valuable in some situations and redundant in others. If you already belong to a motor club, you may be paying twice for towing. If your car is worth less than the cost of comprehensive and collision coverage, dropping those coverages on an older vehicle can save real money. As a rule of thumb, if your annual comprehensive and collision premium exceeds 10 percent of your car's market value, it is worth running the math.
Do not, however, reduce your liability limits below your actual net worth. Liability coverage protects you when you cause an accident that injures someone or damages property. State minimums are rarely enough. If you are unsure where your limits should sit, working with a licensed agent through a service like NewAutoInsurance.com can help you understand the tradeoffs before you commit. NewAutoInsurance.com is an independent educational resource, not an insurer or broker, and it connects drivers with licensed agents for personalized quotes.
Use Usage-Based And Telematics Programs
Usage-based insurance programs, sometimes called telematics or pay-per-mile plans, track your driving habits through a smartphone app or a device plugged into your car. Safe drivers, low-mileage drivers, and people who avoid late-night driving often earn meaningful discounts, frequently 10 to 30 percent at renewal.
These programs are especially attractive if you work from home, commute short distances, or have a clean driving record. They are less attractive if you drive aggressively, brake hard, or rack up highway miles at odd hours, because the same data that earns discounts for some drivers can trigger surcharges for others.
Before enrolling, ask three questions:
- Does the program require a plug-in device or just a phone app?
- Is the discount applied immediately or only after a monitoring period?
- Can poor driving scores raise my rate at renewal?
If the answers favor your driving style, a telematics program is one of the few discounts that stacks cleanly on top of shopping around, and it does not require you to move any other policy.
Claim Every Discount You Already Qualify For
Insurers bury discounts in fine print, and many drivers never ask. Without any bundling, you may still qualify for a surprising number of reductions:
- Paid-in-full discount for paying the full six- or twelve-month premium upfront
- Automatic payment discount for enrolling in autopay
- Paperless billing discount for receiving documents by email
- Good student discount for full-time students with strong grades
- Defensive driving course discount for completing an approved class
- Low-mileage discount for driving under a set annual threshold
- Vehicle safety features discount for airbags, anti-lock brakes, or anti-theft systems
- New car discount for recently purchased vehicles with modern safety tech
Individually, these discounts may shave 2 to 10 percent each. Stacked together, they can easily cut a premium by 20 percent or more, which often rivals or beats a bundle discount. Call your insurer and ask for a full list of discounts they offer, then confirm which ones are already applied to your policy. It is not unusual to find that a discount you qualified for months ago was never added.
Improve The Factors That Drive Your Rate
Some of the biggest levers on your premium have nothing to do with bundling at all. They are tied to you, your vehicle, and your record.
Your credit-based insurance score is one of the strongest predictors carriers use in most states. Paying down revolving balances, disputing errors on your credit report, and avoiding new credit inquiries in the months before you shop can meaningfully lower your quotes. This is not about your general creditworthiness; it is about the specific insurance score model your state allows carriers to use.
Your driving record matters just as much. A single at-fault accident or moving violation can raise rates for three to five years. Many states allow you to take a defensive driving course to remove points, and some carriers offer a discount for completing one even when points are not at stake. If a ticket is eligible for dismissal through traffic school, taking that option usually pays for itself many times over in future premiums.
The vehicle itself also drives cost. Sports cars, vehicles with expensive parts, and models with high theft rates cost more to insure. If you are shopping for a new car, checking insurance costs before you buy can save you thousands over the life of the loan. You can review our guide on lowering your auto insurance premium legally and fast for more tactics that work alongside the ones here.
Adjust How And When You Pay
Payment structure is an underrated savings lever. Most carriers charge installment fees for monthly billing, and those fees add up to real money over a year. Switching to a paid-in-full plan typically removes those fees and unlocks an additional discount, often 5 to 10 percent.
If paying six months upfront is not feasible, ask about a two-payment plan or a shorter installment schedule. Even reducing the number of payments from twelve to four can cut fees significantly. Pair this with autopay and paperless billing, and you have trimmed administrative costs without touching your coverage at all.
It also helps to time your shopping. Rates fluctuate, and carriers sometimes run promotional periods. If your renewal is two months away, start gathering quotes about six weeks out so you have time to negotiate or switch before the new term begins.
When A Bundle Actually Helps, And When It Does Not
Bundling is not inherently bad. For homeowners and renters with clean records, combining auto and property policies can produce a genuine multi-policy discount, sometimes 5 to 25 percent on the auto side. The problem is that the bundle discount is calculated on top of whatever base rate the carrier already charges, and that base rate may be higher than a competitor's non-bundled rate.
A simple test clarifies the decision. Get a quote for auto alone from Carrier A and a bundled quote from Carrier B. Then get an auto-only quote from Carrier B and a homeowners or renters quote from a separate Carrier C. Compare the total cost of both scenarios. If splitting the policies across two carriers costs less overall, unbundling wins even after losing the discount.
Unbundling also makes sense when your home or renters policy is with a carrier that does not write competitive auto coverage in your state, or when you have a claims history that one carrier penalizes more than another. Keeping policies separate gives you the freedom to optimize each one independently, and it prevents a single claim or non-renewal from disrupting both.
Reduce Risk Factors Within Your Control
Beyond driving and credit, a few lifestyle and household adjustments can lower your premium without any bundle:
- Add a responsible driver to your policy if it genuinely reduces household risk (rare, but possible with a spouse or parent)
- Remove drivers who no longer live with you or no longer use your vehicle
- Park in a garage or secured lot if available, which can reduce comprehensive premiums
- Choose a higher deductible on comprehensive only, keeping collision lower if you cannot afford a big hit
- Drop duplicate coverage such as medical payments if you have strong health insurance
Each change is small on its own. Combined, they can reshape your premium profile enough that a non-bundled policy beats a bundled one.
Put The Savings Together
Lowering car insurance premiums without bundling is a process of stacking independent wins: multiple quotes, right-sized coverage, telematics, every discount you qualify for, and a cleaner risk profile. None of these require you to move your home or renters policy, and several of them compound. A driver who shops three carriers, raises a deductible, enrolls in a safe-driving app, and claims four overlooked discounts can realistically cut a premium by 30 percent or more.
Start with the easiest steps this week: pull competing quotes, call your insurer for a discount audit, and check whether a telematics program fits your driving. Then revisit coverage limits and deductibles with a licensed agent who can explain the tradeoffs in plain language. NewAutoInsurance.com connects drivers with licensed agents for personalized quotes at no obligation, and its educational guides can help you compare options before you decide. Some agents and agencies may pay a fee to be promoted, which should be considered advertising; NewAutoInsurance.com does not endorse any specific provider. With a little methodical effort, you can keep your policies separate and still pay noticeably less.