How to Evaluate an Auto Insurance Company Without Brand Bias
Evaluate insurers on data, not logos. Call 8332147506 for help comparing quotes and avoiding brand bias.
By Isobel Crane
Your neighbor swears by one carrier. Your coworker insists another is the only option worth considering. A flashy television ad tells you a third company will save you hundreds. Meanwhile, the quote you pulled online last night looks nothing like any of those recommendations. This is the reality of shopping for car insurance in the United States: brand familiarity shapes decisions long before the actual policy details enter the conversation. The problem is that brand recognition and policy value are two very different things. A company can dominate the airwaves and still offer you a mediocre rate with restrictive claims handling, while a lesser known regional carrier might deliver better coverage at a lower price.
Learning how to evaluate an auto insurance company without brand bias is one of the most financially useful skills a driver can develop. It means setting aside logos, jingles, and celebrity endorsements and instead judging insurers on measurable factors: financial strength, complaint ratios, coverage flexibility, claims service, and the actual numbers on your quote. This guide walks through a practical framework you can apply to any carrier, whether it is a household name or a company you have never heard of. The goal is not to distrust big brands or to champion small ones. The goal is to let evidence, not marketing, drive your decision.
Why Brand Bias Costs Drivers Money
Brand bias in insurance shows up in subtle ways. Drivers often assume that a company with a large advertising budget must be more reliable, or that a well known name will automatically process claims faster. Neither assumption holds up under scrutiny. Advertising spend is a marketing metric, not a service metric. In fact, some of the heaviest advertisers in the auto insurance space have faced regulatory scrutiny over claims practices, while many mid-sized and regional carriers quietly earn high satisfaction scores year after year.
There is also a pricing dimension. Insurers use proprietary rating models, and those models weight factors differently from company to company. Your driving record, ZIP code, vehicle, credit based insurance score (where permitted), and coverage selections interact with each carrier's unique algorithm. The practical result is that the same driver can receive quotes that vary by hundreds or even thousands of dollars per year across companies. Loyalty to a brand name does not protect you from that variance. Only comparison does.
Finally, brand bias creates a false sense of security. When you choose a carrier because you recognize the name, you may skip the steps that actually protect you: reading the policy language, checking the complaint index, and verifying that the coverage limits match your financial exposure. A familiar logo on an inadequate policy is still an inadequate policy.
The Core Framework: Five Objective Criteria That Matter
Evaluating an insurer without brand influence requires a repeatable process. The following five criteria cover the factors that genuinely affect your experience and your wallet. Apply them to every company you consider, and score each one consistently so you can compare apples to apples.
- Financial strength and claims paying ability. Check ratings from independent agencies such as AM Best, S&P Global, and Moody's. A strong rating indicates the company can meet its obligations, including paying large claims after a serious accident.
- Complaint history and regulatory record. Every state insurance department tracks complaints. The National Association of Insurance Commissioners (NAIC) publishes a complaint index that normalizes complaints by market share, so you can see whether a carrier generates more or fewer grievances than expected for its size.
- Coverage options and policy flexibility. Look at what the company actually offers: liability limits, uninsured and underinsured motorist coverage, comprehensive and collision deductibles, rideshare endorsements, and add-ons like rental reimbursement or roadside assistance.
- Claims service and digital experience. Investigate how claims are filed, how long payouts typically take, and whether the company offers 24/7 support, a mobile app, or online claim tracking. Third-party studies from J.D. Power and similar research firms can supplement your own research.
- Price relative to coverage and service. Price matters, but only in context. A cheap policy with poor claims handling is not a bargain. Compare quotes at identical coverage levels so the price comparison is meaningful.
Notice that none of these criteria involve brand recognition. A company's advertising presence tells you how much it spends on marketing, not how well it will treat you after a fender bender. Using this framework, a driver can evaluate a regional carrier and a national carrier on the same terms.
Reading the Numbers Behind the Name: Financial Ratings and Complaint Data
Financial strength ratings are the closest thing the insurance industry has to an objective scorecard. AM Best, for example, assigns letter grades based on a company's balance sheet, operating performance, and business profile. A rating in the secure range (typically A- or higher from AM Best) suggests the insurer is financially capable of honoring its commitments. This matters most in catastrophic scenarios: a multi-car accident, a total loss, or a liability claim that exceeds typical policy limits. If the insurer cannot pay, your policy is only as good as the paper it is printed on.
Complaint data adds a second layer of evidence. The NAIC complaint index is particularly useful because it adjusts for market share. A complaint index of 1.0 means the company receives the expected number of complaints for its size. A score above 1.0 suggests more complaints than expected; below 1.0 suggests fewer. When you see a company with a low complaint index and strong financial ratings, that combination is a meaningful signal regardless of whether the brand is famous.
State insurance departments also publish complaint records, and some provide detailed breakdowns by complaint type (claims handling, billing disputes, underwriting). If you are evaluating a smaller regional carrier, its state regulator's data may be more detailed than national datasets. Take advantage of that. A regional insurer with a clean complaint record in your state may serve you better than a national brand with a spotty one.
Coverage Comparison: The Details Brands Do Not Advertise
Television ads rarely explain the difference between split limits and combined single limits, or why uninsured motorist coverage matters in states with high rates of uninsured drivers. Yet these details determine whether your policy actually protects you. When evaluating any insurer, compare the following coverage elements side by side:
- Liability limits: State minimums are rarely enough. Compare what each insurer offers at higher limits and how the pricing scales.
- Uninsured and underinsured motorist coverage: This protects you when the at-fault driver has no insurance or insufficient coverage. Availability and pricing vary significantly by carrier.
- Comprehensive and collision deductibles: Higher deductibles lower premiums but increase out-of-pocket costs after a claim. Compare the full deductible menu each insurer offers.
- Add-ons and endorsements: Rental reimbursement, roadside assistance, gap coverage, and OEM parts endorsements are not standard everywhere.
- Discounts and bundling options: Multi-policy discounts, safe driver discounts, and paid-in-full discounts can meaningfully change the effective price. For a closer look at how bundling works across policy types, see this guide on auto insurance for renters and homeowners, which explains how combining policies can close coverage gaps and reduce premiums.
The insight here is that coverage breadth is often more important than brand name. An insurer that offers robust uninsured motorist coverage and flexible deductibles may protect you better than a famous carrier with bare-bones options. Read the declarations page and policy jacket for each quote, not just the marketing summary.
Claims Experience: Where Brand Reputation Meets Reality
Claims handling is where the gap between advertising and actual performance becomes most visible. A company can promise "fast, fair claims" in every commercial, but the lived experience depends on adjuster staffing, digital tools, and internal processes. To evaluate claims service objectively, look at multiple sources: third-party satisfaction studies, online reviews (read them critically, since unhappy customers post more often than satisfied ones), and your state insurance department's complaint data specifically filtered for claims related complaints.
Also consider the mechanics of filing a claim. Does the insurer offer a mobile app for photo estimates? Is there a 24/7 phone line? Can you track a claim status online? For drivers with commercial vehicles, motorcycles, or RVs, claims complexity increases, and the insurer's specialized experience matters more. If you operate a business vehicle or ride a motorcycle, ask specifically how the carrier handles those claim types. A generalist insurer may struggle with a commercial auto claim that a specialist handles routinely.
One practical test: call the insurer's claims line before you buy. Note how long you wait, how knowledgeable the representative seems, and whether they can answer questions about your specific coverage scenario. This small experiment reveals more about service culture than any advertisement.
How to Run a Brand-Blind Quote Comparison
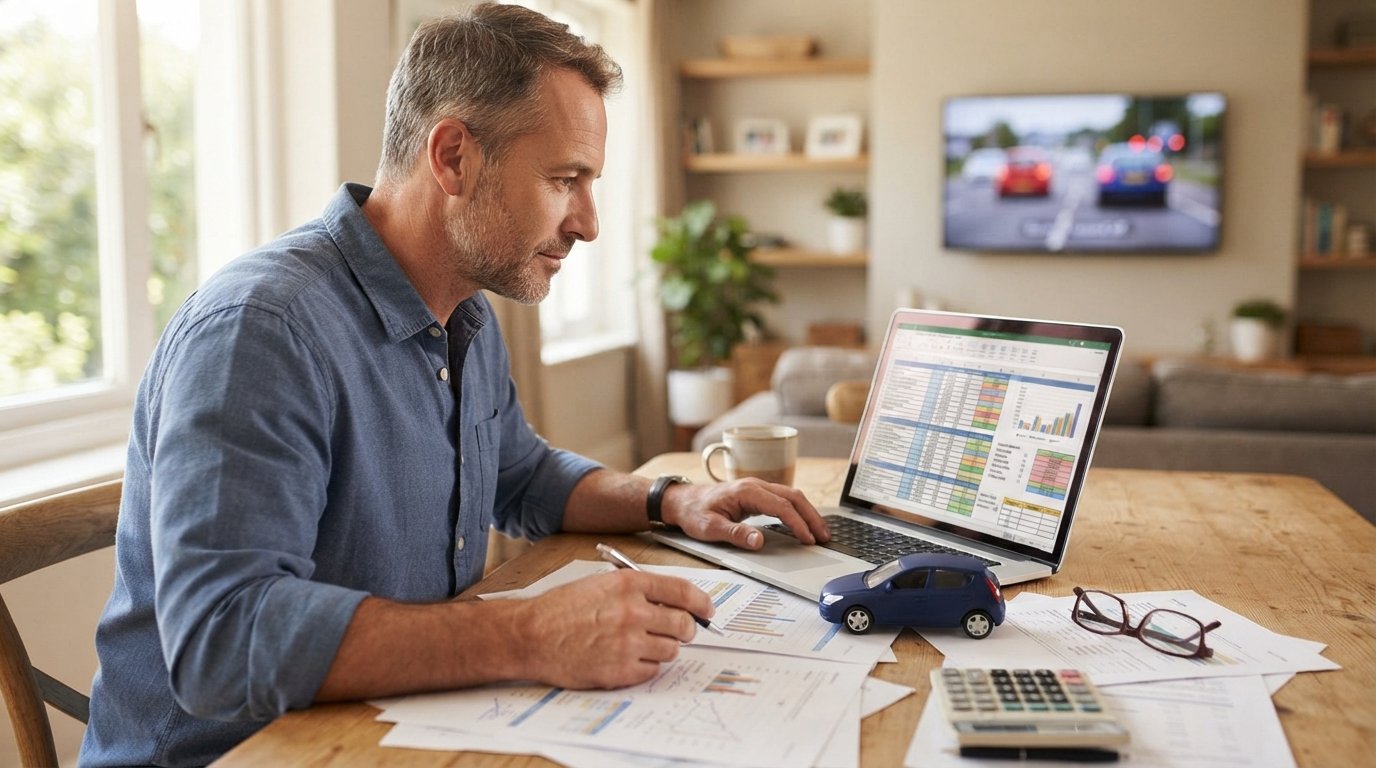
The most effective way to eliminate brand bias is to structure your shopping process so that brand names are the last thing you consider, not the first. Here is a step by step approach that any driver can follow.
- Define your coverage requirements first. Decide on liability limits, deductible levels, and optional coverages before you request a single quote. Write these down so every quote is evaluated against the same standard.
- Gather quotes from a mix of carriers. Include at least one large national brand, one mid-sized or regional carrier, and one direct-to-consumer insurer. Use an independent comparison platform to streamline the process. For example, FreeAutoInsuranceQuotesOnline lets drivers request no-obligation quotes from multiple carriers so they can compare rates and coverage side by side without starting from a brand preference.
- Normalize the quotes. Adjust each quote so the coverage limits, deductibles, and add-ons match your predefined requirements. A quote that looks cheap may simply have lower limits.
- Score each carrier on the five criteria. Financial strength, complaint index, coverage flexibility, claims service, and price. Use a simple one to five scale for each and total the scores.
- Review the policy documents, not the brochures. Request sample policy language or the full policy jacket for the top two or three contenders. Look for exclusions that could affect you.
- Make the decision based on scores, not slogans. If the highest scoring carrier is one you had never heard of before this process, that is a valid outcome and often a financially smart one.
This process works because it forces you to engage with substance before style. By the time you see the company name attached to a score, you have already evaluated the factors that actually matter. The name becomes a label on a result, not a reason for the result.
Special Cases: When Brand Bias Is Hardest to Avoid
Certain situations make brand bias more tempting. Drivers with classic or antique cars, for instance, often gravitate toward well known collector car insurers without comparing specialty options. Motorcycle riders may default to the brand their dealer recommends. Commercial vehicle owners may stick with the carrier their fleet has always used. In each case, the same framework applies: check financial strength, complaint history, coverage fit, and claims experience for the specialty line, not just the general auto product.
Renters and homeowners face a related trap. Bundling auto and home or renters insurance is a legitimate savings strategy, but it can also lock drivers into a carrier that is strong in homeowners insurance and weak in auto claims. Evaluate each policy on its own merits, then evaluate the bundle discount as a separate financial decision. A large bundle discount on a mediocre auto policy may still cost more than a competitive standalone auto policy paired with a separate home policy.
Newer drivers and those with imperfect credit or driving records also face limited options, which can push them toward the first brand that will accept them. Even here, comparison matters. Non-standard insurers vary widely in pricing and service, and the difference between the best and worst option in that segment can be substantial.
Building a Repeatable Evaluation Habit
Evaluating an auto insurance company without brand bias is not a one-time exercise. Rates change, claims practices evolve, and your own circumstances shift, whether you move to a new state, add a teenage driver, or buy a different vehicle. A practical habit is to re-run a brand-blind comparison every 12 to 24 months, or whenever a major life change occurs. You do not necessarily need to switch carriers each time, but you should know whether your current policy still represents competitive value.
Keep a simple file with your coverage requirements, the scores you assigned to each carrier, and the quotes you received. When renewal time arrives, compare the new premium against your file. If your insurer raises rates significantly without a corresponding change in your risk profile, that is a signal to re-shop. If a competitor now offers better coverage at a similar price, you have the evidence to make a switch confidently.
Ultimately, the drivers who get the best value from auto insurance are not the ones who are most loyal to a brand. They are the ones who treat every carrier as an unknown until the data says otherwise. Financial ratings, complaint indexes, coverage details, and claims performance do not care about advertising budgets. Use them, and your decision will be based on what protects you rather than what you recognize.