Does Auto Insurance Cover Rental Car Damage?
Does auto insurance cover rental car damage? Find out what transfers, what does not, and how to skip costly rental waivers. Call 8332147506 for guidance.
By Olivia Martin
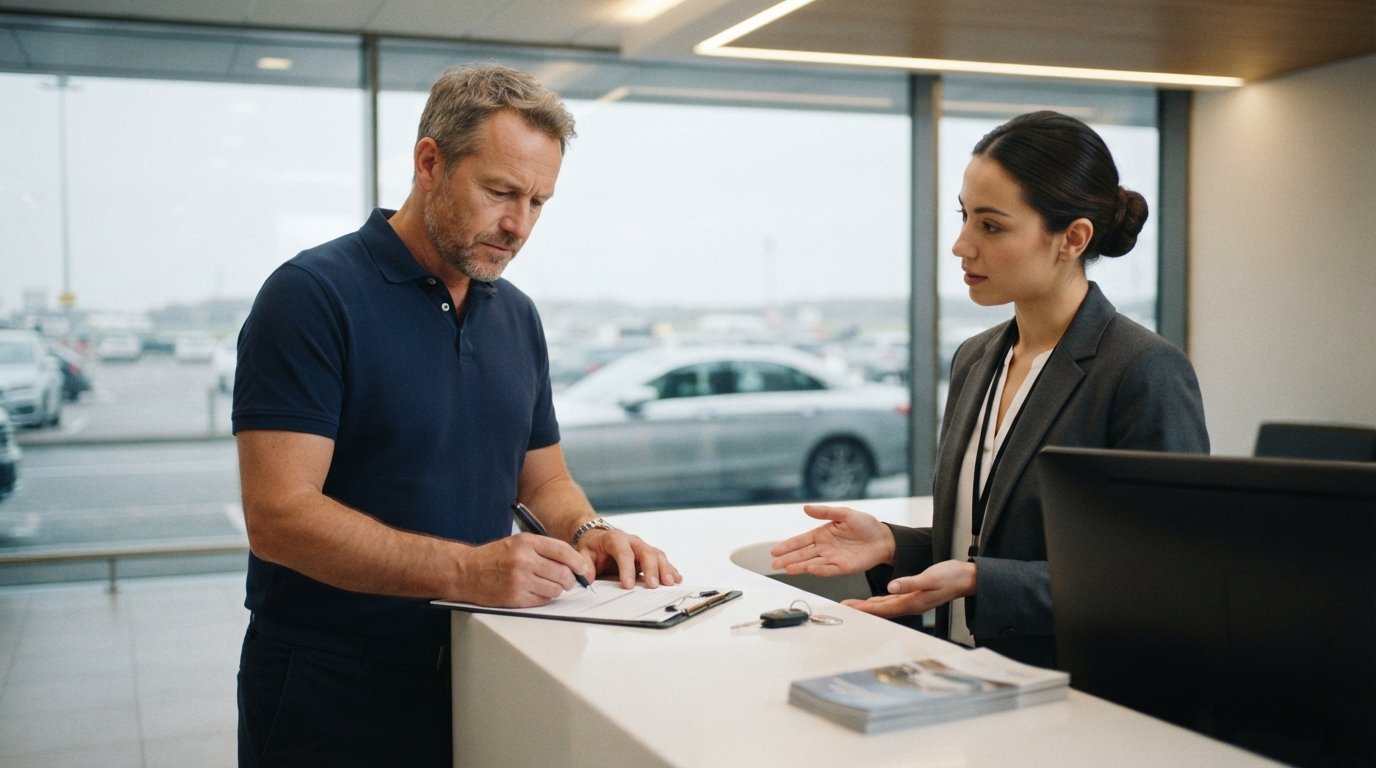
You are standing at the rental counter after a long flight. The agent slides a form across the desk and asks the question that trips up millions of drivers every year: do you want the collision damage waiver? It costs $15 to $30 per day, and if you decline it, you are on the hook for any scratches, dents, or cracked windshields. But here is the good news most travelers never hear: your own auto insurance policy may already cover rental car damage, which means you could skip that expensive counter add-on and save hundreds on a week-long trip.
The answer to does auto insurance cover rental car damage is not a simple yes or no. It depends on the coverage types you carry, the reason for your rental, and whether your policy extends to temporary vehicles. Understanding these details before you travel can save you serious money and prevent a financial headache if something goes wrong on the road.
How Your Personal Auto Policy Treats Rental Cars
Most standard personal auto insurance policies in the United States extend your existing coverage to rental cars, as long as you are driving a private passenger vehicle for personal use. This means the liability, collision, and comprehensive coverage you already pay for can follow you into a rental car. The key phrase here is "private passenger vehicle," because commercial rentals, moving trucks, and exotic cars often fall outside this protection.
Liability coverage is the most commonly extended protection. If you cause an accident in a rental car, your bodily injury and property damage liability limits apply just as they would in your own vehicle. This is critical because rental companies rarely include adequate liability protection in the base rate, and state minimums may not be enough if you injure someone or damage expensive property.
Collision and comprehensive coverage are where things get more interesting. If you carry these coverages on your personal policy, they typically transfer to a rental car. Collision pays for damage to the rental vehicle if you hit something or someone, while comprehensive covers theft, vandalism, fire, and weather-related damage. Without these, you would be personally responsible for the full value of the rental car, which could easily reach $30,000 or more.
What Determines Whether Your Policy Covers a Rental
Not every driver gets the same rental car protection, even with identical coverage types. Several factors influence whether your policy will pay a claim after rental car damage.
First, your deductible still applies. If you have a $500 deductible on collision coverage, you pay the first $500 of rental car damage before your insurer covers the rest. This is often far less than the $2,000 to $3,000 deductible that rental companies charge through their damage waivers, but it is still real money you need to have available.
Second, the type of rental matters. Personal auto policies generally cover passenger cars, minivans, and SUVs rented for leisure or personal errands. They typically do not cover box trucks, cargo vans, or vehicles rented for business purposes. If you are renting a car for a work trip and plan to use it for business activities, your personal policy may deny the claim entirely.
Third, the driver matters. Only drivers listed on your policy are covered. If you let your brother-in-law drive the rental car and he is not on your policy, your insurer can deny the claim. Rental companies also require authorized drivers, so an unlisted driver creates two problems at once.
Finally, your policy territory matters. Coverage usually applies within the United States and Canada. If you rent a car in Europe, Mexico, or the Caribbean, your personal auto policy almost certainly will not protect you. You would need to rely on the rental company's coverage or purchase a travel insurance policy that includes rental car protection.
When Your Credit Card Covers the Gap
Many credit cards advertise rental car insurance as a perk, and this can be a valuable secondary layer of protection. However, credit card coverage works differently from your auto policy, and understanding the distinction helps you avoid costly mistakes.
Credit card rental car coverage is typically secondary to your personal auto insurance. That means your auto insurer pays first, and the credit card benefit picks up what remains, such as your deductible. Some premium cards offer primary coverage, which pays before your auto insurer and keeps your policy claims record clean. Primary coverage is far more valuable because it prevents a rental car claim from raising your personal premiums.
Credit card coverage also comes with significant limitations. It usually excludes trucks, vans, and luxury vehicles. It does not cover liability, meaning if you injure someone, your personal policy must respond. It also requires you to decline the rental company's collision damage waiver and pay with the eligible card. If you accept the waiver, the credit card benefit becomes void.
Here is a quick breakdown of how the three main protection options compare:
- Personal auto policy: Extends liability, collision, and comprehensive coverage, applies your deductible, excludes business use and exotic vehicles.
- Credit card benefit: Secondary or primary coverage for damage only, no liability protection, requires declining the rental waiver.
- Rental company waiver: No deductible, covers damage and loss of use, but costs $15 to $30 per day and may not cover liability.
The best strategy often combines your personal auto policy with a primary credit card benefit. This gives you liability protection from your insurer and damage protection from your card without touching your collision deductible. Before relying on either, call your insurer and your credit card company to confirm exactly what is covered.
Steps to Confirm Your Coverage Before You Rent
Guessing whether your auto insurance covers rental car damage is a recipe for financial stress. A five-minute phone call before your trip can give you complete clarity and confidence. Follow these steps to verify your protection.
- Call your insurance agent or customer service line and ask whether your policy extends to rental cars. Confirm which coverage types transfer and what your deductible is.
- Ask specifically about liability limits and whether they apply to rentals. Some policies cap rental liability or exclude it entirely.
- Contact your credit card issuer and ask whether your card offers primary or secondary rental coverage and what vehicles are excluded.
- Check whether your rental is for personal or business use. If business, ask your employer whether their commercial policy covers the rental.
- Review your travel destination. If renting outside the United States or Canada, purchase separate rental car coverage.
After completing these steps, you will know whether to accept or decline the rental company's damage waiver. In most cases, drivers with full coverage on their personal policy can safely decline the waiver and save $100 or more on a weekly rental.
Common Situations That Change the Answer
Real-world rental scenarios rarely fit neatly into a single rule. Certain situations create exceptions that can leave you unprotected if you assume your policy will handle everything.
Business rentals are one of the biggest gray areas. If you rent a car for a work trip and your employer does not provide commercial coverage, your personal policy may deny a claim because the vehicle was used for business purposes. Some insurers make exceptions for occasional business use, but you must confirm this in writing before you drive off the lot.
Renting a vehicle while your own car is in the shop for repairs is another common scenario. In this case, your policy almost always extends coverage because the rental is a temporary substitute for your insured vehicle. This is one of the clearest situations where your auto insurance covers rental car damage without question.
Peer-to-peer rental services like Turo create unique challenges. These platforms often provide their own protection plans, and your personal auto policy may or may not respond. Many insurers treat peer-to-peer rentals as commercial transactions, which means your personal coverage could be void. Always read the platform's terms and confirm with your insurer before booking.
If you are a renter or homeowner, bundling your auto insurance with your renters or homeowners policy can simplify your coverage and reduce costs. Our guide on auto insurance for renters and homeowners explains how bundling can close coverage gaps and lower your premiums, which matters when you are trying to protect yourself both at home and on the road.
How to Handle a Rental Car Claim
If you damage a rental car and plan to file a claim, acting quickly and documenting everything protects your interests. Rental companies move fast to charge your credit card for damages, sometimes before you even return home.
Start by notifying your insurer immediately. Most policies require prompt reporting of accidents, and delays can give your insurer grounds to deny the claim. Provide the rental agreement, photos of the damage, and a police report if one was filed. Your insurer will assign an adjuster to assess the damage and communicate with the rental company.
Be aware that rental companies may charge for loss of use, which is the revenue they lose while the damaged car sits in the shop. Many personal auto policies do not cover loss of use, so you could owe this amount out of pocket. Some credit card benefits cover loss of use, which is another reason to use a card with primary rental coverage.
Administrative fees and diminished value claims are also common. Rental companies may charge processing fees, and they may argue the car is worth less after an accident. Your insurer will negotiate these charges, but you should review every line item and dispute anything that seems inflated.
Getting the Right Coverage for Your Situation
Every driver has different needs, and the right rental car protection depends on your policy, your travel habits, and your risk tolerance. If you rent cars frequently, carrying collision and comprehensive coverage on your personal policy is almost always worth the cost. The premium increase is small compared to the daily cost of rental waivers over multiple trips.
If you rarely rent cars and do not carry collision coverage, a primary credit card benefit or a standalone rental car insurance policy may be a smarter choice. These options provide targeted protection without raising your annual auto premium.
Comparing quotes from multiple carriers is the most reliable way to find affordable coverage that includes rental car protection. You can get free auto insurance quotes online from multiple carriers in minutes, which lets you see exactly how much it costs to add collision and comprehensive coverage to your policy. With that information in hand, you can decide whether your auto insurance covers rental car damage well enough to skip the counter waiver on your next trip.
The next time a rental agent asks whether you want the damage waiver, you will have a confident answer. Check your policy, confirm your credit card benefits, and drive away knowing exactly who pays if something goes wrong.