Car Theft Insurance Coverage and Prevention Guide
Understand car theft insurance coverage and prevention, from comprehensive claims to anti-theft discounts. Call 8332147506 for a personalized quote review.
By Owen Calder
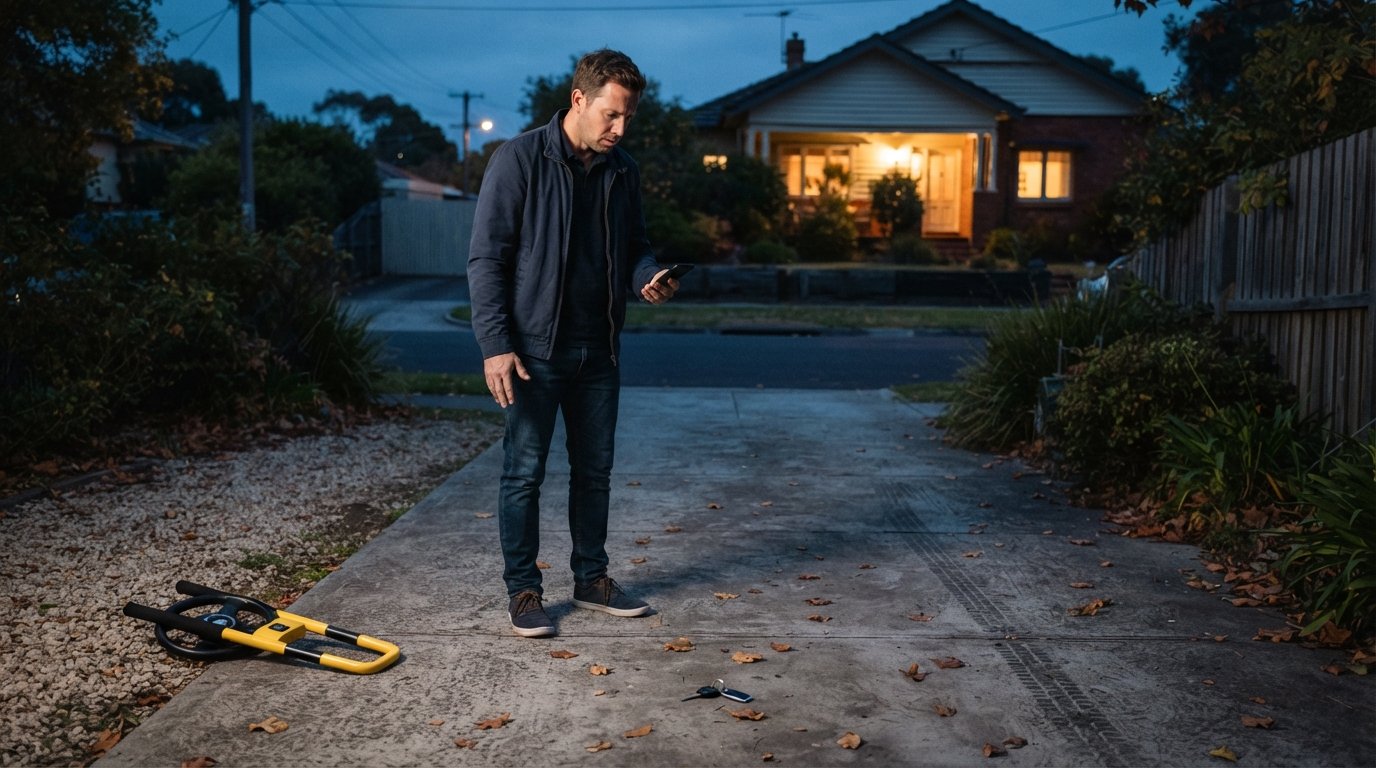
A vehicle disappearing from your driveway is one of the most stressful events a driver can face. Beyond the emotional shock, there is the immediate financial question: will your policy actually pay to replace it? Understanding how car theft insurance coverage and prevention work together is the difference between a smooth claim and a financial nightmare. The FBI estimates that a vehicle is stolen roughly every 30 seconds in the United States, and modern thieves are using increasingly sophisticated methods like relay attacks to bypass keyless entry systems. While you cannot control criminal behavior, you can control your policy structure, your parking habits, and your recovery strategy. This guide explains exactly how insurers evaluate theft claims, which coverage types pay out, and the practical steps that reduce both your risk of becoming a victim and the cost of your premium.
How Car Theft Insurance Coverage Actually Works
Many drivers assume that because they carry auto insurance, they are automatically protected if their car is stolen. That assumption is dangerous. The coverage that pays for a stolen vehicle is comprehensive coverage, which is technically an optional add-on in most states. If you only carry liability insurance (the minimum required by law in nearly every state), your policy will not pay a single dollar toward replacing a stolen car. Liability coverage pays for damage you cause to others, not for your own property.
Comprehensive coverage handles a specific list of non-collision events: theft, fire, vandalism, hail, flooding, and animal strikes. When a vehicle is stolen, comprehensive coverage typically pays the Actual Cash Value (ACV) of the car at the time of the theft, minus your deductible. ACV is not what you paid for the car; it is the market value of a comparable vehicle with similar mileage and condition. This is a critical distinction. If you purchased a new car two years ago for $35,000 and it is stolen today, the insurer might pay $26,000 based on depreciation. That gap can be devastating if you still owe $30,000 on a loan.
This is where Guaranteed Asset Protection (GAP) coverage becomes relevant. GAP insurance covers the difference between what you owe on your auto loan or lease and what the insurer pays out as ACV. If your car is stolen and deemed a total loss, GAP kicks in to cover the shortfall so you are not left making payments on a vehicle you no longer possess. It is often rolled into dealership financing, but you can usually purchase it cheaper through your insurance carrier.
There is also the waiting period issue. Most insurers require a police report and a waiting period (often 14 to 30 days) before they will settle a theft claim as a total loss. This is because many stolen vehicles are recovered within the first few weeks, albeit sometimes damaged. If your car is recovered, the insurer will pay for repairs under your comprehensive coverage rather than cutting a check for the full value. If it is never found, the claim transitions to a total loss settlement.
Beyond the vehicle itself, comprehensive coverage also pays for personal belongings stolen from the car, though usually up to a limited amount (often $200 to $500). If you have expensive electronics or tools in your vehicle, your homeowners or renters insurance policy may offer higher limits for off-premises property, but you will need to file a separate claim and pay a separate deductible. It is worth checking whether your renters or homeowners policy offers better protection for high-value items left in the car.
What Determines Your Theft Coverage Payout
When you file a theft claim, the adjuster does not simply write a check for the sticker price. Several factors influence the final settlement amount, and understanding them helps you set realistic expectations. The most obvious factor is your deductible. If you chose a $1,000 deductible to lower your monthly premium, the first $1,000 of the loss comes out of your pocket. A lower deductible means a higher payout but higher premiums, so there is a trade-off to evaluate based on how much risk you can absorb.
Another major factor is the condition and mileage of your vehicle. A 2018 sedan with 90,000 miles will command a much lower ACV than the same model with 30,000 miles. Insurers use third-party valuation services to determine market value, and you have the right to dispute their offer if you can provide evidence of comparable listings or recent maintenance that increases the car's worth. Documentation matters: keep records of oil changes, new tires, and any aftermarket upgrades, as these can support a higher valuation.
Your claims history also plays a role, though not in the way many people expect. A single theft claim is generally treated as a not-at-fault loss, meaning it should not raise your rates as much as an at-fault accident would. However, some insurers may still apply a surcharge or remove a claims-free discount. If you have multiple comprehensive claims in a short period, the insurer may view you as high-risk and increase your premium or even decline to renew your policy.
Finally, the location of the theft matters. If your car is stolen from a high-crime area, the insurer may scrutinize the claim more closely, though they cannot deny coverage solely based on geography. If the car was stolen while you were using it for business purposes (like rideshare driving) and you did not have commercial coverage, the claim could be denied. Personal auto policies typically exclude business use, so if you drive for a living, you need a commercial policy or a rideshare endorsement.
Prevention Strategies That Reduce Risk and Premiums
Prevention is not just about avoiding the hassle of a claim; it is also about lowering your insurance costs. Insurers offer discounts for anti-theft devices, and some even reduce premiums for vehicles with factory-installed tracking systems. The logic is simple: a car that is harder to steal is less likely to generate a claim. Here are the most effective prevention measures you can take, ranked by impact and cost.
- Install a vehicle tracking system. GPS trackers like LoJack or factory systems (OnStar, BMW Assist) dramatically increase the chance of recovery. Many insurers offer discounts of 5% to 15% for these devices.
- Use a steering wheel lock or pedal lock. These visible deterrents make your car a less attractive target. They are low-tech but highly effective against opportunistic thieves.
- Park in well-lit, secure areas. Garages, gated lots, and areas with security cameras are far safer than street parking. If you must park on the street, choose a spot near a light or a busy pedestrian area.
- Never leave keys or valuables in the car. Keyless entry systems are vulnerable to relay attacks, so consider storing your key fob in a signal-blocking pouch at home.
- Enable factory anti-theft features. Many modern cars have immobilizers, alarms, and automatic door locking. Make sure these are activated and functioning.
Beyond these physical measures, your driving and parking habits matter. Avoid leaving your car running unattended, even for a quick errand. In cold climates, this is a common mistake that leads to theft. Also, be cautious about where you leave your registration and insurance documents; thieves can use these to sell the car or commit identity fraud. Keep them in a secure place, not the glove box.
Insurance companies also reward safe behavior. If you have a clean driving record and a history of no claims, you may qualify for a safe driver discount or a claims-free discount. Some insurers offer a new car discount for vehicles with advanced safety features, which often include anti-theft technology. If you are shopping for a new car, check the Insurance Institute for Highway Safety (IIHS) ratings for theft deterrents; some models are statistically less likely to be stolen.
For drivers who want to compare how different carriers handle theft claims and prevention discounts, using a comparison platform can save hours of research. If you are also curious about how rental car coverage interacts with theft protection, our guide on whether auto insurance covers rental cars explains the overlap in detail.
What to Do Immediately After a Car Theft
The first 24 hours after a theft are critical for recovery and for your claim. Your actions during this window can significantly influence whether the police find your vehicle and whether the insurer processes your claim smoothly. Do not wait to see if the car reappears; act immediately.
Step 1: Call the police. File a stolen vehicle report as soon as you notice the car is missing. You will need the license plate number, VIN, make, model, and color. The police will enter the vehicle into the National Crime Information Center (NCIC) database, which alerts patrol officers and automatic license plate readers. Without a police report, your insurer will not process a theft claim.
Step 2: Notify your insurer. Call your insurance company or file a claim online as soon as possible. They will assign a claims adjuster and explain the next steps, including the waiting period for recovery. Provide the police report number and any documentation you have, such as the title, registration, and loan information.
Step 3: Contact your lender or leasing company. If you have a loan or lease, let them know the vehicle is stolen. They will want to know the status of the insurance claim and may require you to continue payments until the claim is settled. GAP coverage, if you have it, will be coordinated through the insurer.
Step 4: Gather your documentation. Locate your title, registration, loan documents, and any receipts for aftermarket upgrades. If you have photos of the car, especially showing its condition, that helps establish ACV. Also, list any personal property that was in the car at the time of theft.
Step 5: Follow up with the police and insurer. Recovery rates drop significantly after the first 48 hours, but vehicles are sometimes found weeks later. Stay in contact with the detective assigned to your case and forward any updates to your adjuster. If the car is recovered, inspect it carefully for damage and file a supplemental claim if needed.
One common mistake is assuming the insurer will handle everything. You are your own best advocate. Keep a log of all phone calls, emails, and correspondence. If the settlement offer seems low, negotiate with comparable listings from Kelley Blue Book, Edmunds, or local dealerships. You have the right to fair compensation, and insurers expect some pushback on valuation.
How Theft Claims Affect Your Premiums
A theft claim is typically classified as a not-at-fault loss, which means it should not increase your premium as much as an at-fault accident. However, that does not mean your rates will stay the same. Many insurers apply a surcharge for any comprehensive claim, including theft, especially if you have filed multiple claims in a short period. The surcharge usually ranges from 10% to 20% and may stay on your record for three to five years.
There is also the risk of losing a claims-free discount. If you were receiving a discount for having no claims, that discount will likely be removed after a theft claim. The net effect could be a premium increase even if the base rate does not change. Some insurers offer accident forgiveness or claims forgiveness programs, but these usually apply only to at-fault accidents, not comprehensive claims.
On the positive side, a theft claim does not typically affect your ability to switch insurers. Since it is a not-at-fault loss, other carriers will still consider you a reasonable risk. However, you must disclose the claim when applying for new coverage. Failure to disclose can be considered material misrepresentation and could void your policy. If you are shopping for a new policy after a theft, be transparent and be prepared to explain the circumstances.
If you are concerned about how a theft claim might impact your rates, it helps to compare quotes from multiple carriers. Some insurers are more forgiving of comprehensive claims than others. A platform like FreeAutoInsuranceQuotesOnline allows you to request quotes from several carriers at once, so you can see which ones offer the best rates despite a prior claim.
Special Considerations for High-Risk Vehicles
Not all cars are equally likely to be stolen. Certain models, particularly pickup trucks, SUVs, and high-performance vehicles, are targeted more frequently. If you drive one of these vehicles, you may face higher comprehensive premiums or even difficulty finding coverage. Insurers use theft rate data from the National Insurance Crime Bureau (NICB) to set rates, and they may require additional anti-theft measures before issuing a policy.
If your car is on the most-stolen list, consider the following steps to keep your premium manageable:
- Install a tracking device and provide proof to your insurer. This often qualifies you for a discount and demonstrates that you are taking prevention seriously.
- Park in a garage whenever possible. Garage parking significantly reduces theft risk and may lower your premium.
- Choose a higher deductible. If you can afford to absorb more of the loss, a higher deductible lowers your monthly premium.
- Bundle your auto and home or renters insurance. Bundling discounts can offset the higher cost of insuring a high-risk vehicle.
For antique or classic cars, theft coverage works differently. These vehicles are often insured with agreed value policies rather than ACV, meaning you and the insurer agree on a specific value upfront. This is crucial because market value for a classic car can be difficult to determine. If you own a classic car, make sure your policy includes theft coverage and that the agreed value reflects current market conditions.
Motorcycles, RVs, and ATVs also have unique theft risks. Motorcycles are relatively easy to steal and often lack comprehensive coverage if the owner is trying to save money. RVs and travel trailers are often stored in unsecured lots during the off-season, making them prime targets. If you own any of these vehicles, review your policy to confirm that theft is covered and consider additional security measures like wheel locks or GPS trackers.
Building a Theft-Resilient Insurance Strategy
Ultimately, protecting yourself from car theft is a two-part equation: having the right coverage and taking prevention seriously. Comprehensive coverage is the foundation, but it is not enough if you do not understand how ACV, deductibles, and waiting periods work. GAP coverage fills a critical gap for newer vehicles, and renters or homeowners insurance can cover personal property stolen from the car.
On the prevention side, the most effective measures are often the simplest: park smart, lock up, and use visible deterrents. Technology helps, but thieves adapt quickly, so a layered approach is best. Combine a tracking system with a steering wheel lock and smart parking habits. If you drive a high-risk vehicle, invest in additional security and document everything for your insurer.
Finally, review your policy annually. As your car ages, its ACV drops, and you may no longer need GAP coverage. Conversely, if you move to a higher-crime area, you may want to lower your deductible or add more comprehensive protection. Insurance is not a set-it-and-forget-it product; it should evolve with your circumstances. By staying informed and proactive, you can protect your vehicle, your finances, and your peace of mind.